The AI buildout meets the 5% world
Market take
Weekly video_20260921
Vivek Paul
Global Head of Portfolio Strategy
BlackRock Investment Institute
SCRIPT
Header:
CAPITAL AT RISK. MARKETING MATERIAL.
Opening frame: What’s driving markets? Market take
Camera frame
Title slide: The AI buildout meets the 5% world
An accelerating AI buildout is adding pressure to already elevated government borrowing needs. We think these pressures will keep borrowing costs elevated.
1: A debt-hungry AI buildout
The scale of US financing demand is huge. Now, unprecedented AI-driven financing needs are rising sharply and scaling up that demand. We estimate annual US financing demand could reach nearly $8 trillion by 2030 as the AI boom picks up.
The key point is this: we think this financing wave has more room to run – even amid recent talk of slower frontier model development.
2: More factors at play
To be sure, other forces are also pushing yields higher. The Middle East conflict is another source of pressure, with Brent crude oil back above $100 per barrel. This comes against a backdrop of already-sticky inflation driven by a world shaped by supply – an environment we’ve long described.
Another important detail? Policymakers are limited in what they can do, which makes how they respond crucial. The Federal Reserve’s first rate hike in three years last week underscores this dynamic: it helped reestablish the Fed’s credibility.
The lesson is that credibility still matters. While policymakers can't ease the underlying competition for capital or resolve energy shortages, their policy decisions can influence market confidence.
3: Winners and losers
Who ultimately bears the higher cost of capital will vary. Companies with strong earnings and balance sheets have more room to absorb it, while leveraged borrowers are more challenged.
We stay overweight US equities and AI in this environment. In credit, higher yields have improved the income on offer, but selectivity is key. We favor attractive coupons that sit between the weakest borrowers and companies issuing the largest amount of debt.
Outro: Here’s our Market take
AI investment is fueling fierce competition for capital, made even more intense by heavy government borrowing. We stay overweight US equities and seek attractive income away from the weakest borrowers and largest debt issuers.
Closing frame: Read details: blackrock.com/weekly-commentary
An accelerating AI buildout and heavy government borrowing are intensifying competition for capital. We stay pro-risk and selective in bonds.
US two- and 10-year Treasury yields rose last week after the Fed raised interest rates. We think markets may be overinterpreting the Fed’s hawkish tone.
We eye flash PMIs for signs business activity is holding up as borrowing costs rise. US resilience would reinforce the case for rates staying higher for longer.
The Federal Reserve raised rates for the first time in three years, easing near-term credibility concerns as the US 10-year Treasury yield crossed 5%. But the hike is unlikely to end this year’s sharp rate reset. Intensifying competition for capital remains a key driver, as heavy government borrowing collides with growing AI financing needs. Sticky inflation adds pressure, keeping borrowing costs elevated. What drives yields matters. We stay risk-on and favor select credit for income.
Competing for capital
US financing demand, 2018-30
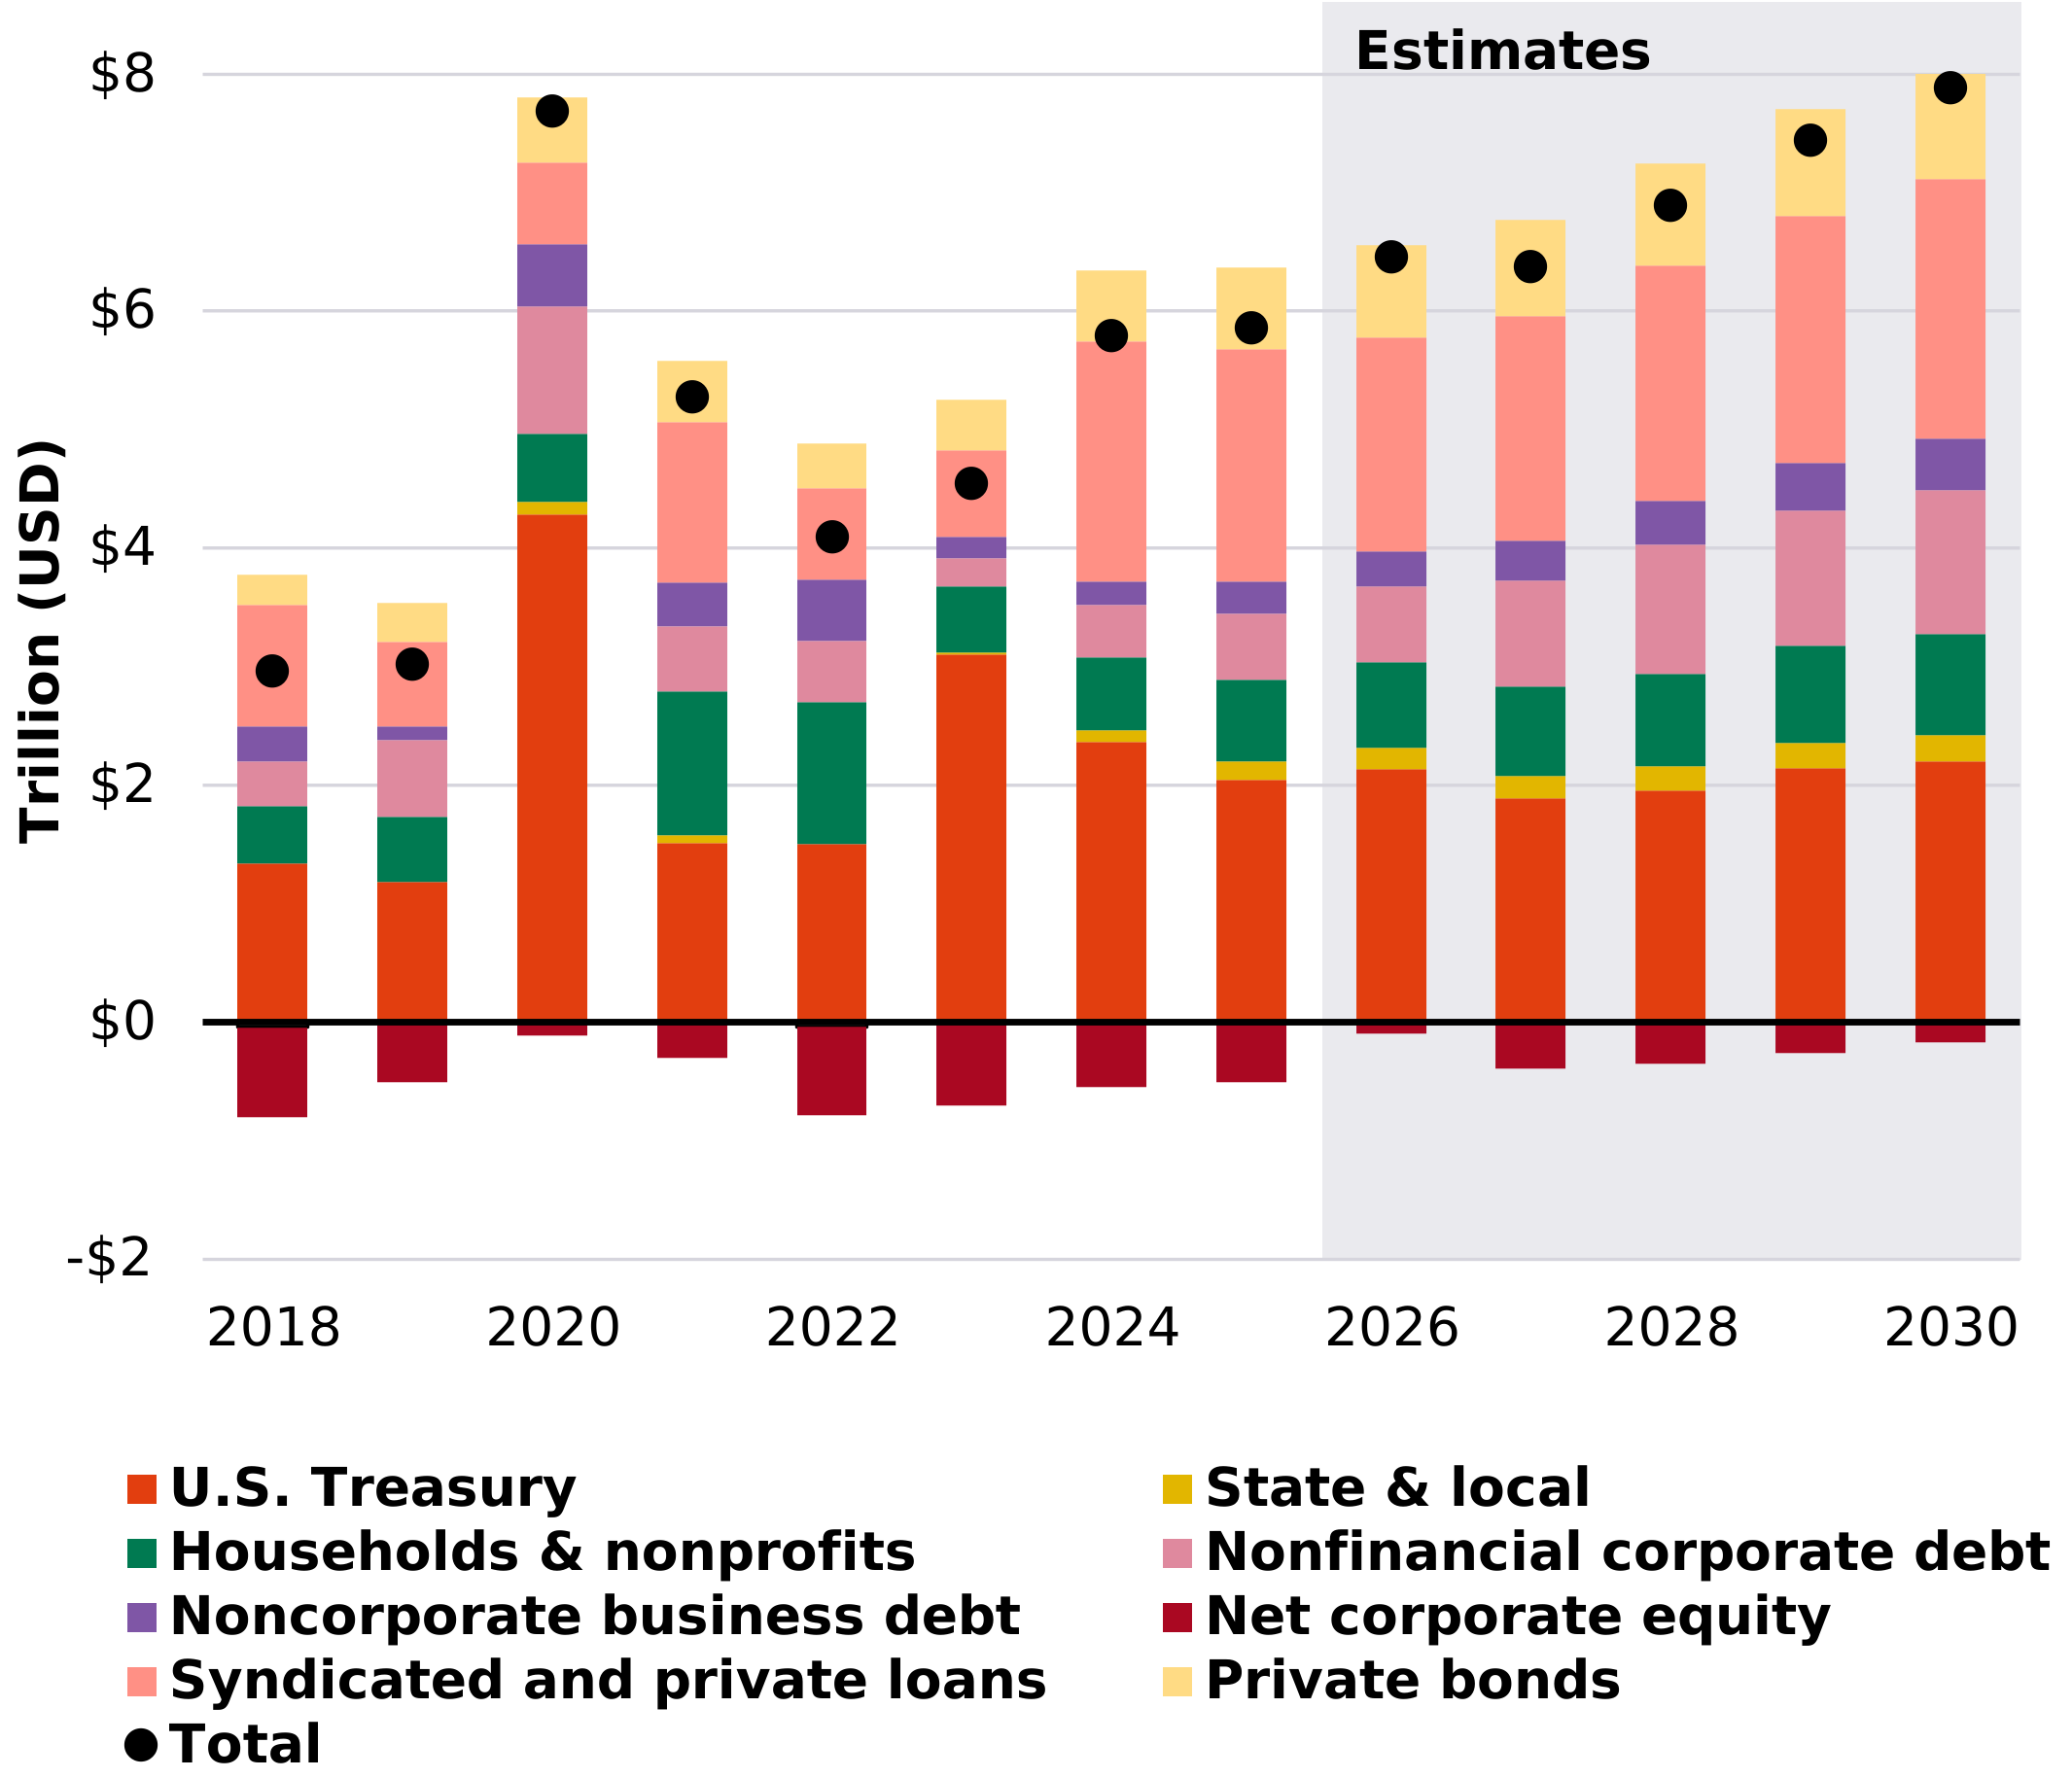
Forward-looking estimates may not come to pass. Source: BlackRock Investment Institute, US Congressional Budget Office, Federal Reserve, EIA. Note: The bars show the net demand for funding of various entities. The chart follows the Fed’s definitions for borrowers. Any AI-related financing is included in nonfinancial corporate debt and net corporate equity.
The numbers show the most intense competition for capital since the great financial crisis and the Covid-19 shock. We estimate annual US financing demand could exceed $7.5 trillion by 2030, driven mainly by the capital needs of the AI buildout. See the chart. The broader AI and data-center bond universe accounts for about 14% of US investment-grade issuance this year, up from 5% in 2025 and 1% over the previous decade. We think this financing wave has room to run. Markets have been rattled by talk of slowing frontier-model development, but we would not equate that with a slower physical AI buildout. For now, demand remains robust: most AI compute is used for inference – running existing models – rather than training new ones. With adoption still in its early stages, inference should keep driving demand for compute even if frontier-model progress slows.
That persistent demand for capital is one reason we think borrowing costs can stay elevated. But other forces could push them higher still. The Strait of Hormuz remains effectively closed amid the ongoing Middle East conflict. Brent crude has moved back above $100 a barrel, adding to already sticky inflation pressures driven by a world shaped by supply. Higher energy prices do not just lift headline inflation. If the effects spill over to wages and other costs, they can make core inflation more persistent, potentially keeping monetary policy tighter for longer.
Focus on underlying drivers
That makes what drives yields critical. Central banks shouldn’t interfere with growth-driven competition for capital and can’t resolve energy shortages, but they can prevent an unnecessary rise in term premium – the extra compensation investors demand to hold long-term bonds – by maintaining credibility. The Fed’s rate hike last week helped reestablish that credibility. So far, higher yields have mostly reflected rising real rates and expectations for tighter policy rather than a sharp increase in term premium. Attempts to suppress yields by tolerating more inflation or without addressing underlying fiscal concerns could undermine that confidence and push term premium higher. But after last week, the risk of a credibility-driven surge looks contained. That matters for our investment views: a rise in yields driven by resilient growth, investment demand and central-bank efforts to maintain credibility can coexist with our pro-risk stance. A rise increasingly driven by inflation or concerns about policy credibility would be more concerning.
Who ultimately bears the higher cost of capital will vary. Companies with strong earnings and balance sheets have more room to absorb it, while leveraged borrowers face greater pressure. We stay overweight US equities and AI, where resilient earnings can help absorb higher financing costs. This environment has also created rich opportunities across fixed income, but selectivity is key. We favor short- to medium-term government bonds on a strategic horizon of five years or longer. In credit, higher yields have improved the income on offer, but who investors lend to matters. We prefer attractive coupons away from the two extremes: the weakest borrowers and companies issuing large amounts of debt.
Our bottom line
Heavy government borrowing and the AI buildout are intensifying competition for capital. We stay pro-risk and overweight US equities while favoring attractive coupons away from the weakest borrowers and largest debt issuers.
Market backdrop
The S&P 500 was little changed last week and the two- and 10-year US Treasury yields rose, after markets took a hawkish read of Fed Chair Kevin Warsh’s post-meeting comments. The 10-year climbed back to 5%, reversing declines seen following the Fed’s first rate hike in three years. We think markets risk overinterpreting the hawkish tone of the press conference. A hike that reinforces Fed credibility against a backdrop of strong growth is, on net, good news for risk assets.
We’re watching flash PMIs for signs that business activity across the US, UK and Europe is holding up as borrowing costs rise. Further US resilience would reinforce the case for rates staying higher for longer. Final University of Michigan data will show whether September’s sharp drop in consumer sentiment and rise in inflation expectations persist – a combination we think would leave the Fed facing a tougher policy trade-off.
Week ahead
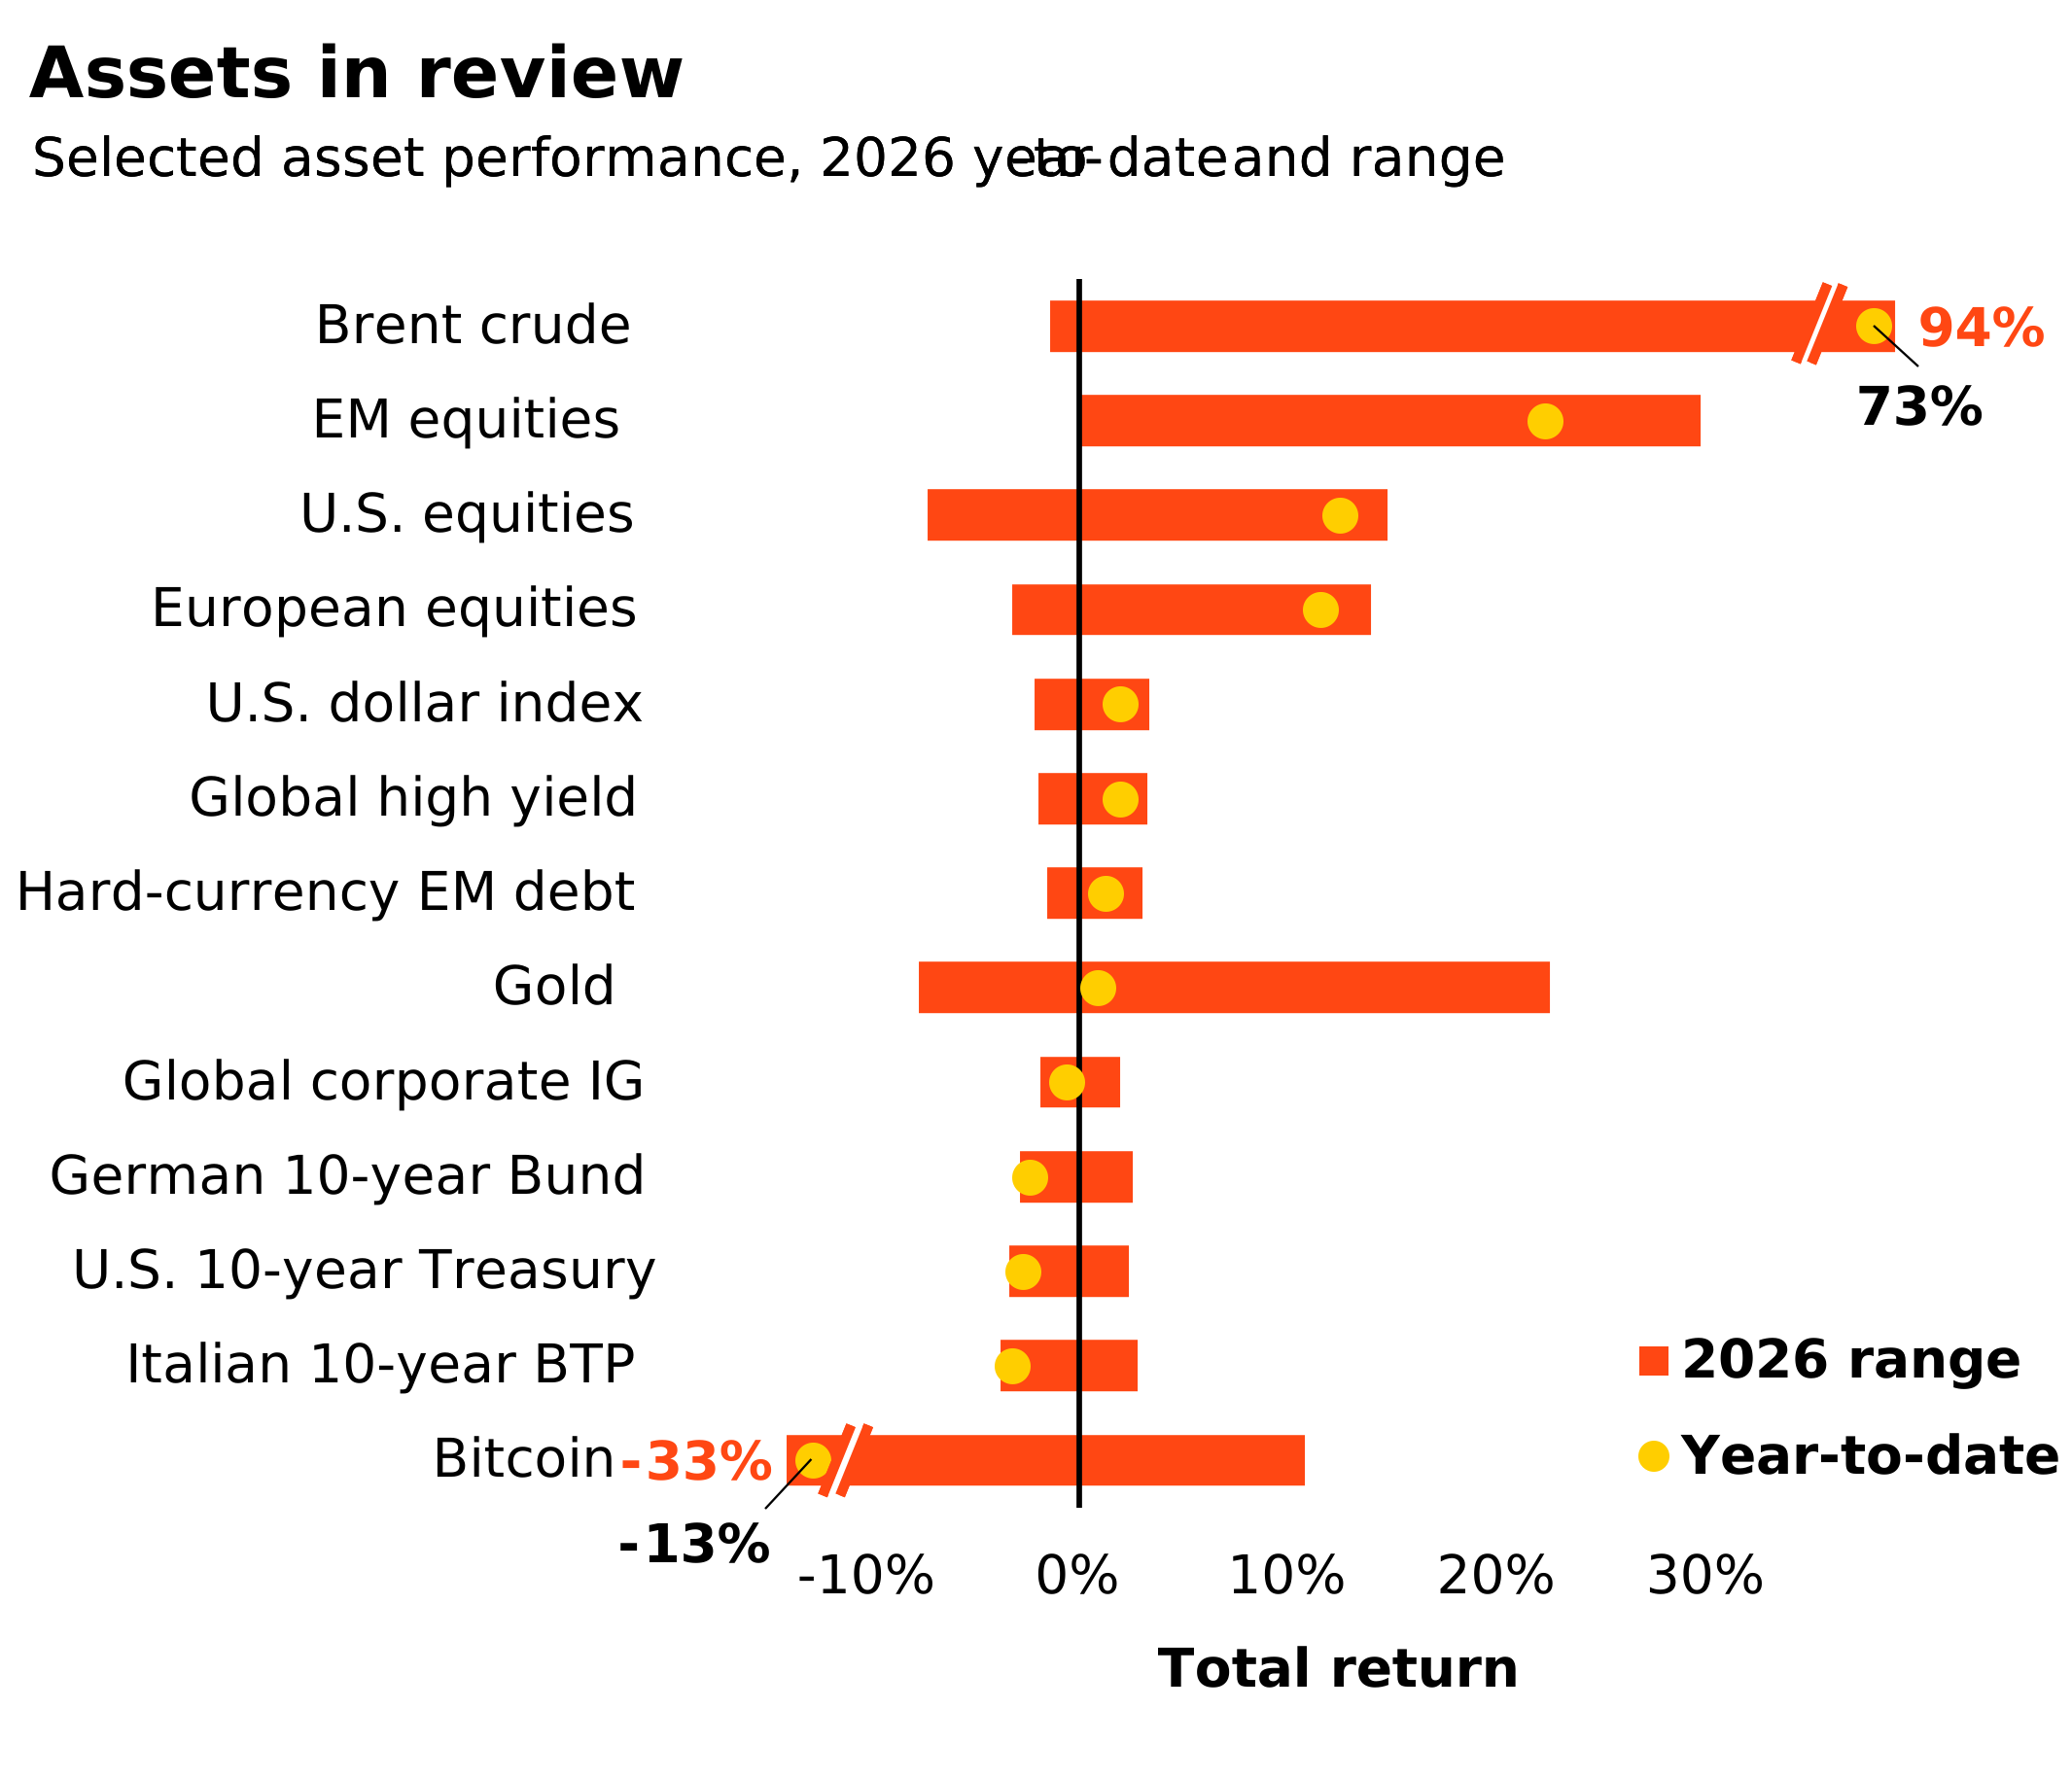
Past performance is not a reliable indicator of current or future results. Indexes are unmanaged and do not account for fees. It is not possible to invest directly in an index. Sources: BlackRock Investment Institute, with data from LSEG Datastream as of September 17, 2026. Notes: The two ends of the bars show the lowest and highest res at any point year to date, and the dots represent current year-to-date res. Emerging market (EM), high yield and global corporate investment grade (IG) res are denominated in US dollars, and the rest in local currencies. Indexes or prices used are: spot Brent crude, ICE US Dollar Index (DXY), spot gold, spot bitcoin, MSCI Emerging Markets Index, MSCI Europe Index, LSEG Datastream 10-year benchmark government bond index (US, Germany and Italy), Bloomberg Global High Yield Index, J.P. Morgan EMBI Index, Bloomberg Global Corporate Index and MSCI USA Index.
EU final consumer confidence
US, UK & EU flash PMI
Japan flash PMI
Umich final consumer sentiment
Read our past weekly commentaries here.
Intersecting mega forces
Since we launched our mega forces framework it has become clearer how their intersection shapes almost all our investment views and opens up alpha opportunities. They cut across asset class labels, spurring a rethink of portfolio construction. Investors need to be deliberate about the economic or thematic exposures they own, the vehicles they use to implement them and their investment horizons.

From drivers to portfolio expressions
Our highest conviction views, September 2026
| Driver | What we think | Portfolio expression |
|---|---|---|
| Growth and AI scarcity | The AI buildout is speeding up, making bottlenecks binding. | Overweight US and EM equities; focus on AI bottleneck opportunities: power, chips and data centers. |
| Duration and diversification | Long bonds carry high rate sensitivity and are less reliable diversifiers. | Prefer short- and medium-term government bonds over long bonds for income. |
| Credit spreads and liquidity | Selectivity is crucial amid tight spreads and uneven fundamentals. | Credit with clear cash flows, lender protections and recovery value; higher-rated high yield. |
| Inflation and scarcity | Scarcity, secure supply and power demand carry inflation risks. | Infrastructure, energy bottlenecks, EM local debt and real-asset-linked exposures. |
| Alpha opportunity | Macro outcomes matter again in the new regime. | Macro hedge funds, venture capital, market-neutral strategies, and selected private credit and non-US alpha. |
Note: Views are from a US dollar perspective, September 2026. This material represents an assessment of the market environment at a specific time and is not intended to be a forecast of future events or a guarantee of future results. This information should not be relied upon by the reader as research or investment advice regarding any particular funds, strategy or security.
Asset class implications
Six- to 12-month tactical positioning, September 2026
This shows the implementation of our key investment views from the previous page through an asset class lens.

| Asset | Tactical view | Commentary | ||||
|---|---|---|---|---|---|---|
| Equities | ||||||
| United States |  |
We are overweight. Strong corporate earnings, fueled by the AI buildout and a favorable macro backdrop, are outpacing higher interest rate expectations. | ||||
| Europe |  |
We are neutral. We would need to see more business-friendly policy and deeper capital markets for Europe to outperform. We favor financials, infrastructure, and industrials. | ||||
| UK | |
We are neutral. Valuations remain attractive relative to the US, but we see few near-term catalysts to trigger a shift. | ||||
| Japan | |
We are neutral. Strong corporate balance sheets and governance reforms remain supportive. We prefer targeted exposures to physical AI and the buildout’s bottlenecks. | ||||
| Emerging markets (EM) |  |
We are overweight. Strong earnings and cheaper valuations create opportunities. We particularly like different expressions of the AI scarcity theme across Asia and Latin America. | ||||
| China | |
We are neutral. We see opportunities in physical AI. Cheap, open-source AI could drive adoption, but that doesn’t necessarily translate into AI-provider profitability. | ||||
| Fixed income | ||||||
| Short US Treasuries | |
We are neutral. We prefer short- and medium-term Treasuries, given the attractive risk-adjusted income on offer. | ||||
| Long US Treasuries |  |
We are underweight. We see investors wanting more compensation for holding long-term bonds amid persistent inflation and high debt loads. Long-duration bonds also are a less reliable portfolio diversifier in the new regime. | ||||
| Global inflation-linked bonds | |
We are neutral. We see inflation settling above pre-pandemic levels, but markets may not price this in the near term as economic growth could slow. | ||||
| Euro area government bonds |  |
We are neutral short- and medium-term bonds. Current ECB rate pricing looks fairly valued given the balance of risks. Higher energy prices could push rates higher. We prefer to deploy risk elsewhere. | ||||
| UK Gilts | |
We are neutral. We expect periods of elevated volatility given political uncertainty, longer-term bonds making up a larger market share, and buyers becoming more price-sensitive. | ||||
| Japanese government bonds |  |
We are underweight. Rate hikes, higher global term premium and heavy bond issuance will likely drive yields up further. | ||||
| China government bonds | |
We are neutral. China bonds offer stability and diversification but developed market yields are higher. A shift in investor sentiment toward equities limits upside. | ||||
| US agency MBS | |
We are overweight. Agency MBS offer higher income than Treasuries with similar risk and may offer more diversification amid fiscal and inflationary pressures. | ||||
| Short-term IG credit | |
We are neutral. Spreads are tight due to corporate strength; they could widen if issuance increases or risk appetite shifts. | ||||
| Long-term IG credit | |
We are underweight. We prefer short-term bonds less exposed to interest rate risk over long-term bonds. | ||||
| Global high yield | |
We are neutral. High yield offers attractive income. We prefer higher-rated US and European high yield over investment grade and see dispersion of returns increasing. | ||||
| Asia credit | |
We are neutral. Overall yields are attractive and fundamentals are solid, but spreads are tight. | ||||
| Emerging hard currency | |
We are neutral. Fundamentals have improved, but we see a more attractive risk-reward profile in EM local debt. | ||||
| Emerging local currency | |
We are overweight. We like the yield relative to its volatility and improving fundamentals. | ||||
Past performance is not a reliable indicator of current or future results. It is not possible to invest directly in an index. Note: Views are from a US dollar perspective. This material represents an assessment of the market environment at a specific time and is not intended to be a forecast or guarantee of future results. This information should not be relied upon as investment advice regarding any particular fund, strategy or security.
Euro-denominated tactical granular views
Six to 12-month tactical views on selected assets vs. broad global asset classes by level of conviction, September 2026
We have lengthened our tactical investment horizon back to six to 12 months. The table below reflects this and, importantly, leaves aside the opportunity for alpha, or the potential to generate above-benchmark returns – especially at a time of heightened volatility.
| Asset | Tactical view | Commentary | ||
|---|---|---|---|---|
| Equities | ||||
| Europe ex UK | |
We are neutral. We would need to see more business-friendly policy and deeper capital markets for Europe to outperform and to justify a broad overweight. We stay selective, favoring financials, infrastructure, industrials, materials and healthcare. | ||
| Germany | |
We are neutral. Higher spending on defense and infrastructure support the corporate sector. Valuations are not stretched but neither compelling and expected earnings growth lags other countries. Light positioning means potential easing in geopolitical tensions and AI lifting industrials-driven earnings could create opportunities. | ||
| France | |
We are neutral. Strong expected earnings growth and global revenue exposure support French corporates. Valuations are less compelling, albeit not stretched versus euro area peers. Persistent political uncertainty leaves the overall risk reward balanced. | ||
| Italy | |
We are neutral. Earnings growth and momentum are strong, boosted by the significant exposure to financials, utilities and energy. Valuations are still at discount vs. peers, but not as much as in previous years. Political risk is currently low but likely to pick up ahead of 2027 elections. | ||
| Spain | |
We are overweight. Valuations remain attractive vs. peers even if relative earnings momentum has slowed. Strong domestic demand growth and exposure to fast-growing areas like Latin America support Spanish stocks. Financials, utilities and infrastructure-linked stocks would benefit from Europe’s push towards autonomy. | ||
| Netherlands | |
We are neutral. Earnings revisions in the IT sector, a large sector in the Dutch stock market is offset by other sectors seeing less favorable valuations and a weaker earnings outlook than European peers. | ||
| Switzerland |  |
We are neutral. Valuations have improved, from stretched levels, but the earnings outlook is weaker than other European markets. If global risk appetite stays strong, the index’s tilt to stable, less volatile sectors may weigh on performance. | ||
| UK | |
We are neutral. Valuations remain attractive relative to the US, but we see few near-term catalysts to trigger a shift. | ||
| Fixed income | ||||
| Euro area government bonds | |
We are neutral short- and medium-term bonds. Current ECB rate pricing looks fairly valued given the balance of risks. Higher energy prices could push rates higher. We prefer to deploy risk elsewhere. | ||
| German bunds | |
We are neutral Bunds. Current ECB rate pricing looks more fairly valued given the balance of risks. Fiscal stimulus and increased bond issuance exert upward pressure on yields, alongside inflation risks amid lingering geopolitical tensions. | ||
| French OATs | |
We are neutral. Elevated political uncertainty, high budget deficits and slow structural reforms could stoke volatility, but these risks already seem priced into OATs and we don’t expect a material worsening from here. | ||
| Italian BTPs | |
We are neutral. The spread over German bunds looks tight given Italy’s large budget deficits and growing public debt. Domestic factors remain supportive, with growth holding up relative to the rest of the euro area and local demand for BTPs solid at current yield levels. Domestic disapproval would likely prevent defense spending from reaching fiscally unstable levels. Political uncertainty is likely to increase ahead of next year’s elections. | ||
| UK gilts | |
We are neutral. We expect periods of elevated volatility given political uncertainty, longer-term bonds making up a larger market share, and buyers becoming more price-sensitive. | ||
| Swiss government bonds | |
We are neutral. The SNB seems comfortable with its medium-term inflation outlook and its current policy stance. Market pricing is broadly in line with SNB messaging. | ||
| European inflation-protected securities | |
We are neutral. We see higher medium-term inflation, but inflation expectations are firmly anchored. Cooling inflation and uncertain growth may matter more near term. | ||
| European investment grade | |
European investment grade is supported by healthy corporate sector balance sheets, contained default rates and the persistently strong demand for durable income from European households. We prefer European investment grade over the US. | ||
| European high yield | |
We are overweight. While spreads are low, the income potential remains attractive. Defaults are contained and high yield is of higher quality and less sensitive to interest rate swings compared with the US. | ||
Past performance is not a reliable indicator of current or future results. It is not possible to invest directly in an index. Note: Views are from a euro perspective, September 2026. This material represents an assessment of the market environment at a specific time and is not intended to be a forecast or guarantee of future results. This information should not be relied upon as investment advice regarding any particular fund, strategy or security.
Meet the authors

Jean Boivin

Wei Li

Vivek Paul

Ehsan Khoman
This material is for distribution to Professional Clients (as defined by the Financial Conduct Authority or MiFID Rules) and Qualified Investors only and should not be relied upon by any other persons.
Issued by BlackRock Investment Management (UK) Limited, authorised and regulated by the Financial Conduct Authority. Registered office: 12 Throgmorton Avenue, London, EC2N 2DL. Tel: 020 7743 3000. Registered in England No. 2020394. For your protection telephone calls are usually recorded. BlackRock is a trading name of BlackRock Investment Management (UK) Limited.
Past performance is not a reliable indicator of current or future results and should not be the sole factor of consideration when selecting a product or strategy.
Capital at risk. The value of investments and the income from them can fall as well as rise and is not guaranteed. You may not get back the amount originally invested. Changes in the rates of exchange between currencies may cause the value of investments to diminish or increase. Fluctuation may be particularly marked in the case of a higher volatility fund and the value of an investment may fall suddenly and substantially. Levels and basis of taxation may change from time to time.
Any research in this document has been procured and may have been acted on by BlackRock for its own purpose. The results of such research are being made available only incidentally. The views expressed do not constitute investment or any other advice and are subject to change. They do not necessarily reflect the views of any company in the BlackRock Group or any part thereof and no assurances are made as to their accuracy.
This document is for information purposes only and does not constitute an offer or invitation to anyone to invest in any BlackRock funds and has not been prepared in connection with any such offer.
© 2026 BlackRock, Inc. All Rights reserved. BLACKROCK, BLACKROCK SOLUTIONS, iSHARES, BUILD ON BLACKROCK and SO WHAT DO I DO WITH MY MONEY logo are registered and unregistered trademarks of BlackRock, Inc. or its subsidiaries in the United States and elsewhere. All other trademarks are those of their respective owners.
