AI’s rising bill of expectations
Market take
Weekly video_20261102
Devan Nathwani
Portfolio strategist
BlackRock Investment Institute
SCRIPT
Header:
CAPITAL AT RISK. MARKETING MATERIAL.
Opening frame: What’s driving markets? Market take
Camera frame
Title slide: AI’s rising bill of expectations
After two years of booming AI investment, we have seen more scrutiny on the AI theme as investors want to see the payoff. That shifting backdrop contributed to our decision to downgrade U.S. equities to neutral last month. Our conviction in AI fundamentals, however, remains intact.
1: A different backdrop
The backdrop for megacap tech looks very different from just a few months ago. Why? The earnings gap has now flipped for the first time since 2022 with the rest of the market expected to outpace the magnificent seven. AI leaders are still delivering, but their outperformance is becoming less exceptional. And with expectations already so high, investors are increasingly looking at whether monetization and cash generation can sustain investment.
2: Maintaining AI conviction
Last week’s earnings highlighted a growing tension between strong demand for AI-linked goods and services and the rising cost of meeting it. Hyperscaler spending has surged, leaving little cash surplus after capex. Each additional dollar of revenue is generating less profit, raising questions about whether returns can keep pace with soaring investment.
We do find early signs of AI adoption impacting earnings growth. Our analysis finds that companies outside big tech with higher AI adoption are on track for about 3% more earnings growth this quarter than those with lower adoption. Meanwhile rising cloud revenues also point to strong AI demand.
3: A broader view
As the AI buildout is increasingly funded by debt, leverage and funding capacity are coming into sharp focus. The buildout is adding to competition for capital and keeping upward pressure on yields. We see the recent fall in yields as a reflection of the ebbs and flows of competition for capital as markets consider any emerging constraints on deploying even more funding. As such, credit markets are a key signpost of how much more AI investment can be financed — and at what cost.
Outro: Here’s our Market take
AI faces a tougher near-term test as investor scrutiny intensifies. But our conviction in AI fundamentals remains intact, keeping us selective on where we take AI exposure.
Closing frame: Read details: blackrock.com/weekly-commentary
Investor scrutiny of AI is intensifying this earnings season. How results hold up will be key to our broader medium-term conviction in the AI transformation.
The Nasdaq posted its worst month since March 2025 as AI scrutiny intensified. We see multiple plausible outcomes for growth, profitability and returns.
We are watching October U.S. jobs data amid signs of a tight labor market in recent months. Any further wage pressure could drive core services inflation.
Four years of booming AI investment have sent earnings expectations soaring. Investors now want evidence that spending can deliver returns, especially as rising capital expenditures squeeze free cash flow, pushing it into negative territory for some firms. We recently downgraded U.S. equities to neutral to lock in profits, but our core conviction in the AI transformation remains intact. That supports our EM equity overweight through exposure to bottlenecks in the AI buildout.
Beyond the magnificent few
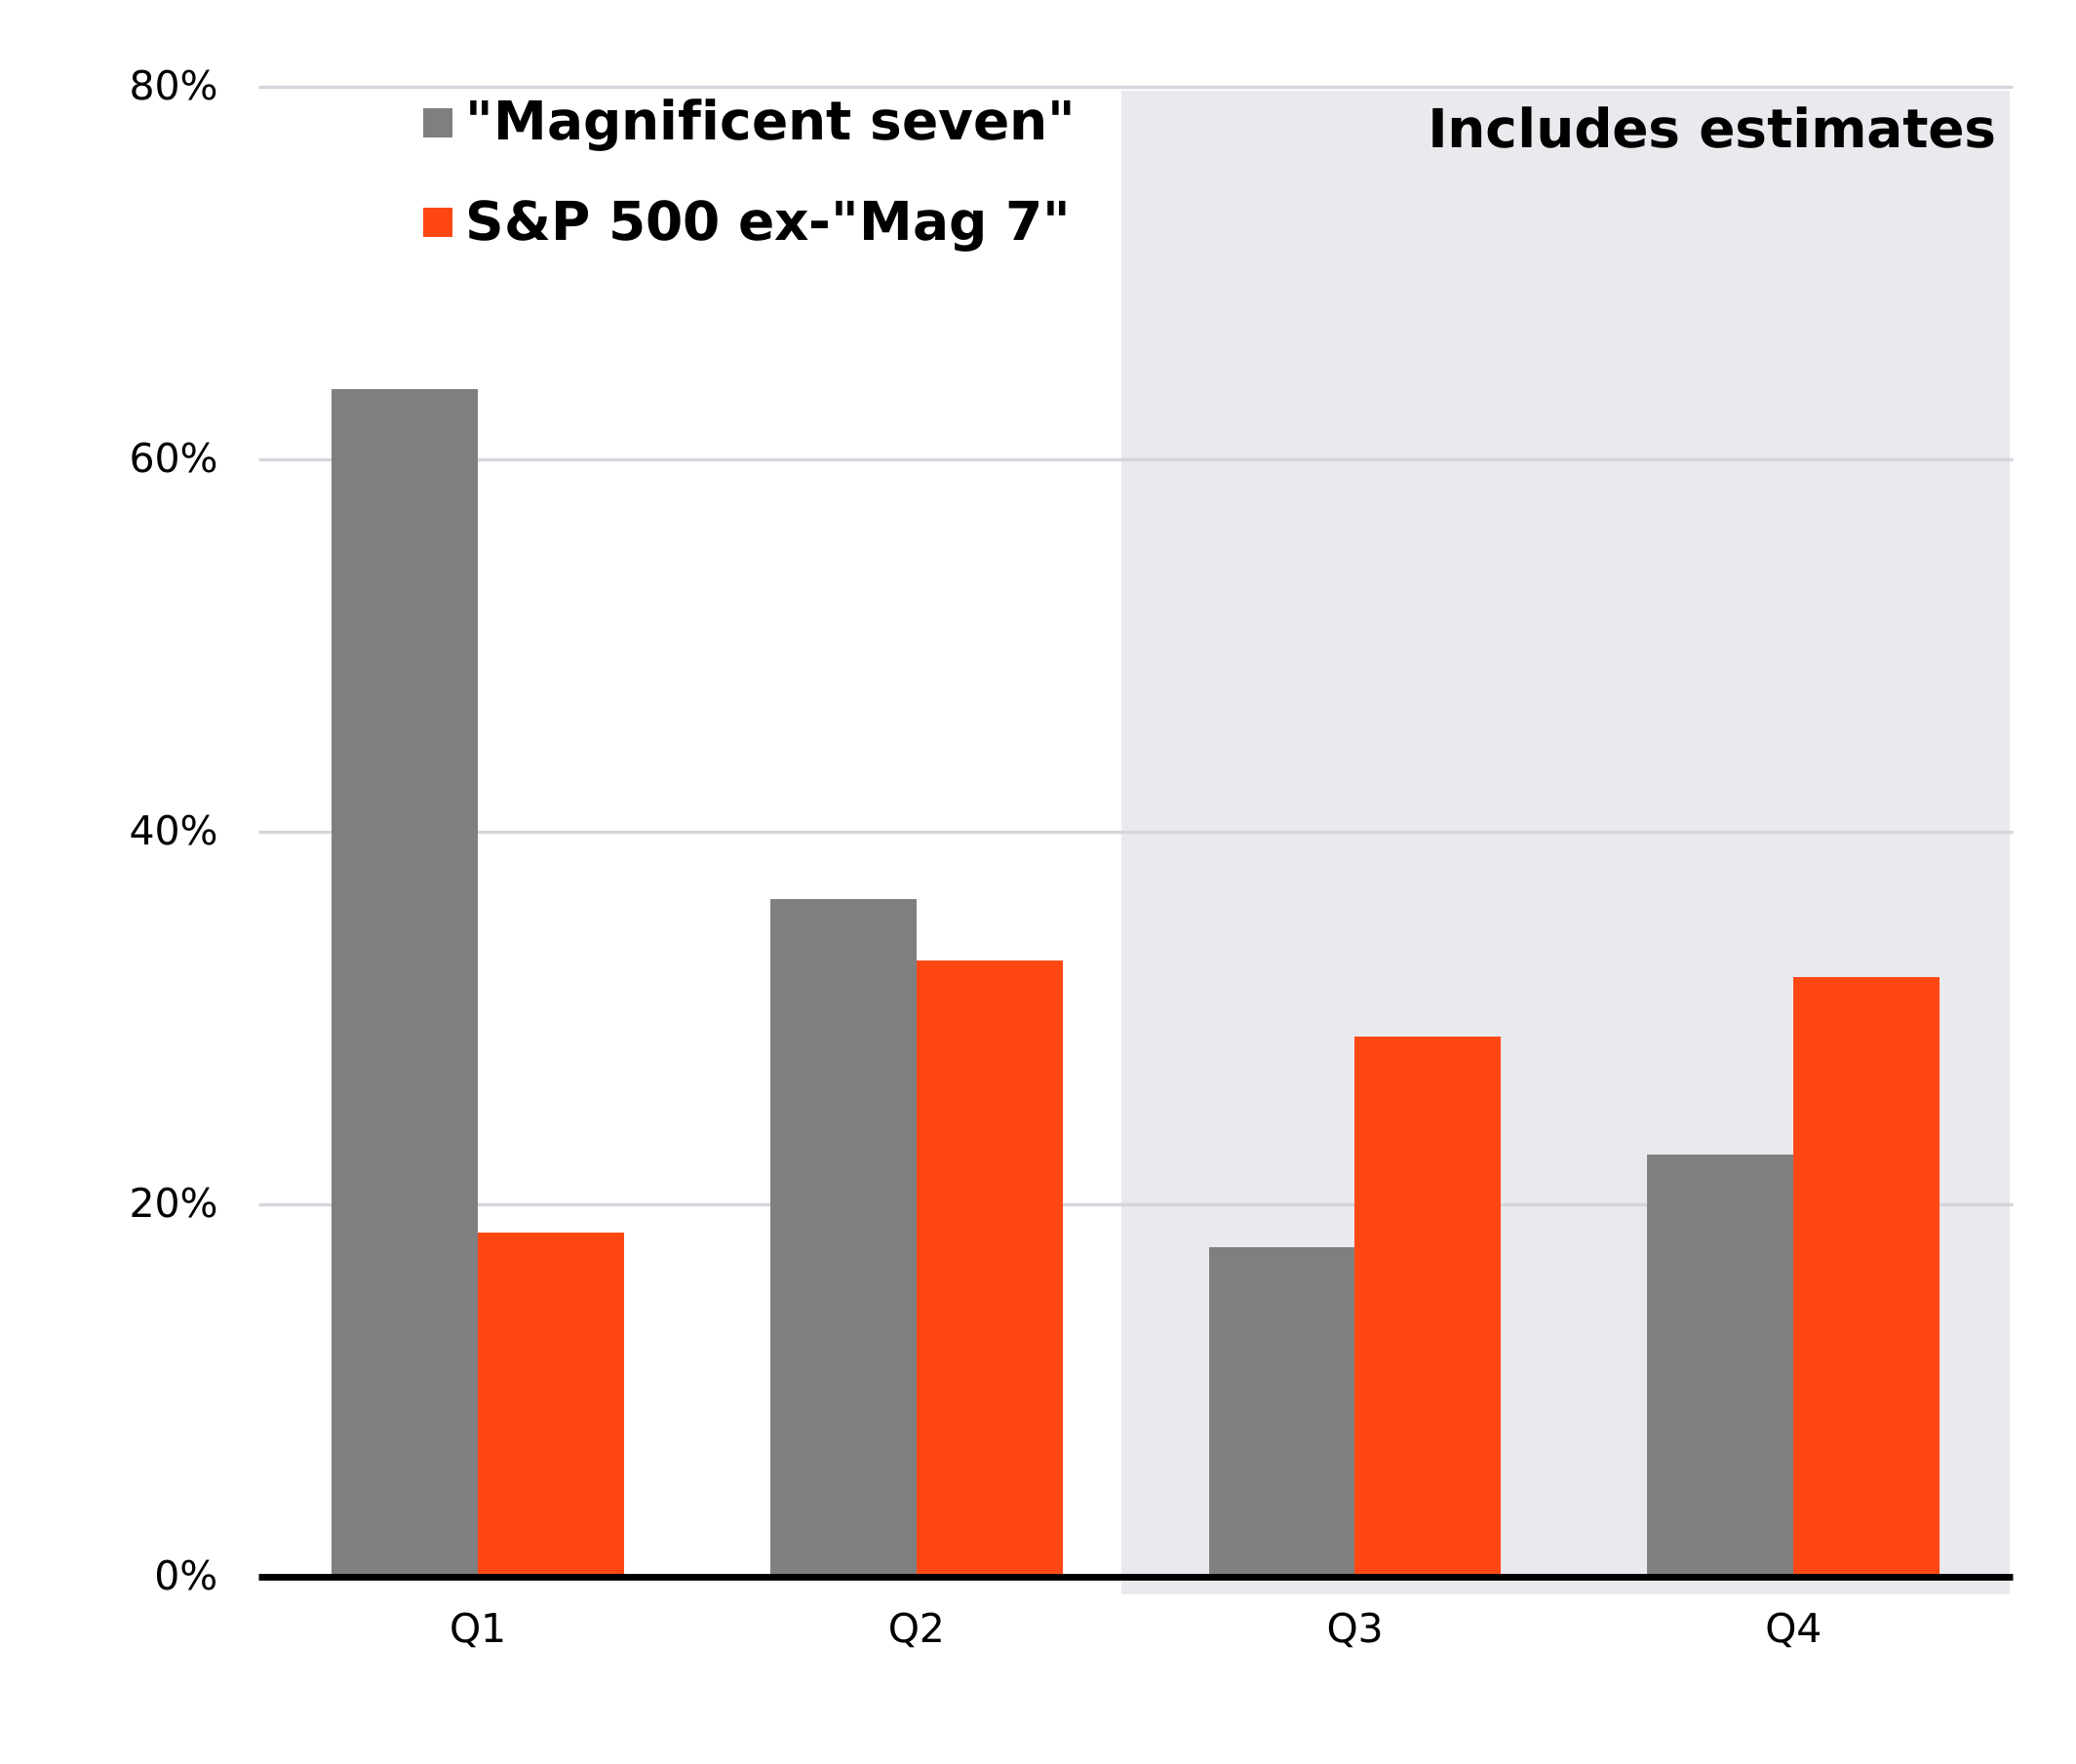
Year-over-year earnings growth for S&P 500 companies, 2026
Past performance is not a reliable indicator of future results. Forward-looking estimates may not come to pass. Source: BlackRock Investment Institute, with data from Bloomberg, October 2026. Note: The bars show year-over-year earnings per share growth for the “magnificent seven” stocks (Alphabet, Amazon, Apple, Meta, Microsoft, Nvidia and Tesla) and the rest of S&P 500. Figures for Q3 and Q4 include estimates.
We will learn much more about the AI theme this earnings season, especially how impactful the technology will ultimately be. But the backdrop for mega-cap tech stocks is starkly different from just four months ago. After narrowing considerably earlier this year, the earnings growth gap has now flipped for the first time since 2022, with the S&P 493 outpacing the “magnificent seven” at roughly 29% versus 18%. See the chart. The bar remains high. Consensus expects S&P 500 earnings to grow about 30% – marking a third consecutive quarter of growth above 20% – according to LSEG data. Meanwhile, scrutiny of the AI theme has grown. That shifting backdrop contributed to our decision to downgrade U.S. equities to neutral last month. Our conviction in AI fundamentals, however, remains intact.
Last week’s earnings highlighted a growing tension between strong demand for AI-linked goods and services and the rising cost of meeting it. Hyperscaler capital spending has surged to about $649 billion over the past year, from about $357 billion in the prior-year period, according to data from Bloomberg, leaving little cash surplus after capex. And while hyperscalers’ operating margins have edged up to 27.1% from 26.9% in the previous four quarters, incremental margins have fallen to 27.9% from 40.4% over that same period. In other words, each additional dollar of revenue is generating less additional profit, raising questions about whether returns can keep pace with soaring investment. Still, our analysis finds that companies with higher AI adoption outside the S&P 500 technology and communication sectors are on track for 3% higher earnings growth this quarter than lower adopters, based on evidence of AI use in regulatory filings. Cloud revenue growth at Microsoft and Alphabet also points to sustained momentum in AI demand. But whether that demand will be enough to justify the scale of investment is still an open question, one we plan to debate at our 2027 internal Outlook Forum this week.
Funding capacity in focus
As the AI buildout becomes increasingly debt-financed, leverage and differences in funding capacity are coming into sharper focus. Credit markets are becoming an important signpost of how much additional AI investment can be financed and at what cost. The Treasury rally alongside the tech sell-off this week also fits our view that the ebb and flow of AI investment expectations will drive competition for capital and bond yields around structurally higher levels.
Within equities, we’re selective with our AI exposures. We favor companies and listed infrastructure poised to benefit from the critical bottlenecks in the AI buildout, a key reason for our move back to overweight EM equities in September. We see that opportunity playing out in Asia. Recent results from chipmakers point to tight supply and strong AI demand. But staying nimble is crucial, as our EM positioning shows: we upgraded at the start of the year, took profits midyear and returned to overweight in September. Brazil’s post-election selloff bears watching, but it does not change our EM overweight.
Our bottom line
AI faces a tougher near-term test as investor scrutiny intensifies. But our conviction in AI fundamentals remains intact, keeping us selective on where we take AI exposure while favoring opportunities tied to scarcity in the buildout.
Market backdrop
The Nasdaq Composite capped its worst month since March 2025 as concerns over returns on massive AI spending intensified. The key question now is the economic value of the AI buildout: what returns it generates and who captures them. We see a range of possible outcomes for growth, profitability and returns on this investment. U.S. Treasuries extended their rally last week, with 10-year yields falling nearly 6 basis points to 4.93% after the Fed kept rates unchanged, as expected.
We focus on October nonfarm payrolls for signs of a tightening labor market and what that could mean for inflation. We’d expect stronger wage pressures than in recent jobs reports, potentially adding to core services inflation, making the October jobs data key to assessing our view of price pressures.
Week ahead
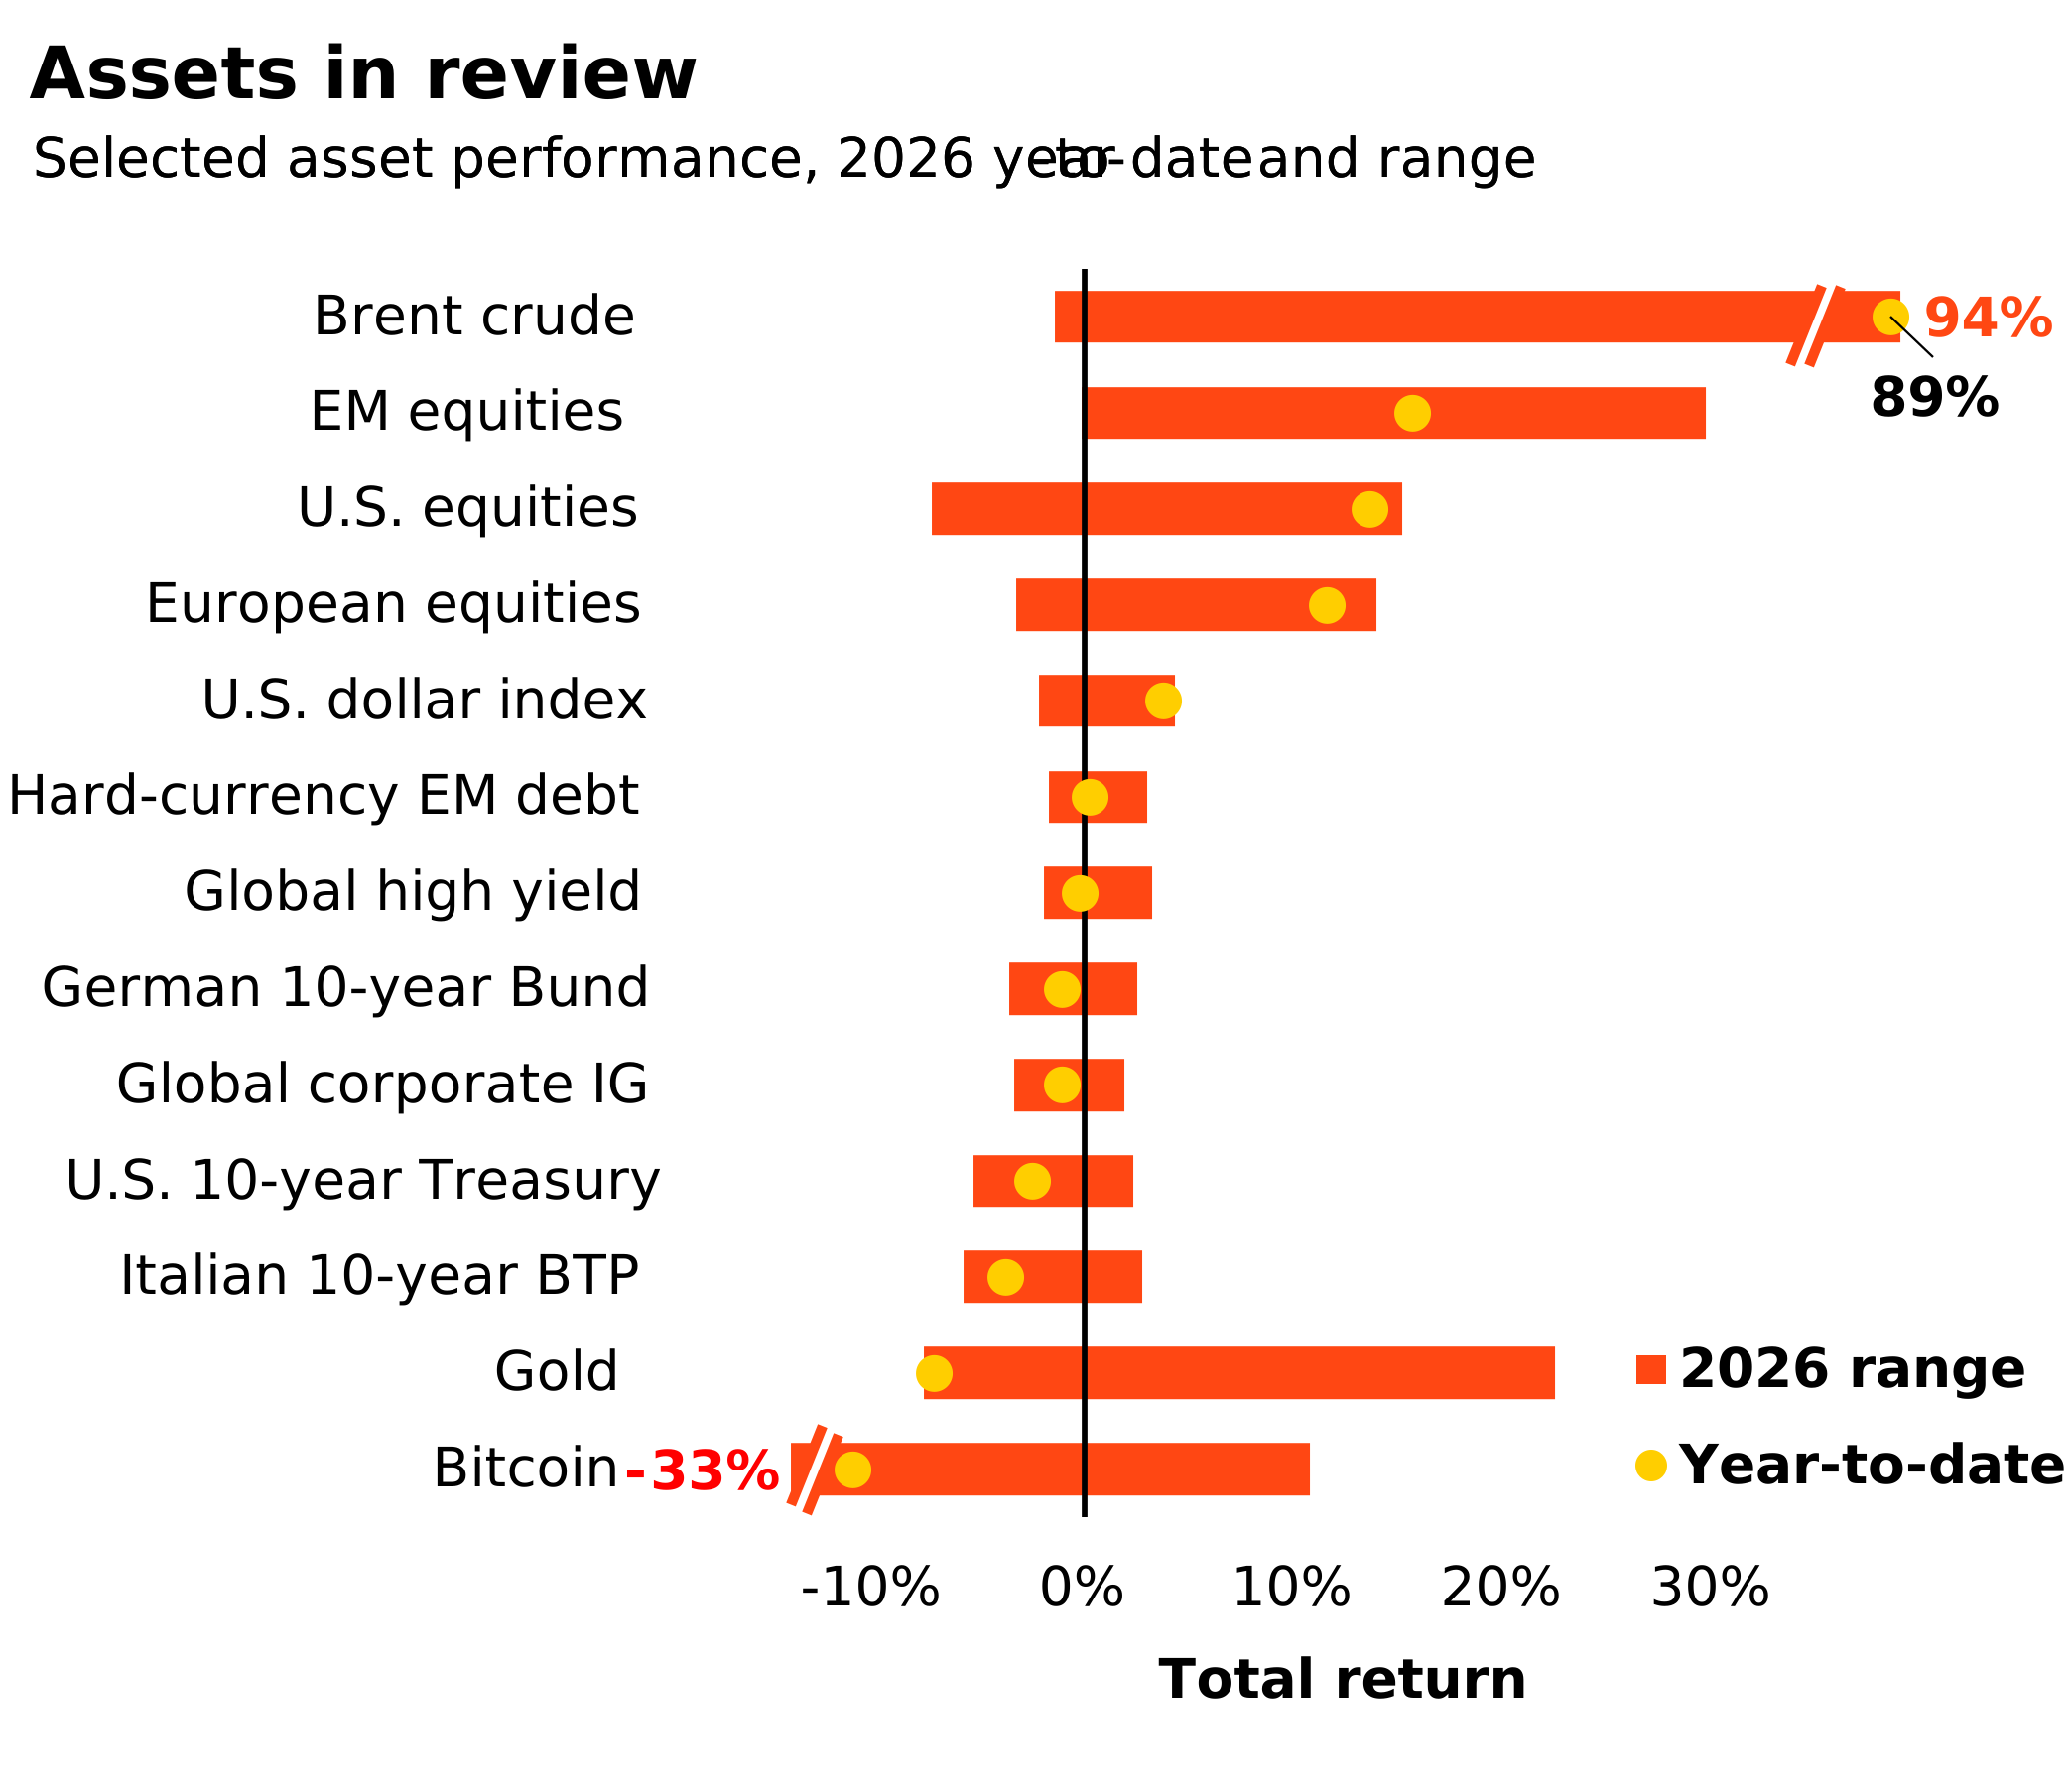
Past performance is not a reliable indicator of current or future results. Indexes are unmanaged and do not account for fees. It is not possible to invest directly in an index. Sources: BlackRock Investment Institute, with data from LSEG Datastream as of October 29, 2026. Notes: The two ends of the bars show the lowest and highest returns at any point year to date, and the dots represent current year-to-date returns. Emerging market (EM), high yield and global corporate investment grade (IG) returns are denominated in U.S. dollars, and the rest in local currencies. Indexes or prices used are: spot Brent crude, ICE U.S. Dollar Index (DXY), spot gold, spot bitcoin, MSCI Emerging Markets Index, MSCI Europe Index, LSEG Datastream 10-year benchmark government bond index (U.S., Germany and Italy), Bloomberg Global High Yield Index, J.P. Morgan EMBI Index, Bloomberg Global Corporate Index and MSCI USA Index.
Global manufacturing PMI final
U.S. international trade balance
Bank of England interest rate decision
U.S. Oct. jobs report; Umich consumer sentiment
Read our past weekly market commentaries here.
Intersecting mega forces
Since we launched our mega forces framework it has become clearer how their intersection shapes almost all our investment views and opens up alpha opportunities. They cut across asset class labels, spurring a rethink of portfolio construction. Investors need to be deliberate about the economic or thematic exposures they own, the vehicles they use to implement them and their investment horizons.

From drivers to portfolio expressions
Our highest conviction views, November 2026
| Driver | What we think | Portfolio expression |
|---|---|---|
| Growth and AI scarcity | AI fundamentals are strong, but we eye near-term volatility. | Neutral U.S. equities and overweight EM equities; favor AI- and tech-related opportunities. |
| Duration and diversification | Higher starting yields improve prospective returns and income. | Overweight short-term U.S. Treasuries for solid income and a cushion against higher rates; neutral long-term Treasuries |
| Credit spreads and liquidity | Selectivity is crucial amid tight spreads and uneven fundamentals. | Credit with clear cash flows, lender protections and recovery value; higher-rated high yield. |
| Inflation and scarcity | Scarcity, secure supply and power demand carry inflation risks. | Infrastructure, energy bottlenecks, EM local debt and real-asset-linked exposures. |
| Alpha opportunity | Macro outcomes matter again in the new regime. | Macro hedge funds, venture capital, market-neutral strategies, and selected private credit and non-U.S. alpha. |
Note: Views are from a U.S. dollar perspective, November 2026. This material represents an assessment of the market environment at a specific time and is not intended to be a forecast of future events or a guarantee of future results. This information should not be relied upon by the reader as research or investment advice regarding any particular funds, strategy or security.
Asset class implications
Six- to 12-month tactical positioning, November 2026
This shows the implementation of our key investment views from the previous page through an asset class lens.

| Asset | Tactical view | Commentary | ||||
|---|---|---|---|---|---|---|
| Equities | ||||||
| United States | We are neutral. Strong AI fundamentals remain supportive, but policy uncertainty could fuel near-term volatility. We continue to favor AI and tech. | |||||
| Europe | We are neutral. We would need to see more business-friendly policy and deeper capital markets for Europe to outperform. We favor financials, infrastructure, and industrials. | |||||
| UK | We are neutral. Valuations remain attractive relative to the U.S., but we see few near-term catalysts to trigger a shift. | |||||
| Japan | We are neutral. Strong corporate balance sheets and governance reforms remain supportive. We prefer targeted exposures to physical AI and the buildout’s bottlenecks. | |||||
| Emerging markets (EM) | We are overweight. Strong earnings and cheaper valuations create opportunities. We particularly like different expressions of the AI scarcity theme across Asia and Latin America. | |||||
| China | We are neutral. We see opportunities in physical AI. Cheap, open-source AI could drive adoption, but that doesn’t necessarily translate into AI-provider profitability. | |||||
| Fixed income | ||||||
| Short U.S. Treasuries | We are overweight. Much of the repricing we anticipated has occurred, and expectations for further Fed hikes look excessive. We favor the front end for attractive income and a greater breakeven buffer. | |||||
| Long U.S. Treasuries | We are neutral. Higher yields offer attractive income and a bigger cushion against further rate increases. We still see room for yields to rise as competition for capital intensifies. | |||||
| Global inflation-linked bonds | We are neutral. We see inflation settling above pre-pandemic levels, but markets may not price this in the near term as economic growth could slow. | |||||
| Euro area government bonds | We are neutral short- and medium-term bonds. Current ECB rate pricing looks fairly valued given the balance of risks. Higher energy prices could push rates higher. We prefer to deploy risk elsewhere. | |||||
| UK gilts | We are neutral. We expect periods of elevated volatility given political uncertainty, longer-term bonds making up a larger market share, and buyers becoming more price-sensitive. | |||||
| Japanese government bonds | We are underweight. The substantial repricing in yields has improved the risk-reward, but further rate hikes and heavy issuance could push yields higher. | |||||
| China government bonds | We are neutral. China bonds offer stability and diversification but developed market yields are higher. A shift in investor sentiment toward equities limits upside. | |||||
| U.S. agency MBS | We are neutral and lean into the stable income MBS provide despite tight spreads. | |||||
| Short-term IG credit | We are neutral. Spreads are tight due to corporate strength; they could widen if issuance increases or risk appetite shifts. | |||||
| Long-term IG credit | We are underweight. We prefer short-term bonds less exposed to interest rate risk over long-term bonds. But attractive overall yields help offset the risk of increased issuance. | |||||
| Global high yield | We are neutral. High yield offers attractive income. We prefer higher-rated U.S. and European high yield over investment grade and see dispersion of returns increasing. | |||||
| Asia credit | We are neutral. Overall yields are attractive and fundamentals are solid, but spreads are tight. | |||||
| Emerging hard currency | We are neutral. Fundamentals have improved, but we see a more attractive risk-reward profile in EM local debt. | |||||
| Emerging local currency | We are overweight. We like the yield relative to its volatility and improving fundamentals. | |||||
Past performance is not a reliable indicator of current or future results. It is not possible to invest directly in an index. Note: Views are from a U.S. dollar perspective. This material represents an assessment of the market environment at a specific time and is not intended to be a forecast or guarantee of future results. This information should not be relied upon as investment advice regarding any particular fund, strategy or security.
Euro-denominated tactical granular views
Six to 12-month tactical views on selected assets vs. broad global asset classes by level of conviction, November 2026

We have lengthened our tactical investment horizon back to six to 12 months. The table below reflects this and, importantly, leaves aside the opportunity for alpha, or the potential to generate above-benchmark returns – especially at a time of heightened volatility.
| Asset | Tactical view | Commentary | ||
|---|---|---|---|---|
| Equities | ||||
| Europe ex UK | We are neutral. We would need to see more business-friendly policy and deeper capital markets for Europe to outperform and to justify a broad overweight. We stay selective, favoring financials, infrastructure, industrials, materials and healthcare. | |||
| Germany | We are neutral. Higher spending on defense and infrastructure support the corporate sector. Valuations are not stretched but neither compelling and expected earnings growth lags other countries. Light positioning means potential easing in geopolitical tensions and AI lifting industrials-driven earnings could create opportunities. | |||
| France | We are neutral. Strong expected earnings growth and global revenue exposure support French corporates. Valuations are less compelling, albeit not stretched versus euro area peers. Persistent political uncertainty leaves the overall risk reward balanced. | |||
| Italy | We are neutral. Earnings growth and momentum are strong, boosted by the significant exposure to financials, utilities and energy. Valuations are still at discount vs. peers, but not as much as in previous years. Political risk is currently low but likely to pick up ahead of 2027 elections. | |||
| Spain | We are overweight. Valuations remain attractive vs. peers even if relative earnings momentum has slowed. Strong domestic demand growth and exposure to fast-growing areas like Latin America support Spanish stocks. Financials, utilities and infrastructure-linked stocks would benefit from Europe’s push towards autonomy. | |||
| Netherlands | We are neutral. Earnings revisions in the IT sector, a large sector in the Dutch stock market is offset by other sectors seeing less favorable valuations and a weaker earnings outlook than European peers. | |||
| Switzerland | We are neutral. Valuations have improved, from stretched levels, but the earnings outlook is weaker than other European markets. If global risk appetite stays strong, the index’s tilt to stable, less volatile sectors may weigh on performance . | |||
| UK | We are neutral. Valuations remain attractive relative to the U.S., but we see few near-term catalysts to trigger a shift. | |||
| Fixed income | ||||
| Euro area government bonds | We are neutral short- and medium-term bonds. Current ECB rate pricing looks fairly valued given the balance of risks. Higher energy prices could push rates higher. We prefer to deploy risk elsewhere. | |||
| German bunds | We are neutral Bunds. Current ECB rate pricing looks more fairly valued given the balance of risks. Fiscal stimulus and increased bond issuance exert upward pressure on yields, alongside inflation risks amid lingering geopolitical tensions. | |||
| French OATs | We are neutral. Elevated political uncertainty, high budget deficits and slow structural reforms could stoke volatility, but these risks already seem priced into OATs and we don’t expect a material worsening from here. | |||
| Italian BTPs | We are neutral. The spread over German bunds looks tight given Italy’s large budget deficits and growing public debt. Domestic factors remain supportive, with growth holding up relative to the rest of the euro area and local demand for BTPs solid at current yield levels. Domestic disapproval would likely prevent defense spending from reaching fiscally unstable levels. Political uncertainty is likely to increase ahead of next year’s elections. | |||
| UK gilts | We are neutral. We expect periods of elevated volatility given political uncertainty, longer-term bonds making up a larger market share, and buyers becoming more price-sensitive. | |||
| Swiss government bonds | We are neutral. The SNB seems comfortable with its medium-term inflation outlook and its current policy stance. Market pricing is broadly in line with SNB messaging. | |||
| European inflation-protected securities | We are neutral. We see higher medium-term inflation, but inflation expectations are firmly anchored. Cooling inflation and uncertain growth may matter more near term. | |||
| European investment grade | European investment grade is supported by healthy corporate sector balance sheets, contained default rates and the persistently strong demand for durable income from European households. We prefer European investment grade over the U.S. | |||
| European high yield | We are overweight. While spreads are low, the income potential remains attractive. Defaults are contained and high yield is of higher quality and less sensitive to interest rate swings compared with the U.S. | |||
Past performance is not a reliable indicator of current or future results. It is not possible to invest directly in an index. Note: Views are from a euro perspective, November 2026. This material represents an assessment of the market environment at a specific time and is not intended to be a forecast or guarantee of future results. This information should not be relied upon as investment advice regarding any particular fund, strategy or security.
On the go?