Upgrading US Treasuries to lock in income
Market take
Weekly video_20261012
Wei Li
Global Chief Investment Strategist
BlackRock
SCRIPT
Camera frame
Title slide: Upgrading US Treasuries to lock in income
This week we are making some tactical view changes, in particular changing our views on US Treasuries and US equities.
1: Locking in US Treasury income
Starting with US Treasuries, we first went underweight US long-duration Treasuries back in October 2020, when the US 10-year [yield] was still below 0.9%.
Since then, we have had brief periods of neutral but stayed mostly underweight.
The US 10-year [yield] is now at five and a quarter [5.25%], and we are upgrading to neutral to lock in income.
We’re refraining from making a bigger bullish call on the long end of the US Treasuries market and instead are upgrading front-end Treasuries into overweight, given the greater income buffer for further yield increases.
2: Downgrading US equities
On US equities, we are bringing overweight to neutral, partly funding the Treasuries upgrade.
We still prefer AI and tech within the neutral stance.
This is a short-term risk management move, really reflecting the fact that we believe investors need to be more dynamic in this new market and macro regime.
3: A more dynamic approach
Our conviction in the fundamentals remains intact, and we stand ready to add risk on potentially more attractive venture points.
Other adjustments include trimming our Japanese government bond underweight, after Japanese 10-year [yields] rose from [around] 0.4% when we first initiated the position in mid-2023 to now around 3%.
Outro: Here’s our Market take
The big picture is that the new investment regime requires a very dynamic approach.
We are managing risk, not changing our core convictions.
And we’re also monitoring growing population focus on AI policy and AI buildout.
Closing frame: Read details: blackrock.com/weekly-commentary
Income in focus
We upgrade US Treasuries, preferring short-term bonds, as higher yields improve potential returns, partly funded by downgrading US equities to neutral.
Market backdrop
Global bonds swung sharply last week, with 10- and 30-year US Treasury yields hitting 24-year highs before retreating after strong bond auctions.
Week ahead
US CPI and PPI offer the first look at September inflation this week. We watch for signs that could shift Fed expectations and Treasury yields.
Higher yields and potentially excessive Fed tightening expectations create room to unwind our US Treasury underweight – a mainstay for most of the last six years. We upgrade Treasuries, favoring short-term bonds. In turn, we take profits: downgrading US equities to neutral to manage potential volatility around the AI buildout and trimming our Japanese government bond (JGB) underweight. We retain our conviction in AI fundamentals and preference for AI within US equities.
Paragraph-2,Image-1,Paragraph-3
Paragraph-4,Advance Static Table-1,Paragraph-5,Advance Static Table-2,Paragraph-6,Advance Static Table-3
Anatomy of a 5% yield
10-year US Treasury yield decomposition, 2005–26
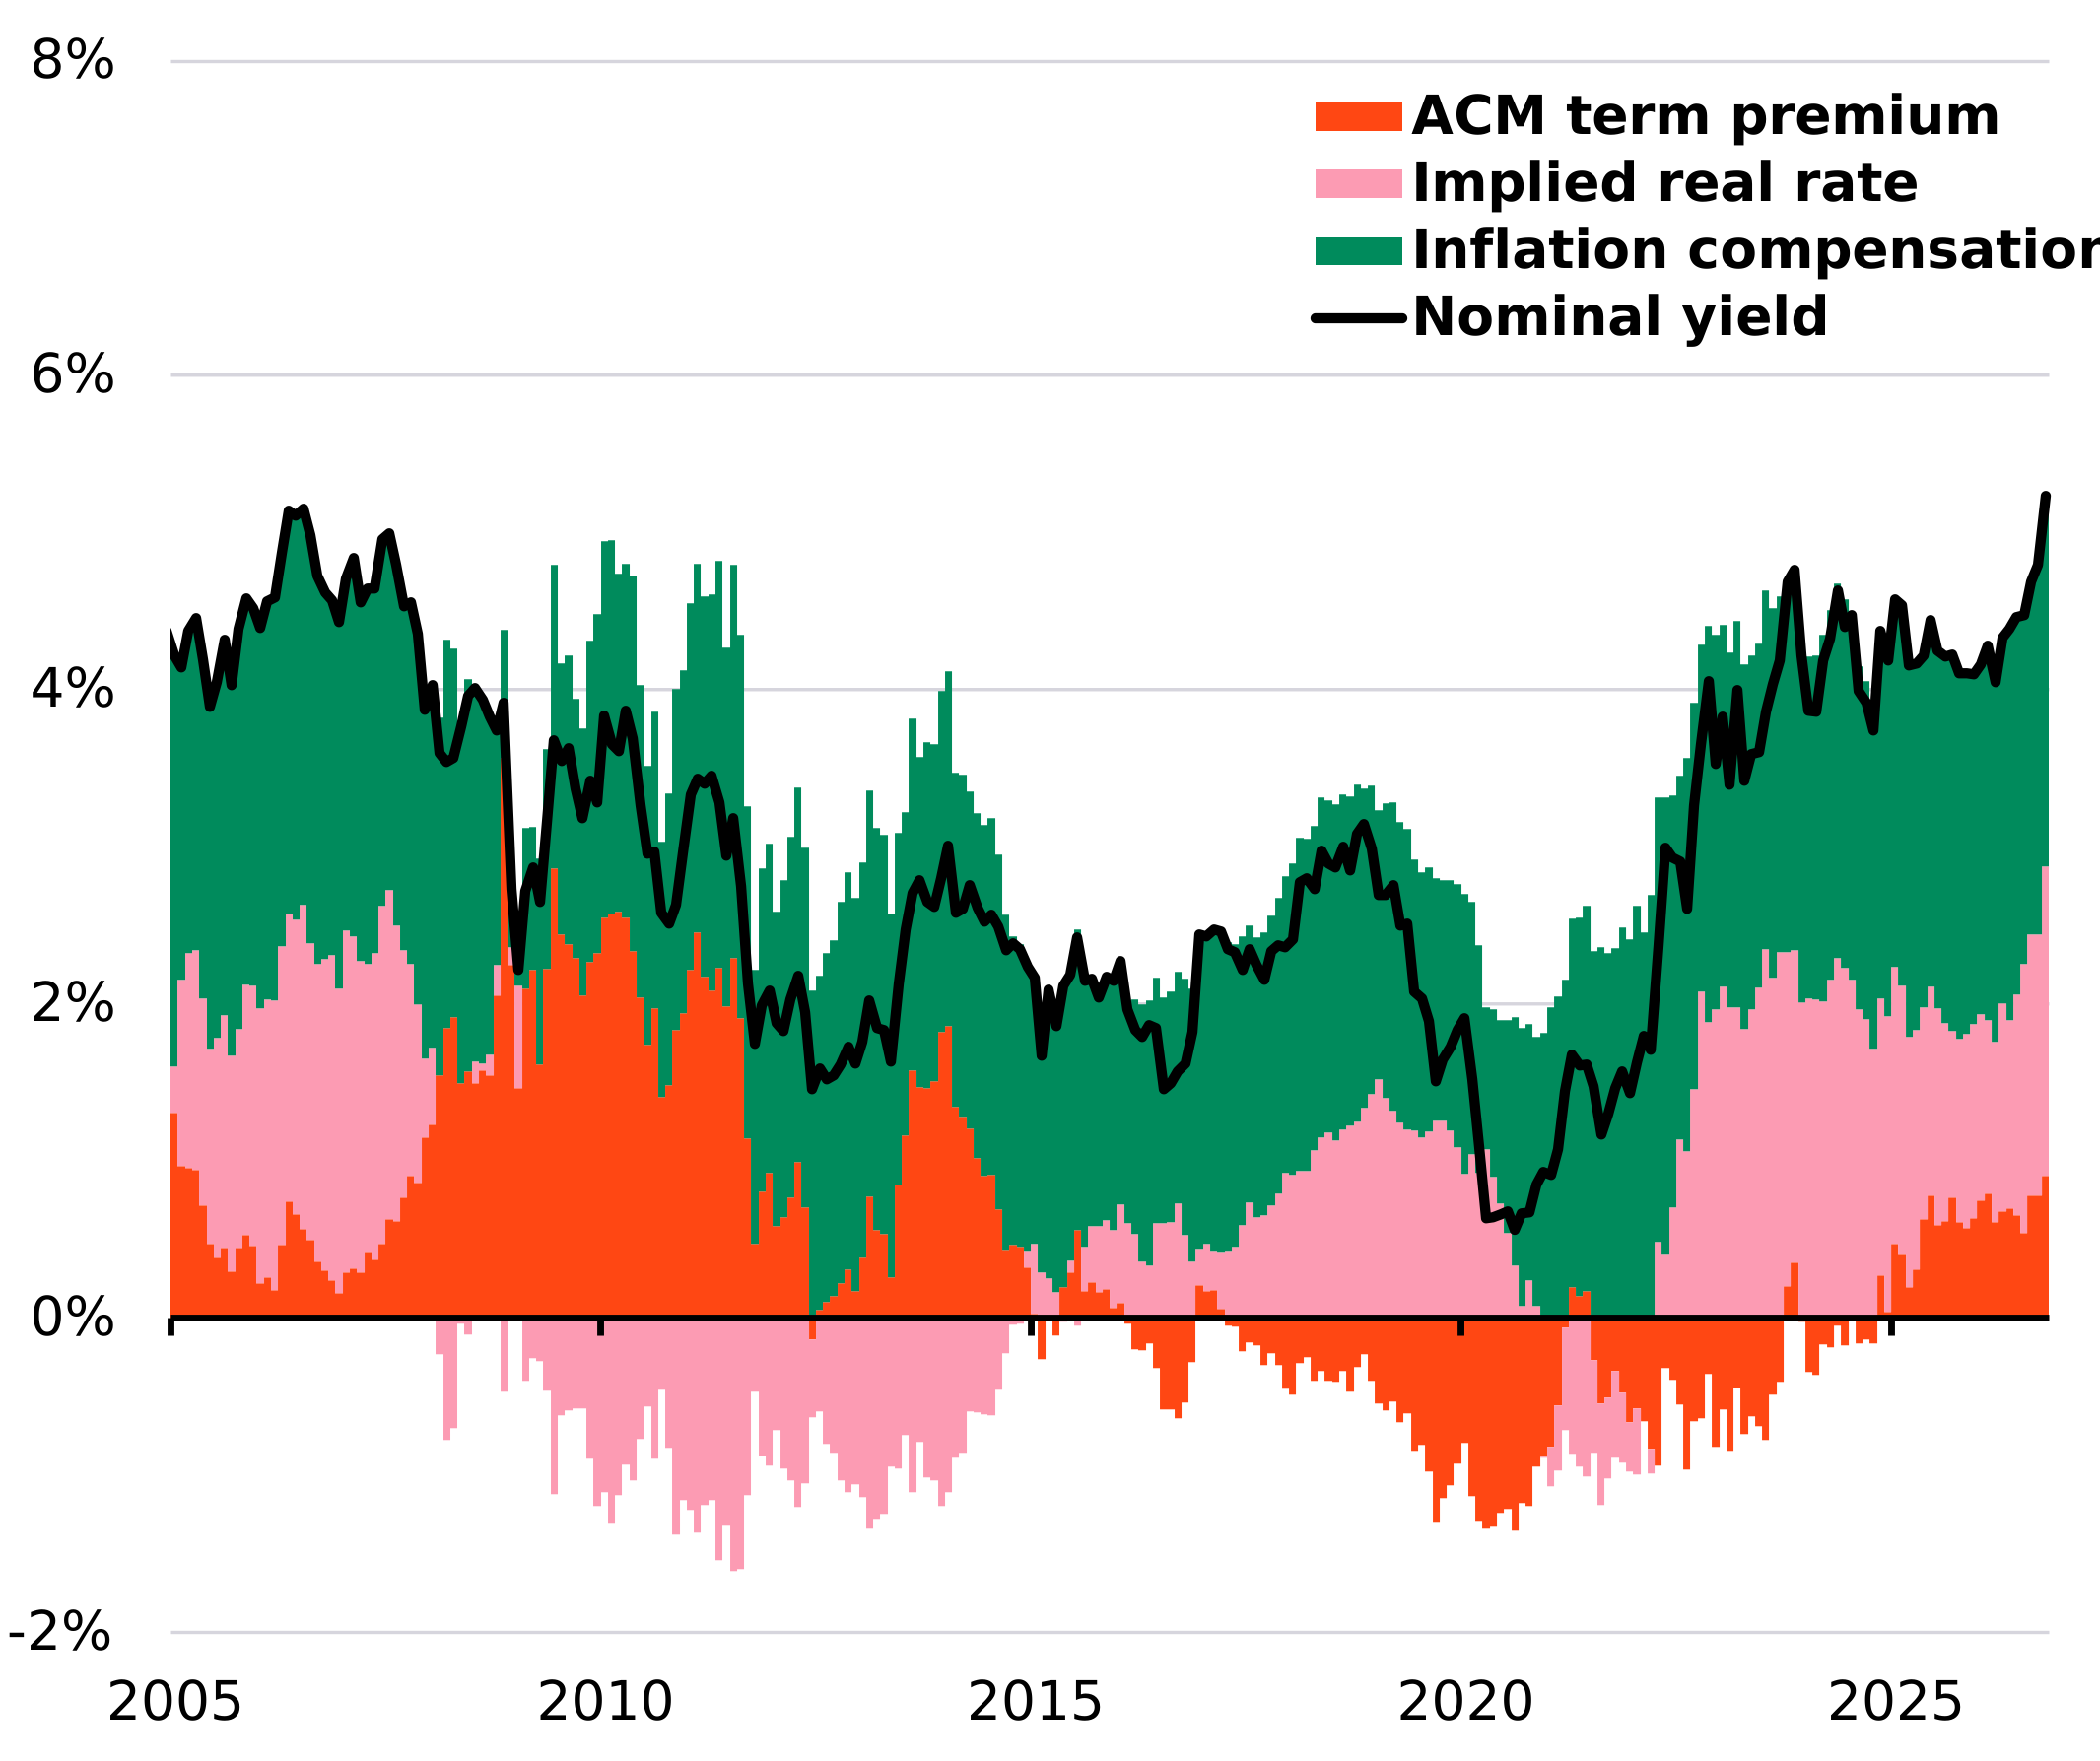
The figure shown relates to past performance. Past performance is not a reliable indicator of current or future results. The ACM term premium is a model-based estimate subject to uncertainty. Source: BlackRock Investment Institute, with data from LSEG Datastream and the Federal Reserve Bank of New York, October 2026. Notes: Inflation compensation is based on 10-year breakeven inflation. The implied real rate is calculated as the nominal yield less inflation compensation and the ACM term premium. The decomposition is illustrative, not a model-based estimate.
The 10-year Treasury yield has risen 110 basis points this year to around 5.25%, driven mainly by higher real interest rates rather than inflation expectations or term premium. Two forces are behind the rise in real rates: intensifying competition for capital is pushing up the neutral rate while Middle East tensions and higher oil prices have driven a sharp reversal in Fed rate expectations. Since January, markets have priced in 160 additional basis points of Fed tightening over the next 12 months. We think that is overdone. With term premium averaging around 75 basis points since September, higher yields offer a more attractive entry point. At current yields, our analysis suggests a 75-basis-point cushion against further yield increases over 12 months before total returns turn negative. That supports adding US Treasuries, especially at the short end, where we see the greatest scope for Fed tightening expectations to unwind.
We are adding Treasuries from across the curve. For most of the last six years, we’ve been underweight Treasuries, turning neutral in spots. Now, yields have reset toward our long-held higher-rates view, and we want to lock in some attractive income. Ten-year Treasury yields sat near 0.9% back in October 2020 when we first went underweight and have since surged to 24-year highs above 5.3%. We are upgrading shorter-term Treasuries to overweight, where we see scope for excessive Fed tightening expectations to unwind, and long-term Treasuries to neutral as higher yields now provide better compensation for interest-rate risk. We also trim our underweight in JGBs, held since July 2023 when 10-year yields were at 0.4%-0.5%, compared with above 3% now. We fund the Treasury upgrades partly from US agency mortgage-backed securities that have been a stable source of income in portfolios and we are now neutral.
Downgrading US equities
We also fund the Treasury upgrades by closing our long-held US equity overweight to neutral. This is a short-term risk-management move, reflecting our belief that investors must be more dynamic in today’s volatile macro and market regime. We are also monitoring growing population focus on AI policy and the AI buildout in jurisdictions across the country.
Our fundamental convictions on AI transformation remain intact. Higher rates are increasingly differentiating companies by their ability to generate earnings and returns above the cost of capital. We still favor AI-related companies and listed infrastructure, where growing demand and scarcity in critical infrastructure support attractive returns. Existing infrastructure could grow even more valuable amid this scarcity. Despite narrative swings, we believe fundamentals will ultimately prevail. We also maintain our emerging market equity overweight. FactSet data shows third-quarter earnings for S&P 500 companies are expected to grow nearly 30% year-on-year.
Our bottom line
We are managing near-term risk, not changing our core convictions. Higher yields offer an opportunity to add Treasuries, funded partly by taking profits on US equities. We remain constructive on AI and stand ready to add risk again as visibility improves and attractive entry points emerge.
Market backdrop
Global government bonds saw another volatile week, with 10- and 30-year US Treasury yields hitting their highest levels since 2002 before retreating after strong bond auctions. European bonds also sold off, led by France amid fiscal concerns. Oil prices rose as Middle East tensions persisted, adding to inflation worries. We see the bond selloff as reinforcing our competition-for-capital thesis, while higher yields improve the case for owning Treasuries.
US CPI and PPI data take center stage this week, offering the first snapshots of September inflation. Fed minutes last week underscored caution about the policy path and the importance of incoming data. We are watching for persistent price pressures amid higher energy costs and recent PCE methodology changes, with the readings likely to shape Fed rate expectations and Treasury yields.
Week ahead
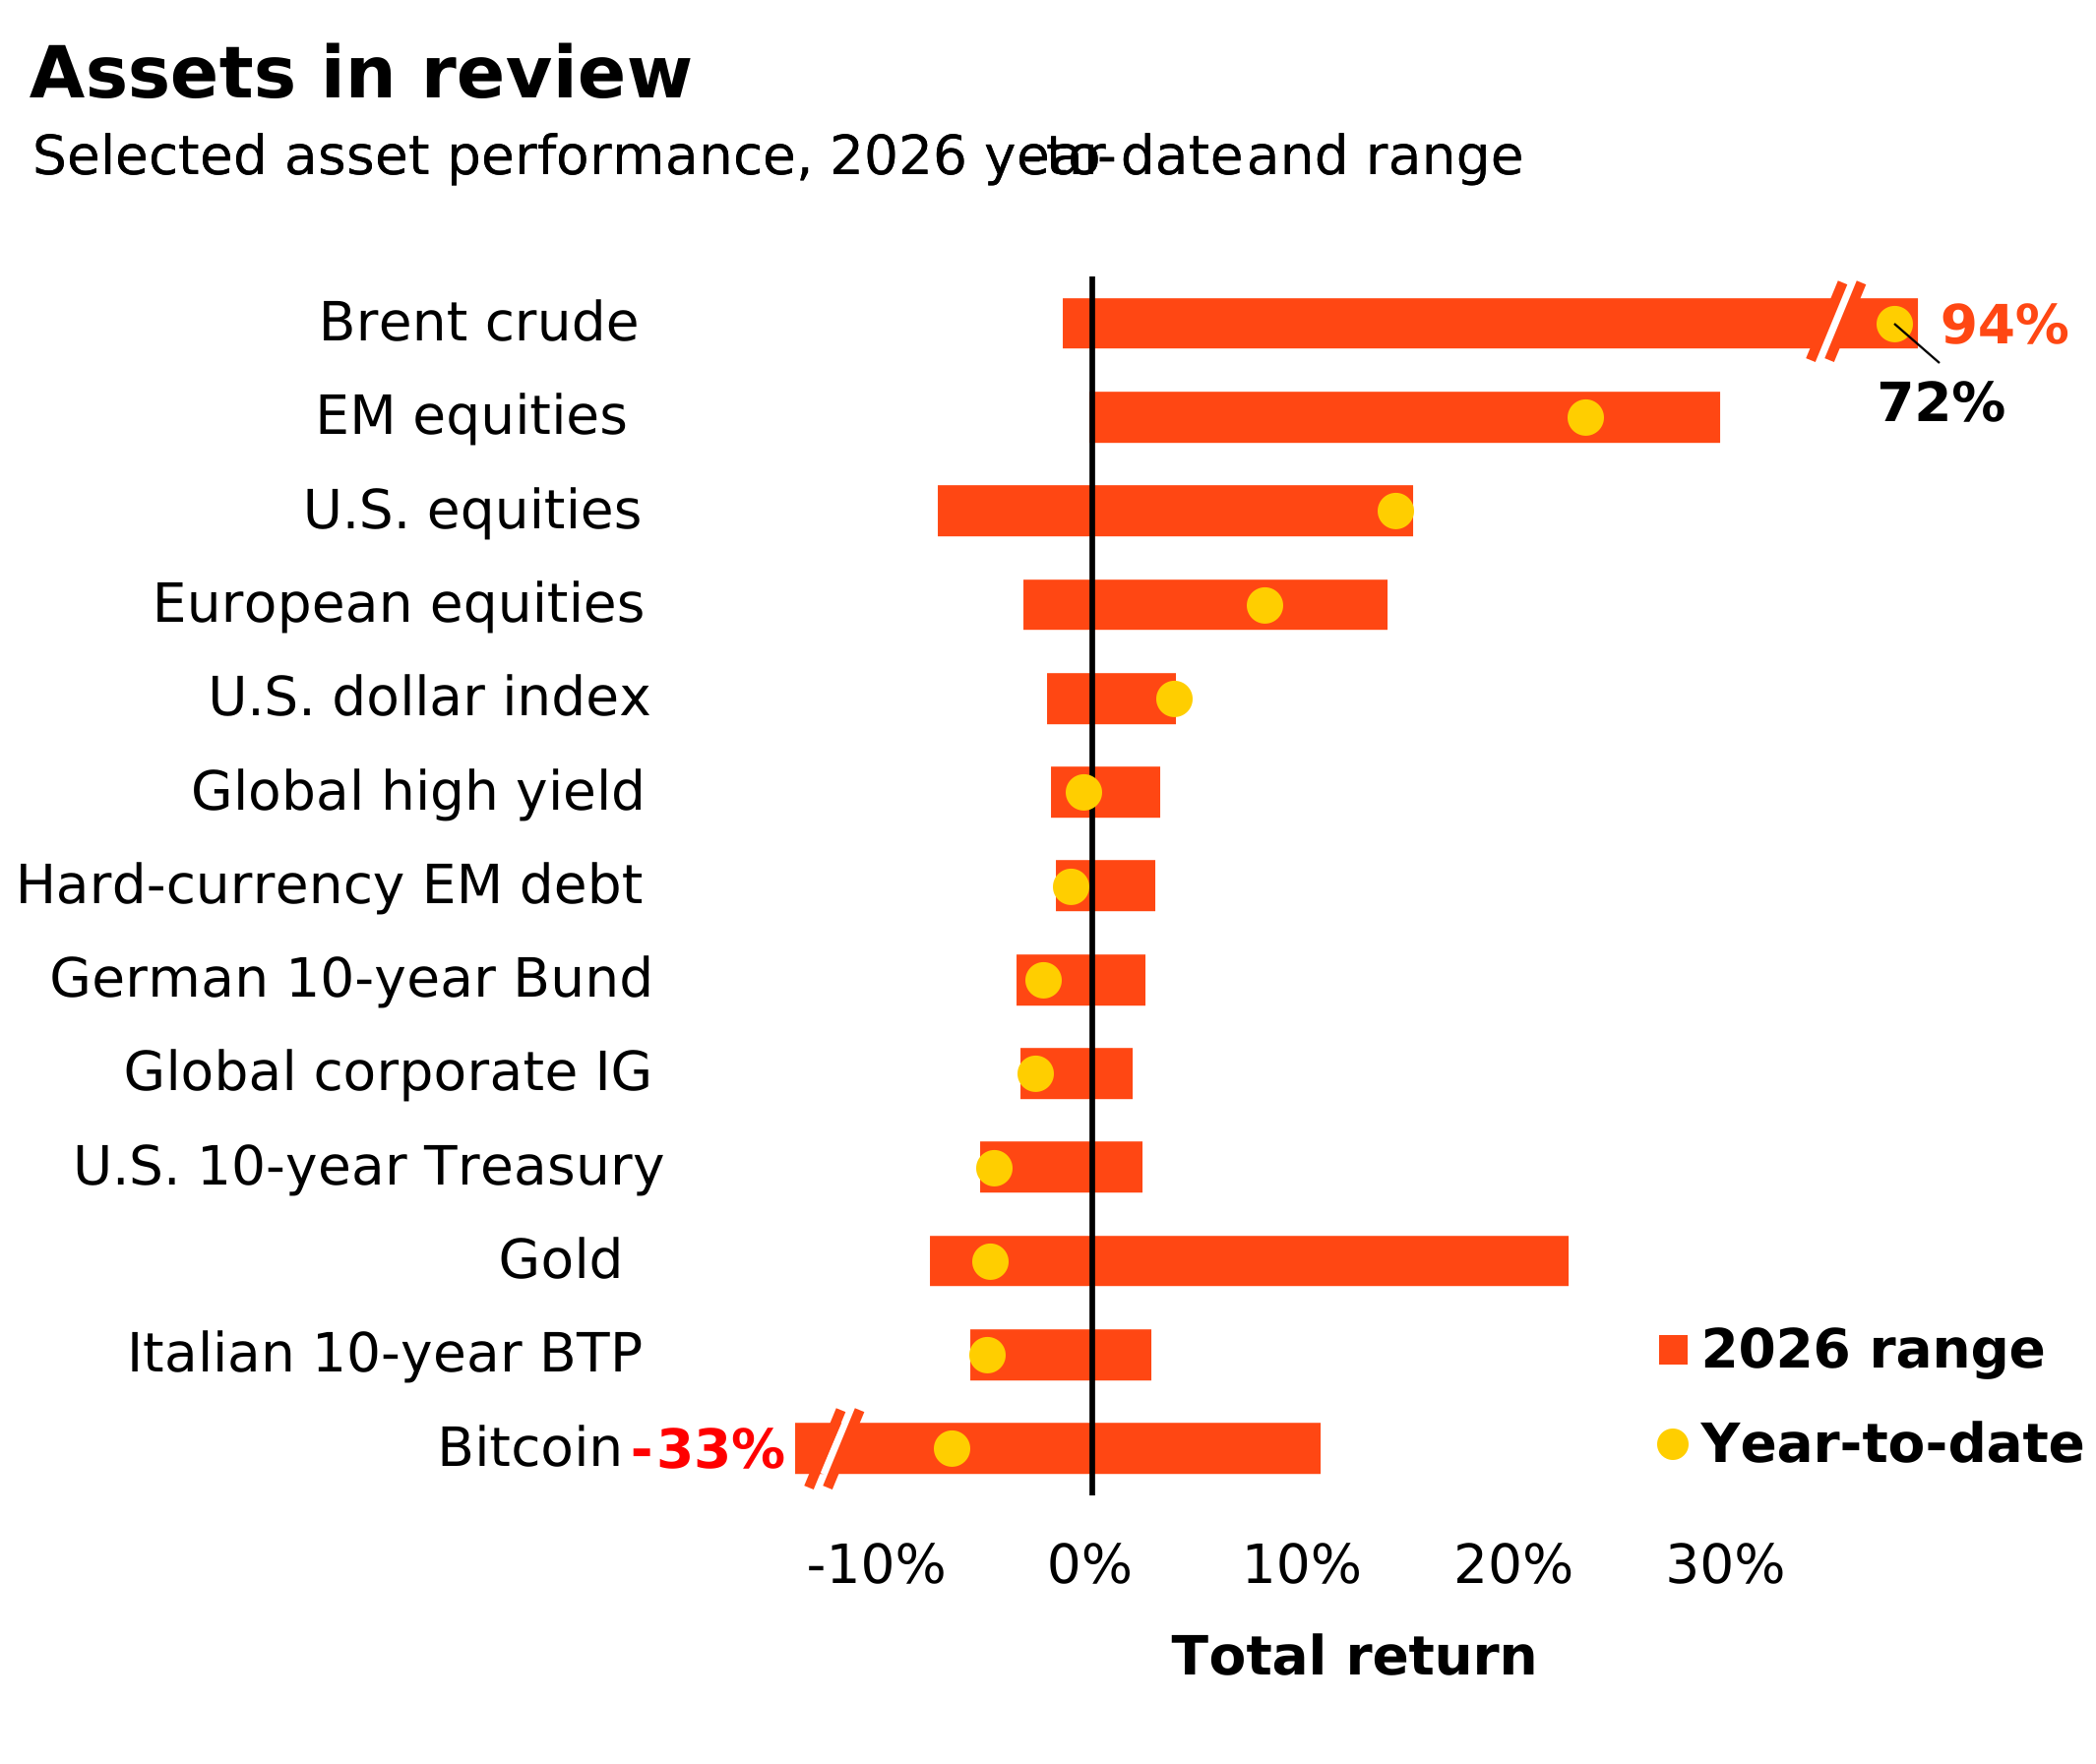
Past performance is not a reliable indicator of current or future results. Indexes are unmanaged and do not account for fees. It is not possible to invest directly in an index. Sources: BlackRock Investment Institute, with data from LSEG Datastream as of October 8, 2026. Notes: The two ends of the bars show the lowest and highest returns at any point year to date, and the dots represent current year-to-date returns. Emerging market (EM), high yield and global corporate investment grade (IG) returns are denominated in US dollars, and the rest in local currencies. Indexes or prices used are: spot Brent crude, ICE US Dollar Index (DXY), spot gold, spot bitcoin, MSCI Emerging Markets Index, MSCI Europe Index, LSEG Datastream 10-year benchmark government bond index (US, Germany and Italy), Bloomberg Global High Yield Index, J.P. Morgan EMBI Index, Bloomberg Global Corporate Index and MSCI USA Index.
Oct. 12
Japan PPI
Oct. 14
US CPI
Oct. 15
US PPI and retail sales, UK GDP estimate
Oct. 16
EU trade balance, US industrial production
Read our past weekly commentaries here.
Intersecting mega forces
Since we launched our mega forces framework it has become clearer how their intersection shapes almost all our investment views and opens up alpha opportunities. They cut across asset class labels, spurring a rethink of portfolio construction. Investors need to be deliberate about the economic or thematic exposures they own, the vehicles they use to implement them and their investment horizons.

From drivers to portfolio expressions
Our highest conviction views, October 2026
| Driver | What we think | Portfolio expression |
|---|---|---|
| Growth and AI scarcity | AI fundamentals are strong, but we eye near-term volatility. | Neutral US equities and overweight EM equities; favor AI- and tech-related opportunities. |
| Duration and diversification | Higher starting yields improve prospective returns and income. | Overweight short-term US Treasuries for solid income and a cushion against higher rates; neutral long-term Treasuries |
| Credit spreads and liquidity | Selectivity is crucial amid tight spreads and uneven fundamentals. | Credit with clear cash flows, lender protections and recovery value; higher-rated high yield. |
| Inflation and scarcity | Scarcity, secure supply and power demand carry inflation risks. | Infrastructure, energy bottlenecks, EM local debt and real-asset-linked exposures. |
| Alpha opportunity | Macro outcomes matter again in the new regime. | Macro hedge funds, venture capital, market-neutral strategies, and selected private credit and non-US alpha. |
Note: Views are from a US dollar perspective, October 2026. This material represents an assessment of the market environment at a specific time and is not intended to be a forecast of future events or a guarantee of future results. This information should not be relied upon by the reader as research or investment advice regarding any particular funds, strategy or security.
Asset class implications
Six- to 12-month tactical positioning, October 2026
This shows the implementation of our key investment views from the previous page through an asset class lens.

| Asset | Tactical view | Commentary | ||||
|---|---|---|---|---|---|---|
| Equities | ||||||
| United States |  |
We are neutral. Strong AI fundamentals remain supportive, but policy uncertainty could fuel near-term volatility. We continue to favor AI and tech. | ||||
| Europe |  |
We are neutral. We would need to see more business-friendly policy and deeper capital markets for Europe to outperform. We favor financials, infrastructure, and industrials. | ||||
| UK | |
We are neutral. Valuations remain attractive relative to the US, but we see few near-term catalysts to trigger a shift. | ||||
| Japan | |
We are neutral. Strong corporate balance sheets and governance reforms remain supportive. We prefer targeted exposures to physical AI and the buildout’s bottlenecks. | ||||
| Emerging markets (EM) |  |
We are overweight. Strong earnings and cheaper valuations create opportunities. We particularly like different expressions of the AI scarcity theme across Asia and Latin America. | ||||
| China | |
We are neutral. We see opportunities in physical AI. Cheap, open-source AI could drive adoption, but that doesn’t necessarily translate into AI-provider profitability. | ||||
| Fixed income | ||||||
| Short US Treasuries | |
We are overweight. Much of the repricing we anticipated has occurred, and expectations for further Fed hikes look excessive. We favor the front end for attractive income and a greater breakeven buffer. | ||||
| Long US Treasuries |  |
We are neutral. Higher yields offer attractive income and a bigger cushion against further rate increases. We still see room for yields to rise as competition for capital intensifies. | ||||
| Global inflation-linked bonds | |
We are neutral. We see inflation settling above pre-pandemic levels, but markets may not price this in the near term as economic growth could slow. | ||||
| Euro area government bonds | |
We are neutral short- and medium-term bonds. Current ECB rate pricing looks fairly valued given the balance of risks. Higher energy prices could push rates higher. We prefer to deploy risk elsewhere. | ||||
| UK Gilts | |
We are neutral. We expect periods of elevated volatility given political uncertainty, longer-term bonds making up a larger market share, and buyers becoming more price-sensitive. | ||||
| Japanese government bonds |  |
We are underweight. The substantial repricing in yields has improved the risk-reward, but further rate hikes and heavy issuance could push yields higher. | ||||
| China government bonds | |
We are neutral. China bonds offer stability and diversification but developed market yields are higher. A shift in investor sentiment toward equities limits upside. | ||||
| US agency MBS | |
We are neutral and lean into the stable income MBS provide despite tight spreads. | ||||
| Short-term IG credit | |
We are neutral. Spreads are tight due to corporate strength; they could widen if issuance increases or risk appetite shifts. | ||||
| Long-term IG credit |  |
We are underweight. We prefer short-term bonds less exposed to interest rate risk over long-term bonds. But attractive overall yields help offset the risk of increased issuance. | ||||
| Global high yield | |
We are neutral. High yield offers attractive income. We prefer higher-rated US and European high yield over investment grade and see dispersion of returns increasing. | ||||
| Asia credit | |
We are neutral. Overall yields are attractive and fundamentals are solid, but spreads are tight. | ||||
| Emerging hard currency | |
We are neutral. Fundamentals have improved, but we see a more attractive risk-reward profile in EM local debt. | ||||
| Emerging local currency | |
We are overweight. We like the yield relative to its volatility and improving fundamentals. | ||||
Past performance is not a reliable indicator of current or future results. It is not possible to invest directly in an index. Note: Views are from a US dollar perspective. This material represents an assessment of the market environment at a specific time and is not intended to be a forecast or guarantee of future results. This information should not be relied upon as investment advice regarding any particular fund, strategy or security.
Euro-denominated tactical granular views
Six to 12-month tactical views on selected assets vs. broad global asset classes by level of conviction, October 2026
We have lengthened our tactical investment horizon back to six to 12 months. The table below reflects this and, importantly, leaves aside the opportunity for alpha, or the potential to generate above-benchmark returns – especially at a time of heightened volatility.
| Asset | Tactical view | Commentary | ||
|---|---|---|---|---|
| Equities | ||||
| Europe ex UK | |
We are neutral. We would need to see more business-friendly policy and deeper capital markets for Europe to outperform and to justify a broad overweight. We stay selective, favoring financials, infrastructure, industrials, materials and healthcare. | ||
| Germany | |
We are neutral. Higher spending on defense and infrastructure support the corporate sector. Valuations are not stretched but neither compelling and expected earnings growth lags other countries. Light positioning means potential easing in geopolitical tensions and AI lifting industrials-driven earnings could create opportunities. | ||
| France | |
We are neutral. Strong expected earnings growth and global revenue exposure support French corporates. Valuations are less compelling, albeit not stretched versus euro area peers. Persistent political uncertainty leaves the overall risk reward balanced. | ||
| Italy | |
We are neutral. Earnings growth and momentum are strong, boosted by the significant exposure to financials, utilities and energy. Valuations are still at discount vs. peers, but not as much as in previous years. Political risk is currently low but likely to pick up ahead of 2027 elections. | ||
| Spain |  |
We are overweight. Valuations remain attractive vs. peers even if relative earnings momentum has slowed. Strong domestic demand growth and exposure to fast-growing areas like Latin America support Spanish stocks. Financials, utilities and infrastructure-linked stocks would benefit from Europe’s push towards autonomy. | ||
| Netherlands | |
We are neutral. Earnings revisions in the IT sector, a large sector in the Dutch stock market is offset by other sectors seeing less favorable valuations and a weaker earnings outlook than European peers. | ||
| Switzerland |  |
We are neutral. Valuations have improved, from stretched levels, but the earnings outlook is weaker than other European markets. If global risk appetite stays strong, the index’s tilt to stable, less volatile sectors may weigh on performance. | ||
| UK | |
We are neutral. Valuations remain attractive relative to the US, but we see few near-term catalysts to trigger a shift. | ||
| Fixed income | ||||
| Euro area government bonds | |
We are neutral short- and medium-term bonds. Current ECB rate pricing looks fairly valued given the balance of risks. Higher energy prices could push rates higher. We prefer to deploy risk elsewhere. | ||
| German bunds | |
We are neutral Bunds. Current ECB rate pricing looks more fairly valued given the balance of risks. Fiscal stimulus and increased bond issuance exert upward pressure on yields, alongside inflation risks amid lingering geopolitical tensions. | ||
| French OATs | |
We are neutral. Elevated political uncertainty, high budget deficits and slow structural reforms could stoke volatility, but these risks already seem priced into OATs and we don’t expect a material worsening from here. | ||
| Italian BTPs | |
We are neutral. The spread over German bunds looks tight given Italy’s large budget deficits and growing public debt. Domestic factors remain supportive, with growth holding up relative to the rest of the euro area and local demand for BTPs solid at current yield levels. Domestic disapproval would likely prevent defense spending from reaching fiscally unstable levels. Political uncertainty is likely to increase ahead of next year’s elections. | ||
| UK gilts | |
We are neutral. We expect periods of elevated volatility given political uncertainty, longer-term bonds making up a larger market share, and buyers becoming more price-sensitive. | ||
| Swiss government bonds | |
We are neutral. The SNB seems comfortable with its medium-term inflation outlook and its current policy stance. Market pricing is broadly in line with SNB messaging. | ||
| European inflation-protected securities | |
We are neutral. We see higher medium-term inflation, but inflation expectations are firmly anchored. Cooling inflation and uncertain growth may matter more near term. | ||
| European investment grade | |
European investment grade is supported by healthy corporate sector balance sheets, contained default rates and the persistently strong demand for durable income from European households. We prefer European investment grade over the US. | ||
| European high yield | |
We are overweight. While spreads are low, the income potential remains attractive. Defaults are contained and high yield is of higher quality and less sensitive to interest rate swings compared with the US. | ||
Past performance is not a reliable indicator of current or future results. It is not possible to invest directly in an index. Note: Views are from a euro perspective, October 2026. This material represents an assessment of the market environment at a specific time and is not intended to be a forecast or guarantee of future results. This information should not be relied upon as investment advice regarding any particular fund, strategy or security.
Meet the authors

Jean Boivin
Head – BlackRock Investment Institute

Rick Rieder
Chief Investment Officer of Global Fixed Income – BlackRock

Wei Li
Global Chief Investment Strategist – BlackRock
This material is for distribution to Professional Clients (as defined by the FCA Rules) and should not be relied upon by any other persons.
Issued by BlackRock Investment Management (UK) Limited, authorised and regulated by the Financial Conduct Authority. Registered office: 12 Throgmorton Avenue, London, EC2N 2DL. Tel: 020 7743 3000. Registered in England No. 2020394. For your protection telephone calls are usually recorded. BlackRock is a trading name of BlackRock Investment Management (UK) Limited.
Sources: Bloomberg unless otherwise specified.
Past performance is not a guide to future performance. The value of investments and the income from them can fall as well as rise and is not guaranteed. You may not get back the amount originally invested. Changes in the rates of exchange between currencies may cause the value of investments to diminish or increase. Fluctuation may be particularly marked in the case of a higher volatility fund and the value of an investment may fall suddenly and substantially. Levels and basis of taxation may change from time to time.
Any research in this document has been procured and may have been acted on by BlackRock for its own purpose. The results of such research are being made available only incidentally. The views expressed do not constitute investment or any other advice and are subject to change. They do not necessarily reflect the views of any company in the BlackRock Group or any part thereof and no assurances are made as to their accuracy.
The opinions expressed in this paper may change as subsequent conditions vary. The information and opinions contained in this paper are derived from proprietary and nonproprietary sources deemed by BlackRock to be reliable, are not necessarily all-inclusive and are not guaranteed as to accuracy. As such, no warranty of accuracy or reliability is given and no responsibility arising in any other way for errors and omissions (including responsibility to any person by reason of negligence) is accepted by BlackRock, its officers, employees or agents.
This paper may contain “forward-looking” information that is not purely historical in nature. Such information may include, among other things, projections and forecasts. There is no guarantee that any forecasts made will come to pass. Reliance upon information in this paper is at the sole discretion of the reader.
This document is for information purposes only and does not constitute an offer or invitation to anyone to invest in any BlackRock funds and has not been prepared in connection with any such offer.
© 2026 BlackRock, Inc. All Rights reserved. BLACKROCK, BLACKROCK SOLUTIONS, iSHARES, BUILD ON BLACKROCK and SO WHAT DO I DO WITH MY MONEY logo are registered and unregistered trademarks of BlackRock, Inc. or its subsidiaries in the United States and elsewhere. All other trademarks are those of their respective owners.
