Midterms and AI in focus at 2027 Forum
Market take
Weekly video_20261109
Roelof Salomons
Chief Investment Strategist for the Netherlands and the Nordics
BlackRock Investment Institute
SCRIPT
Header:
CAPITAL AT RISK. MARKETING MATERIAL.
Opening frame: What’s driving markets? Market take
Camera frame
Title slide: Midterms and AI in focus at 2027 Forum
We held our Forum as the U.S. midterms unfolded and markets increasingly priced in a supply-driven regime we’ve long described. Attention is now turning from the AI buildout to demand, adoption and who benefits, as competition for capital intensifies. These shifts will help shape our 2027 Global Outlook.
1: An evolving AI story
Markets are still working through what the Democratic sweep of Congress means for the AI buildout.
The buildout will continue, but the focus is now on whether it will be at the same scale and at the same pace. And whether adoption can keep up.
And that was a key discussion at our Forum last week. A slowdown could have significant consequences for markets. But it could also ease competition for capital and bring bond yields down. Much uncertainty remains about the speed and the size of the buildout. And that uncertainty was behind our move to neutral on U.S. equities and our upgrade of U.S. Treasuries last month.
2: Funding in focus
Competition for capital was another major focus. The AI buildout is competing for funding with government borrowing, with investment in energy and in defense. And Hyperscalers are still spending heavily, even as financing costs rise. And that raises a key question: Can stronger growth and earnings offset those higher costs, and where will the pressure show up next?
3: Eyeing rates
We’ve long expected rates to stay structurally higher. At the forum, the focus was on what that means for markets and portfolios. Shifting capital flows, changing correlations between stocks, bonds and currencies could create new sources of volatility and challenge traditional portfolio hedges. That makes staying flexible key to navigating risks and seizing opportunities.
Outro: Here’s our Market take
The takeaway from our Forum was that AI adoption and competition for capital are critical from here. These topics will be key for our 2027 Global Outlook published next month.
Closing frame: Read details: blackrock.com/weekly-commentary
At our internal 2027 Forum last week, the U.S. midterms, AI adoption and competition for capital ran through the debates among our portfolio managers.
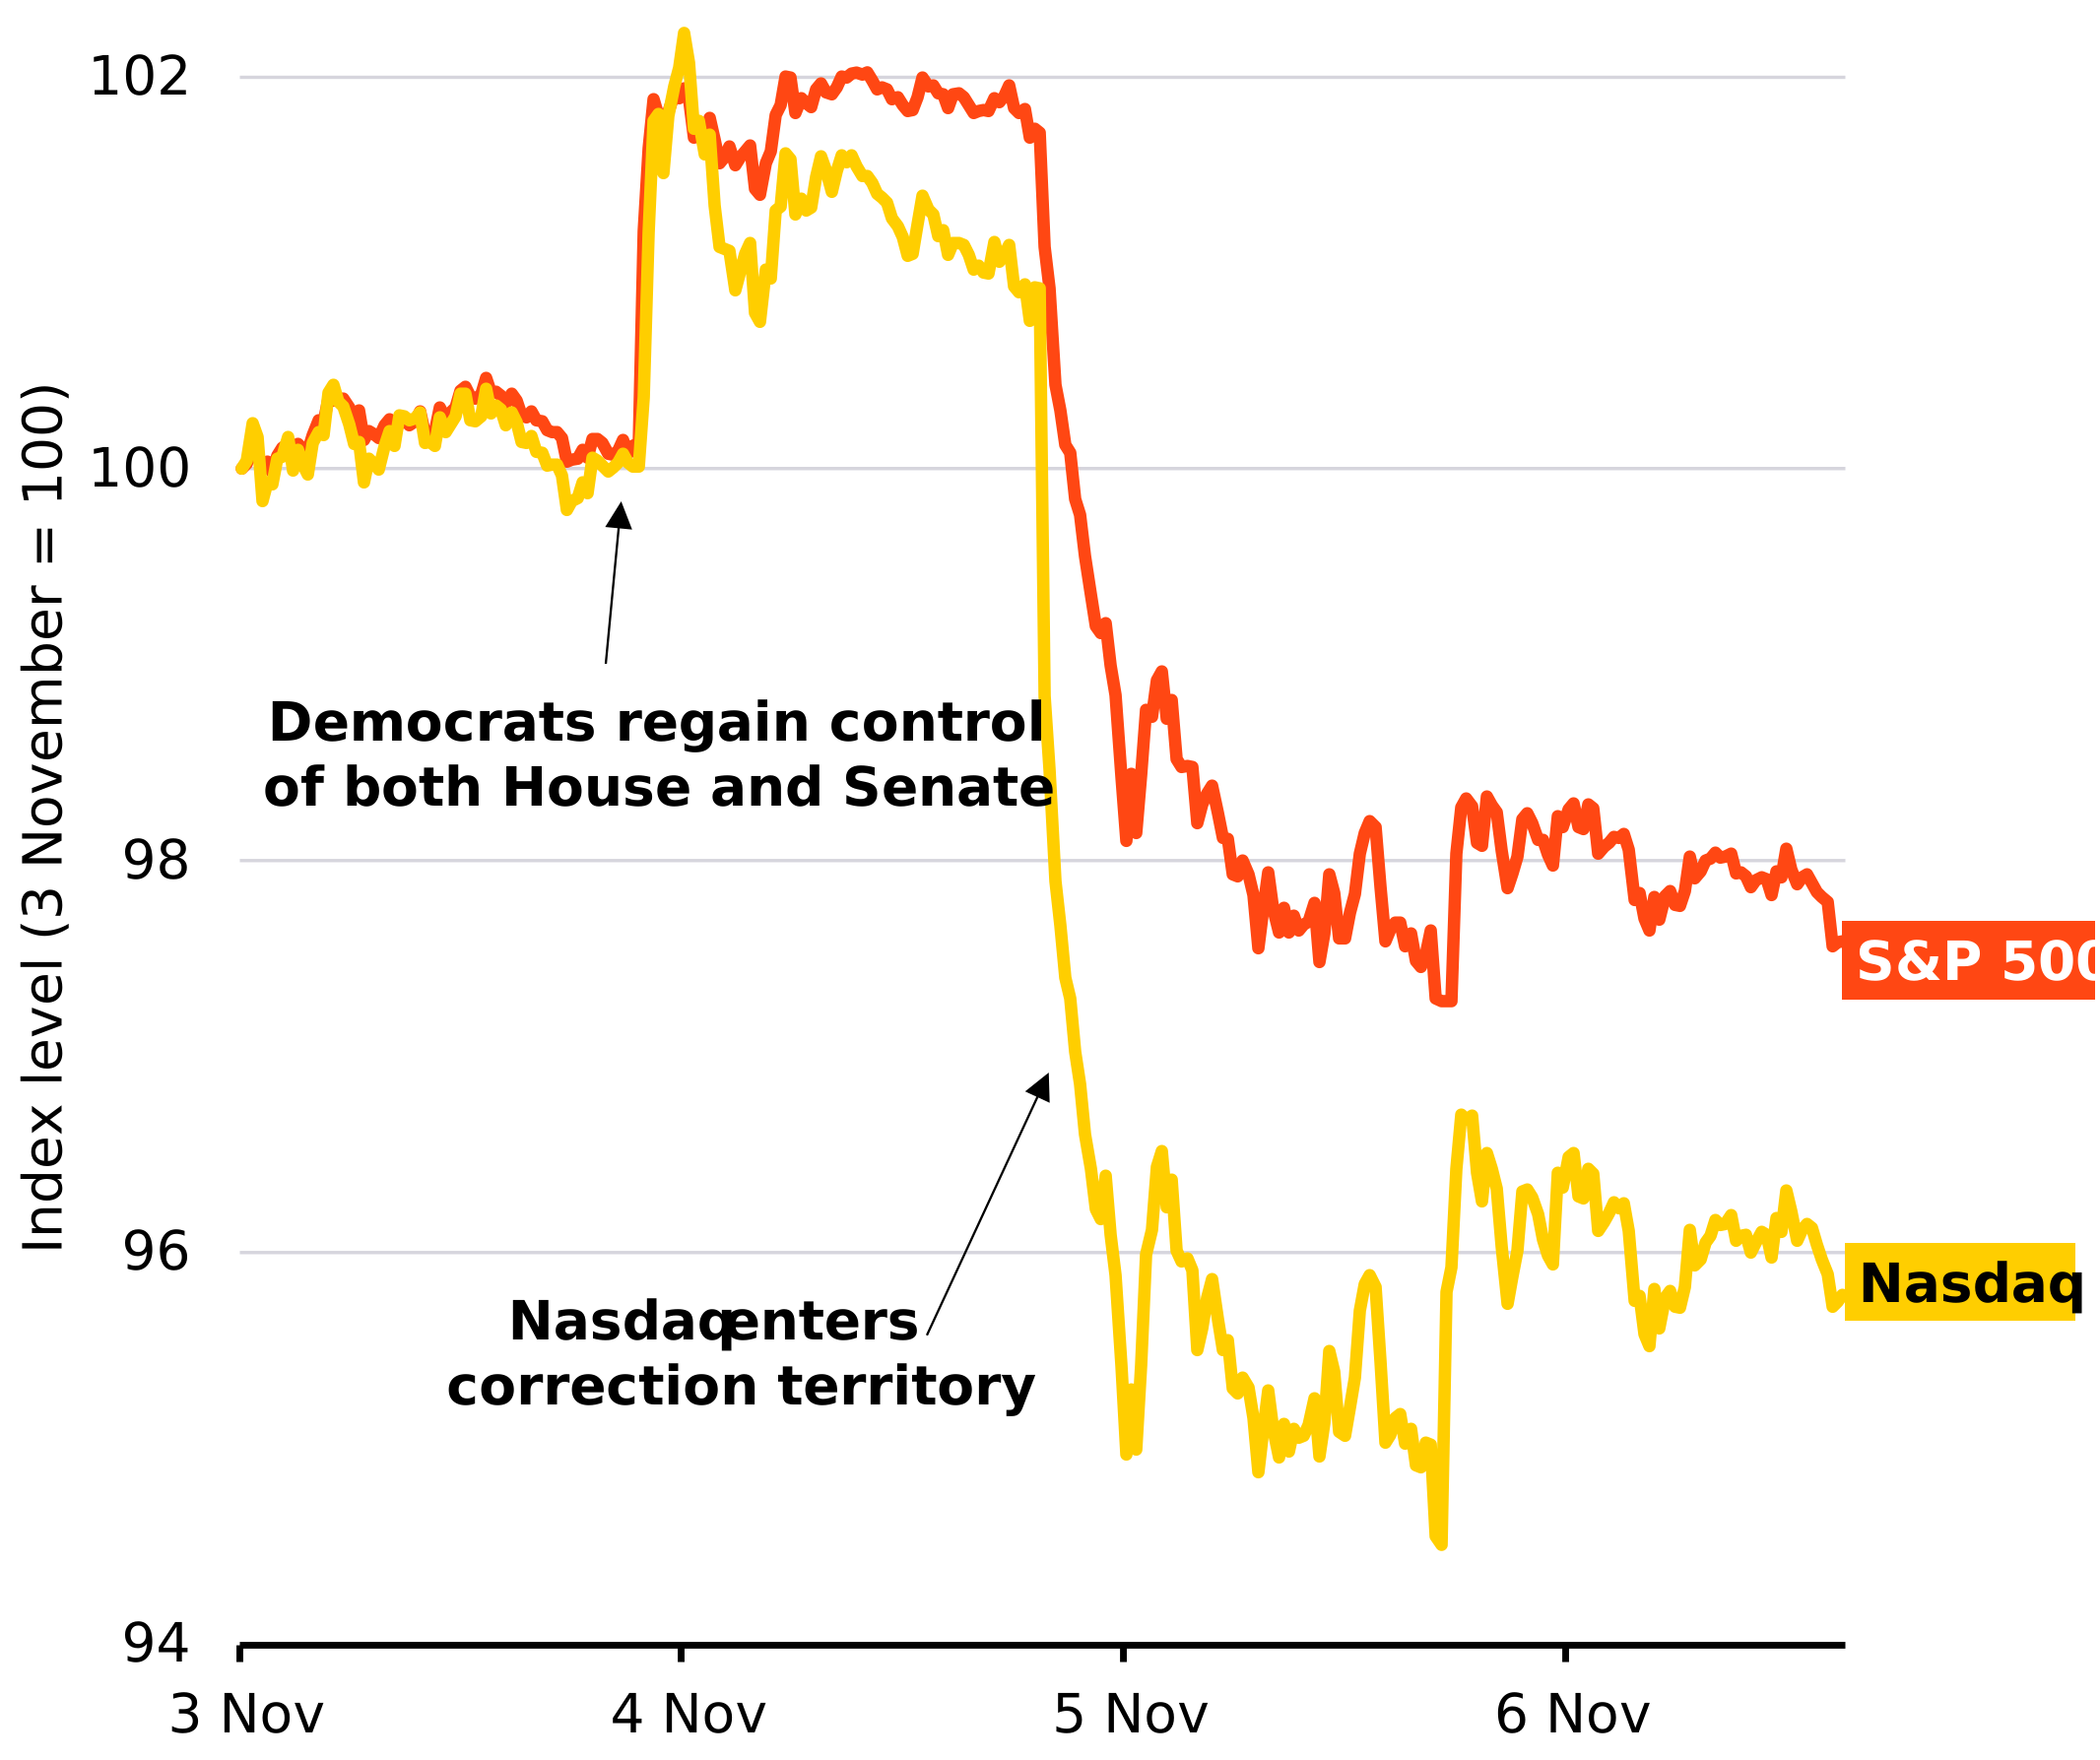
U.S. stocks fell sharply after a brief post-midterm rally, with the Nasdaq entering correction territory as concerns over the AI buildout intensified.
Following last week's strong U.S. payrolls report, CPI and PPI will offer fresh clues on inflation this week ahead of the Fed's December meeting.
The U.S. midterms dominated headlines last week as Democrats took control of Congress. Our 2027 Outlook Forum was consequential given the big unresolved macro questions. The supply-driven regime we’ve described for five years is largely priced in, making the outlook less directional. For AI, attention has shifted from the buildout toward demand, adoption and who benefits as competition for capital intensifies. These debates will shape next month’s 2027 Global Outlook.
From election bounce to correction
S&P 500 and Nasdaq intraday performance, November 3–6, 2026
Past performance is not a reliable indicator of current or future results. Source: BlackRock Investment Institute with data from Bloomberg, November 2026. Note: Index levels rebased to 100 on Nov. 3, 2026. Nasdaq correction refers to a decline of at least 5% from its previous peak.
U.S. stocks rallied the day after the elections, sold off sharply on Thursday and steadied on Friday. See the chart. The swings illustrate a key conclusion from our 2027 Outlook Forum: the AI story is moving into a more nuanced phase. In the initial phase of the AI transformation, the investment opportunity was about pricing the conviction that the buildout needed to happen. Now the focus is shifting to assessing the size and speed of the buildout relative to how quickly AI is adopted and spreads across different tasks. A material slowdown in 2027, though far from certain, could have significant adverse market consequences. But it could also ease competition for capital and lower bond yields, while its economic fallout could temper policy initiatives. This two-sided uncertainty underpinned our move to neutral on U.S. equities and our upgrade of U.S. Treasuries last month.
The AI infrastructure boom has been a powerful driver of growth, earnings and market returns. But how long will scarcity persist, and where might abundance emerge as constraints ease? These questions ran through our Forum discussions. Participants debated how much AI capacity will ultimately be built, whether demand from adoption can justify the scale of investment and when opportunities might shift from suppliers to adopters. We heard directly from corporate CFOs about how they are deploying AI and assessing its benefits, offering a window into demand that remains difficult to measure. Another question was what would happen if capital spending slowed before productivity gains from adoption materialized. And who ultimately captures the gains and who gets disrupted – technology providers, businesses adopting AI or their customers?
Competition for capital a hot topic
Competition for capital was another major topic, as the extraordinary financing needs of AI collide with government borrowing and investment in energy security and defense. Our portfolio managers debated whether this growing demand for funding could crowd out other borrowers, even as AI investment supports economic growth and risk assets. With credit markets becoming more selective, participants also discussed whether greater equity issuance could help hyperscalers manage leverage and preserve their capacity to borrow as the buildout continues. Another key question was whether stronger growth and earnings can continue to offset higher financing costs – and where the pressure might emerge next.
The Forum came at a consequential juncture. After four years of an AI-driven bull market, markets have largely priced in the new regime of structurally higher interest rates we’ve talked about for five years. That makes the investment outlook less directional and more nuanced. Discussions ranged from shifting global capital flows and changing relationships between stocks, bonds and currencies to investment opportunities across Europe, China and emerging markets. Participants also explored how evolving market structures could affect market liquidity and volatility. The reliability of traditional portfolio hedges and the importance of retaining flexibility were also major topics.
Our bottom line
Our 2027 Outlook Forum highlighted the questions facing investors as the supply-driven regime we’ve described for five years becomes increasingly priced in. Look out for more in our 2027 Global Outlook next month.
Market backdrop
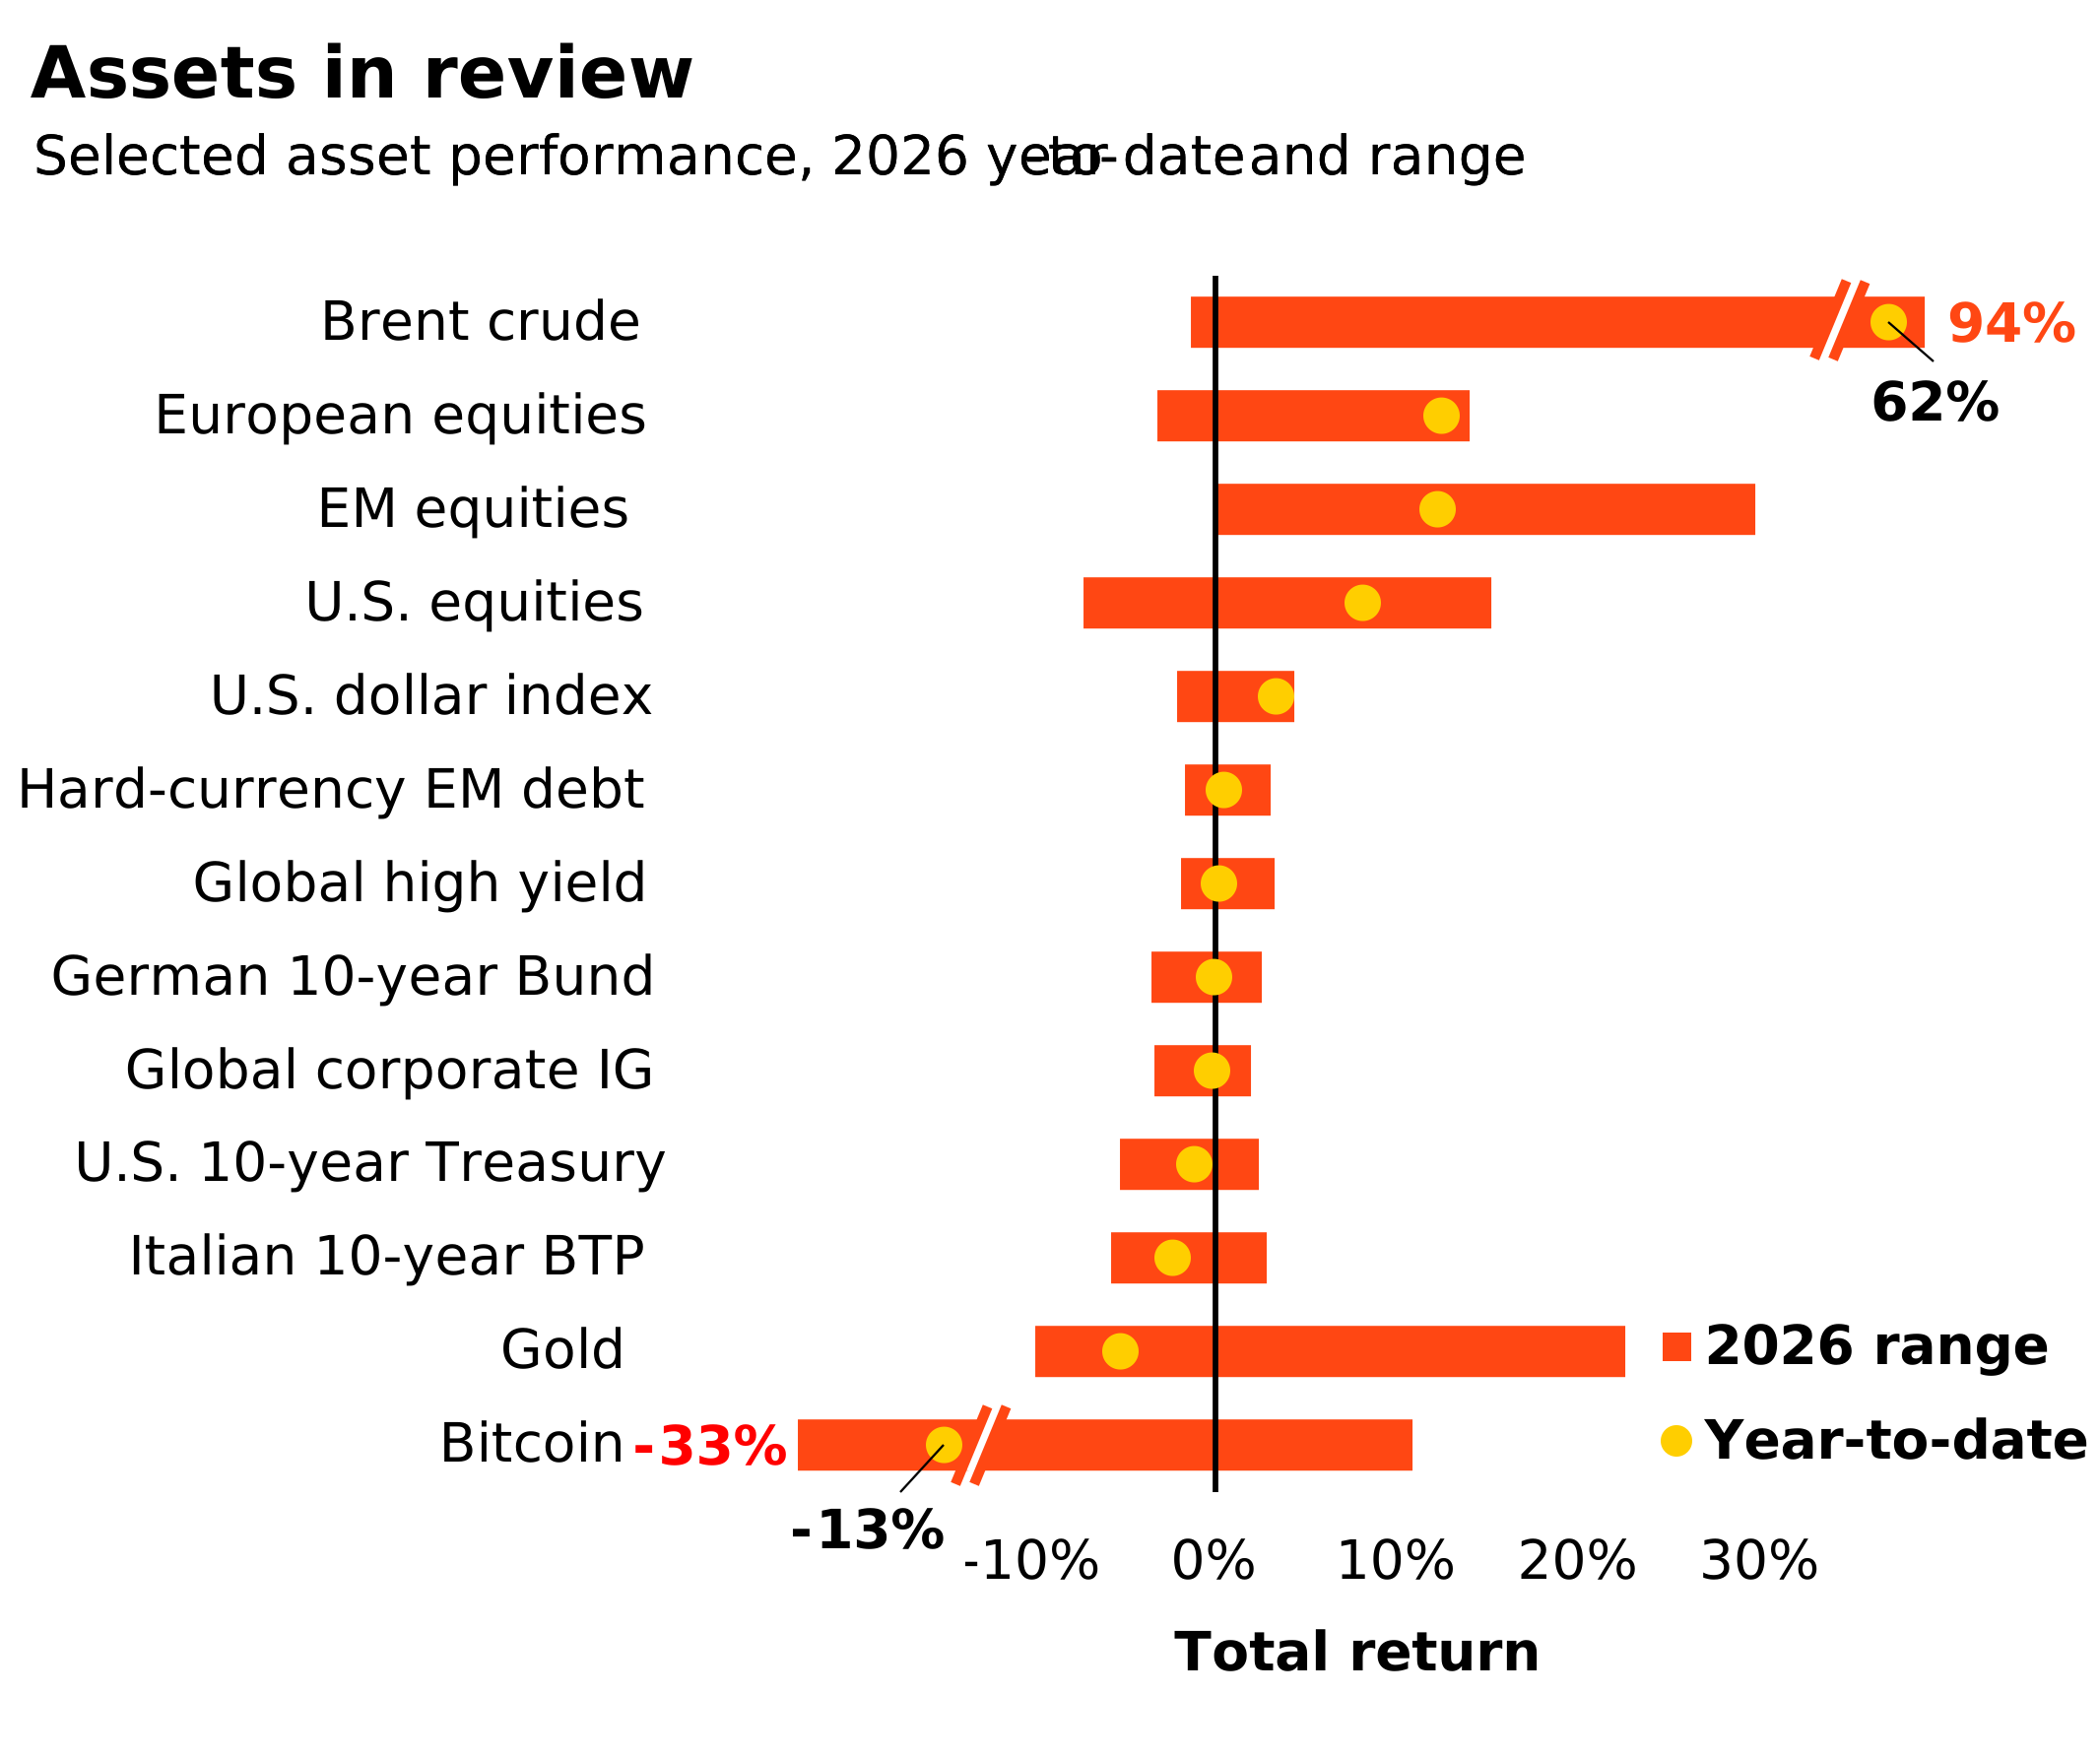
U.S. stocks fell sharply last week following the Democratic sweep in the midterm elections, despite a rebound on Friday. For the week, the Nasdaq 100 lost 4.7%, leaving it 14% below its October peak, while the S&P 500 dropped 2.4%. U.S. Treasuries rallied, with 10-year yields falling 13 basis points over the week to 4.86%. Brent crude fell 17% to $97 a barrel amid hopes for an end to the Middle East conflict.
U.S. inflation data take center stage this week, with CPI and PPI offering the latest read on price pressures ahead of the Fed's December policy meeting. We expect persistent inflation pressures to keep market expectations for further Fed rate hikes alive. China's inflation and trade data will shed light on domestic demand and external activity, while UK and euro area GDP figures will provide a snapshot of European growth.
Week ahead
Past performance is not a reliable indicator of current or future results. Indexes are unmanaged and do not account for fees. It is not possible to invest directly in an index. Sources: BlackRock Investment Institute, with data from LSEG Datastream as of November 5, 2026. Notes: The two ends of the bars show the lowest and highest returns at any point year to date, and the dots represent current year-to-date returns. Emerging market (EM), high yield and global corporate investment grade (IG) returns are denominated in U.S. dollars, and the rest in local currencies. Indexes or prices used are: spot Brent crude, ICE U.S. Dollar Index (DXY), spot gold, spot bitcoin, MSCI Emerging Markets Index, MSCI Europe Index, LSEG Datastream 10-year benchmark government bond index (U.S., Germany and Italy), Bloomberg Global High Yield Index, J.P. Morgan EMBI Index, Bloomberg Global Corporate Index and MSCI USA Index.
China PPI & CPI
U.S. CPI; China trade balance
UK GDP estimate
U.S. PPI; EU GDP & employment flash estimate
Read our past weekly market commentaries here.
Intersecting mega forces
Since we launched our mega forces framework it has become clearer how their intersection shapes almost all our investment views and opens up alpha opportunities. They cut across asset class labels, spurring a rethink of portfolio construction. Investors need to be deliberate about the economic or thematic exposures they own, the vehicles they use to implement them and their investment horizons.

From drivers to portfolio expressions
Our highest conviction views, November 2026
| Driver | What we think | Portfolio expression |
|---|---|---|
| Growth and AI scarcity | AI fundamentals are strong, but we eye near-term volatility. | Neutral U.S. equities and overweight EM equities; favor AI- and tech-related opportunities. |
| Duration and diversification | Higher starting yields improve prospective returns and income. | Overweight short-term U.S. Treasuries for solid income and a cushion against higher rates; neutral long-term Treasuries |
| Credit spreads and liquidity | Selectivity is crucial amid tight spreads and uneven fundamentals. | Credit with clear cash flows, lender protections and recovery value; higher-rated high yield. |
| Inflation and scarcity | Scarcity, secure supply and power demand carry inflation risks. | Infrastructure, energy bottlenecks, EM local debt and real-asset-linked exposures. |
| Alpha opportunity | Macro outcomes matter again in the new regime. | Macro hedge funds, venture capital, market-neutral strategies, and selected private credit and non-U.S. alpha. |
Note: Views are from a U.S. dollar perspective, November 2026. This material represents an assessment of the market environment at a specific time and is not intended to be a forecast of future events or a guarantee of future results. This information should not be relied upon by the reader as research or investment advice regarding any particular funds, strategy or security.
Asset class implications
Six- to 12-month tactical positioning, November 2026
This shows the implementation of our key investment views from the previous page through an asset class lens.

| Asset | Tactical view | Commentary | ||||
|---|---|---|---|---|---|---|
| Equities | ||||||
| United States | We are neutral. Strong AI fundamentals remain supportive, but policy uncertainty could fuel near-term volatility. We continue to favor AI and tech. | |||||
| Europe | We are neutral. We would need to see more business-friendly policy and deeper capital markets for Europe to outperform. We favor financials, infrastructure, and industrials. | |||||
| UK | We are neutral. Valuations remain attractive relative to the U.S., but we see few near-term catalysts to trigger a shift. | |||||
| Japan | We are neutral. Strong corporate balance sheets and governance reforms remain supportive. We prefer targeted exposures to physical AI and the buildout’s bottlenecks. | |||||
| Emerging markets (EM) | We are overweight. Strong earnings and cheaper valuations create opportunities. We particularly like different expressions of the AI scarcity theme across Asia and Latin America. | |||||
| China | We are neutral. We see opportunities in physical AI. Cheap, open-source AI could drive adoption, but that doesn’t necessarily translate into AI-provider profitability. | |||||
| Fixed income | ||||||
| Short U.S. Treasuries | We are overweight. Much of the repricing we anticipated has occurred, and expectations for further Fed hikes look excessive. We favor the front end for attractive income and a greater breakeven buffer. | |||||
| Long U.S. Treasuries | We are neutral. Higher yields offer attractive income and a bigger cushion against further rate increases. We still see room for yields to rise as competition for capital intensifies. | |||||
| Global inflation-linked bonds | We are neutral. We see inflation settling above pre-pandemic levels, but markets may not price this in the near term as economic growth could slow. | |||||
| Euro area government bonds | We are neutral short- and medium-term bonds. Current ECB rate pricing looks fairly valued given the balance of risks. Higher energy prices could push rates higher. We prefer to deploy risk elsewhere. | |||||
| UK gilts | We are neutral. We expect periods of elevated volatility given political uncertainty, longer-term bonds making up a larger market share, and buyers becoming more price-sensitive. | |||||
| Japanese government bonds | We are underweight. The substantial repricing in yields has improved the risk-reward, but further rate hikes and heavy issuance could push yields higher. | |||||
| China government bonds | We are neutral. China bonds offer stability and diversification but developed market yields are higher. A shift in investor sentiment toward equities limits upside. | |||||
| U.S. agency MBS | We are neutral and lean into the stable income MBS provide despite tight spreads. | |||||
| Short-term IG credit | We are neutral. Spreads are tight due to corporate strength; they could widen if issuance increases or risk appetite shifts. | |||||
| Long-term IG credit | We are underweight. We prefer short-term bonds less exposed to interest rate risk over long-term bonds. But attractive overall yields help offset the risk of increased issuance. | |||||
| Global high yield | We are neutral. High yield offers attractive income. We prefer higher-rated U.S. and European high yield over investment grade and see dispersion of returns increasing. | |||||
| Asia credit | We are neutral. Overall yields are attractive and fundamentals are solid, but spreads are tight. | |||||
| Emerging hard currency | We are neutral. Fundamentals have improved, but we see a more attractive risk-reward profile in EM local debt. | |||||
| Emerging local currency | We are overweight. We like the yield relative to its volatility and improving fundamentals. | |||||
Past performance is not a reliable indicator of current or future results. It is not possible to invest directly in an index. Note: Views are from a U.S. dollar perspective. This material represents an assessment of the market environment at a specific time and is not intended to be a forecast or guarantee of future results. This information should not be relied upon as investment advice regarding any particular fund, strategy or security.
Euro-denominated tactical granular views
Six to 12-month tactical views on selected assets vs. broad global asset classes by level of conviction, November 2026

We have lengthened our tactical investment horizon back to six to 12 months. The table below reflects this and, importantly, leaves aside the opportunity for alpha, or the potential to generate above-benchmark returns – especially at a time of heightened volatility.
| Asset | Tactical view | Commentary | ||
|---|---|---|---|---|
| Equities | ||||
| Europe ex UK | We are neutral. We would need to see more business-friendly policy and deeper capital markets for Europe to outperform and to justify a broad overweight. We stay selective, favoring financials, infrastructure, industrials, materials and healthcare. | |||
| Germany | We are neutral. Higher spending on defense and infrastructure support the corporate sector. Valuations are not stretched but neither compelling and expected earnings growth lags other countries. Light positioning means potential easing in geopolitical tensions and AI lifting industrials-driven earnings could create opportunities. | |||
| France | We are neutral. Strong expected earnings growth and global revenue exposure support French corporates. Valuations are less compelling, albeit not stretched versus euro area peers. Persistent political uncertainty leaves the overall risk reward balanced. | |||
| Italy | We are neutral. Earnings growth and momentum are strong, boosted by the significant exposure to financials, utilities and energy. Valuations are still at discount vs. peers, but not as much as in previous years. Political risk is currently low but likely to pick up ahead of 2027 elections. | |||
| Spain | We are overweight. Valuations remain attractive vs. peers even if relative earnings momentum has slowed. Strong domestic demand growth and exposure to fast-growing areas like Latin America support Spanish stocks. Financials, utilities and infrastructure-linked stocks would benefit from Europe’s push towards autonomy. | |||
| Netherlands | We are neutral. Earnings revisions in the IT sector, a large sector in the Dutch stock market is offset by other sectors seeing less favorable valuations and a weaker earnings outlook than European peers. | |||
| Switzerland | We are neutral. Valuations have improved, from stretched levels, but the earnings outlook is weaker than other European markets. If global risk appetite stays strong, the index’s tilt to stable, less volatile sectors may weigh on performance . | |||
| UK | We are neutral. Valuations remain attractive relative to the U.S., but we see few near-term catalysts to trigger a shift. | |||
| Fixed income | ||||
| Euro area government bonds | We are neutral short- and medium-term bonds. Current ECB rate pricing looks fairly valued given the balance of risks. Higher energy prices could push rates higher. We prefer to deploy risk elsewhere. | |||
| German bunds | We are neutral Bunds. Current ECB rate pricing looks more fairly valued given the balance of risks. Fiscal stimulus and increased bond issuance exert upward pressure on yields, alongside inflation risks amid lingering geopolitical tensions. | |||
| French OATs | We are neutral. Elevated political uncertainty, high budget deficits and slow structural reforms could stoke volatility, but these risks already seem priced into OATs and we don’t expect a material worsening from here. | |||
| Italian BTPs | We are neutral. The spread over German bunds looks tight given Italy’s large budget deficits and growing public debt. Domestic factors remain supportive, with growth holding up relative to the rest of the euro area and local demand for BTPs solid at current yield levels. Domestic disapproval would likely prevent defense spending from reaching fiscally unstable levels. Political uncertainty is likely to increase ahead of next year’s elections. | |||
| UK gilts | We are neutral. We expect periods of elevated volatility given political uncertainty, longer-term bonds making up a larger market share, and buyers becoming more price-sensitive. | |||
| Swiss government bonds | We are neutral. The SNB seems comfortable with its medium-term inflation outlook and its current policy stance. Market pricing is broadly in line with SNB messaging. | |||
| European inflation-protected securities | We are neutral. We see higher medium-term inflation, but inflation expectations are firmly anchored. Cooling inflation and uncertain growth may matter more near term. | |||
| European investment grade | European investment grade is supported by healthy corporate sector balance sheets, contained default rates and the persistently strong demand for durable income from European households. We prefer European investment grade over the U.S. | |||
| European high yield | We are overweight. While spreads are low, the income potential remains attractive. Defaults are contained and high yield is of higher quality and less sensitive to interest rate swings compared with the U.S. | |||
Past performance is not a reliable indicator of current or future results. It is not possible to invest directly in an index. Note: Views are from a euro perspective, November 2026. This material represents an assessment of the market environment at a specific time and is not intended to be a forecast or guarantee of future results. This information should not be relied upon as investment advice regarding any particular fund, strategy or security.
On the go?