MARKET INSIGHTS

Weekly market commentary

EM equities: back to overweight

Market take

Weekly video_20260914

Michel Dilmanian

Portfolio Strategist

BlackRock Investment Institute

SCRIPT

Header:

CAPITAL AT RISK. MARKETING MATERIAL.

Opening frame: What’s driving markets? Market take

Camera frame

Title slide: EM equities: back to overweight

Higher interest rates don't automatically mean trouble for stocks. The key question is: why are yields rising? If they're moving up because investment and growth are accelerating, stronger earnings can help outweigh the impact of higher borrowing costs. That nuance helps explain our pro-risk stance.

1: Back to overweight EM stocks

So, why did our views on EM stocks change? Earnings durability is a key measure as interest rates reset higher. EM equities stand out by this measure.

Earnings growth has accelerated, while valuations remain well below those in the U.S. We stepped back to neutral in June as leverage concerns, especially in Korea, were building. Since then, deleveraging has eased those concerns, supporting our move back to overweight.

2: The AI scarcity play

EM equities offer another way to express one of our highest conviction investment themes: AI scarcity. South Korea and Taiwan are key players in the semiconductor, memory and hardware supply chains powering the AI buildout. Meanwhile, Latin America offers exposure to other scarce resources and physical infrastructure supporting the AI buildout.

All of these are different expressions of the AI scarcity theme that underpins our U.S. equity overweight.

3: Staying sharp

We stay pro-risk, but nimble. Our return to overweight in EM equities comes alongside our downgrade of short-term European government bonds. More broadly, we're sticking with our overweights in U.S. equities and AI.

We're also keeping a close eye on the key assumptions behind those views. If AI earnings disappoint, leverage concerns grow, or higher long-term rates create a bigger hurdle for stocks, we'd reassess. As always, we're ready to adjust as conditions change.

Outro: Here’s our Market take

We remain pro-risk as strong fundamentals help offset the impact of higher interest rates. But this isn't an all-clear signal, and we'll adjust our views if the data points us in a different direction.

Closing frame: Read details: blackrock.com/weekly-commentary
EM back in focus

We stay pro-risk despite higher rates. Strong fundamentals and AI scarcity support our U.S. equity overweight and return to an overweight in EM equities.

Market backdrop

Oil topped $100 and long-term yields remain near multi-decade highs, yet stocks are near records. We think higher rates and strong equities can coexist.

Week ahead

The Fed, BoE and BoJ take center stage this week. Their rate decisions will keep global yields and currencies in focus as policy paths diverge.

Higher global rates are raising the hurdle for returns, but they have not knocked us off our pro-risk stance. Higher rates and strong equities need not be contradictory – what drives yields matters. When higher yields reflect stronger investment and growth, the resulting earnings strength can help offset a higher cost of capital. That explains why we maintain our U.S. equity and AI overweights. Our return to an overweight in EM equities offers another way to invest in the AI scarcity theme.

Download full commentary (PDF)

Paragraph-2,Paragraph-3,Image-1,Paragraph-4
Paragraph-5,Advance Static Table-1,Paragraph-6,Advance Static Table-2,Paragraph-7,Advance Static Table-3,Paragraph-8,Advance Static Table-4

Exceptional growth without demanding valuations

12-month forward EPS growth and P/E, 2016–26

This chart shows EM equities pairing exceptional earnings growth with undemanding valuations. Forward earnings growth is far above U.S. levels, while price-to-earnings multiples remain about half those of U.S. stocks.

Forward-looking estimates may not come to pass. Source: BlackRock Investment Institute, with data from LSEG Datastream, September 2026. Note: The chart shows 12-month forward consensus earnings-per-share growth and price-to-earnings ratios for the MSCI EM and MSCI U.S. indices.

The bar for taking risk is rising as rates reset higher, making the durability of earnings more important. We think AI-related investment can support growth and profits even as the same investment boom absorbs capital, power and other scarce resources. EM equities now offer another place where earnings can clear that higher hurdle. The fundamental case has strengthened: earnings growth is exceptional even as valuations remain well below those in the U.S. See the chart. The tactical backdrop has improved too. We closed our previous overweight in EM equities in our Midyear Outlook in June as leverage concerns built, particularly in Korea. Korean equities subsequently experienced losses, and summer deleveraging has since eased those leverage concerns, supporting our return to overweight.

The numbers reinforce the case for returning to EM equities. Consensus expects headline earnings per share for the MSCI Emerging Markets Index to grow over 34% over the next 12 months versus about 20% for the MSCI USA Index. Yet EM equities trade at only 10 times forward earnings versus nearly 20 times for their U.S. counterparts. That is a 50% discount, with the EM multiple in the bottom 10% of its 20-year history. A weaker U.S. dollar could add support by easing financial conditions, supporting local currencies and encouraging foreign capital inflows. But our view does not depend on it. We see dollar weakness and stronger inflows as additional support rather than the foundation of our EM call.

EM at the center of AI scarcity

The headline EM rally masks very different sources of returns, but AI scarcity is one thread connecting them. South Korea and Taiwan sit at the heart of semiconductor, memory and hardware supply chains. Latin America, including Brazil, offers exposure to the resources and physical infrastructure needed for the AI buildout. These are different expressions of the AI scarcity theme that is an important part of our U.S. equity overweight. That overlap is deliberate and concentrates some of our equity exposure to the AI buildout. Over time, cheaper models and greater commoditization could shift where AI profits accrue. We therefore prefer to stay selective and dynamic rather than assume today’s winners will remain tomorrow’s.

We remain pro-risk, but see little room for complacency. We maintain our U.S. equity and AI overweights, return to an overweight in EM equities and downgrade short-term European government bonds to neutral. Two risks could challenge that stance. First, markets have absorbed the Middle East shock well, but Strait of Hormuz traffic remains severely constrained and scarcity has shifted downstream into refined products. Renewed energy pressure could keep inflation elevated just as the Fed faces a difficult policy choice. A hold despite persistent inflation and a tight labor market could test its credibility, with the term premium acting as a release valve as investors demand more compensation to hold long-term bonds. That could push long-end yields higher and raise the hurdle for equity returns. We stand ready to adjust as conditions change.

Our bottom line

Strong fundamentals keep us pro-risk despite higher rates. Exceptional earnings growth, attractive valuations and a cleaner tactical backdrop support our U.S. and AI overweights and a return to an overweight in EM equities. But this is not an unqualified bullish call. A lot can still go wrong, and we stand ready to shift from risk-on if the signposts change.

Market backdrop

Markets are balancing mounting macro pressures against strong corporate fundamentals. Brent crude topped $100 a barrel for the first time since July after the U.S. and Iran traded fresh attacks, while new U.S. inflation data prompted markets to ramp up Fed rate hike expectations. Long-term government bond yields remain near multi-decade highs. Yet stocks remain close to record highs. We think strong earnings help explain that resilience: U.S. earnings expectations have continued to rise, giving equities a cushion against higher rates and energy prices and reinforcing our overweight in U.S. stocks.

Central banks take center stage this week, with the Federal Reserve, Bank of England and Bank of Japan all setting rates. Strong jobs and sticky inflation have sharply raised the market odds of a Fed hike, though we don’t see one as a foregone conclusion. The BoE is expected to hold and the BoJ may need to normalize faster. We expect the decisions to keep global yields and currencies in focus.

Week ahead

EM equities offer a rare mix of exceptional earnings growth and relatively modest valuations. Forward earnings growth far exceeds that of the U.S., yet EM stocks trade at roughly half the U.S. price-to-earnings multiple.

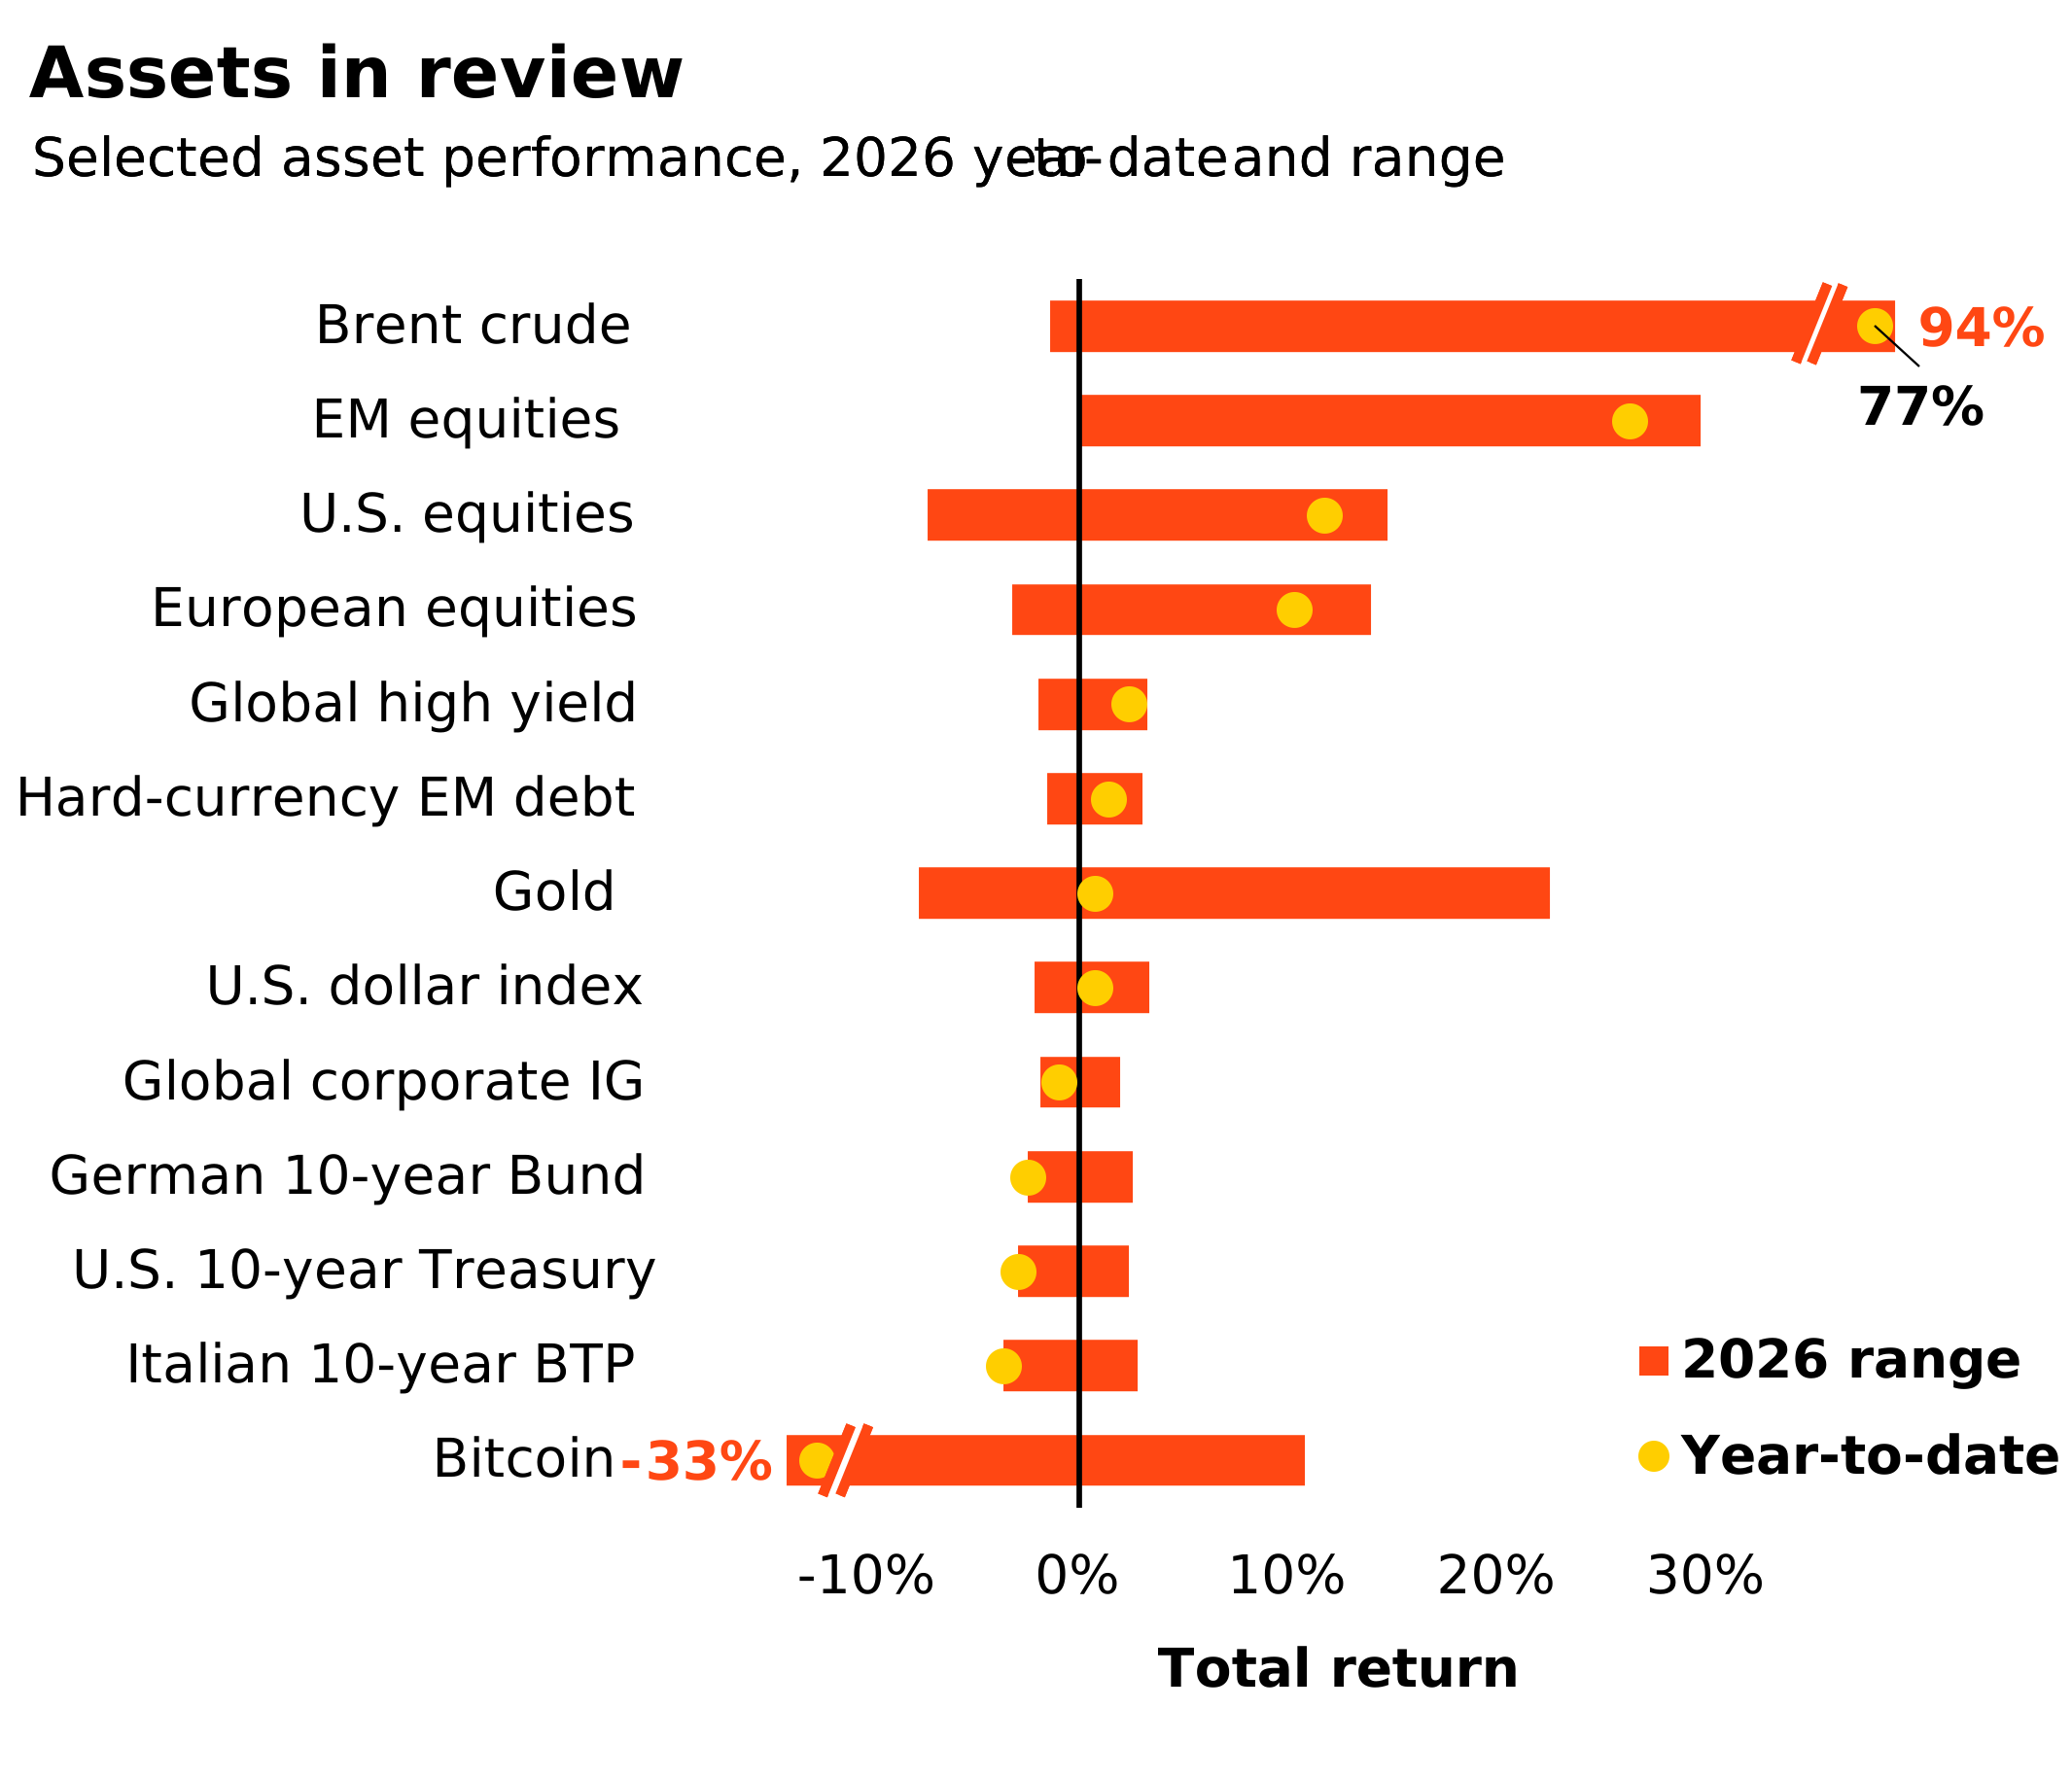
Past performance is not a reliable indicator of current or future results. Indexes are unmanaged and do not account for fees. It is not possible to invest directly in an index. Sources: BlackRock Investment Institute, with data from LSEG Datastream as of September 10, 2026. Notes: The two ends of the bars show the lowest and highest res at any point year to date, and the dots represent current year-to-date res. Emerging market (EM), high yield and global corporate investment grade (IG) res are denominated in U.S. dollars, and the rest in local currencies. Indexes or prices used are: spot Brent crude, ICE U.S. Dollar Index (DXY), spot gold, spot bitcoin, MSCI Emerging Markets Index, MSCI Europe Index, LSEG Datastream 10-year benchmark government bond index (U.S., Germany and Italy), Bloomberg Global High Yield Index, J.P. Morgan EMBI Index, Bloomberg Global Corporate Index and MSCI USA Index.

Sep. 15

UK unemployment; China unemployment

Sep. 16

U.S. Fed rate decision; UK CPI; Japan trade balance

Sep. 17

UK BoE rate decision; U.S. Philly Fed business index, EU HICP final

Sep. 18

BoJ rate decision and Japan core CPI

Read our past weekly market commentaries here.

Intersecting mega forces

Since we launched our mega forces framework it has become clearer how their intersection shapes almost all our investment views and opens up alpha opportunities. They cut across asset class labels, spurring a rethink of portfolio construction. Investors need to be deliberate about the economic or thematic exposures they own, the vehicles they use to implement them and their investment horizons.

The chart shows BlackRock's five mega forces framework and how their intersection shapes investment views and opens up investment opportunities.

From drivers to portfolio expressions

Our highest conviction views, September 2026

Driver What we think Portfolio expression
Growth and AI scarcity The AI buildout is speeding up, making bottlenecks binding. Overweight U.S. and EM equities; focus on AI bottleneck opportunities: power, chips and data centers.
Duration and diversification Long bonds carry high rate sensitivity and are less reliable diversifiers. Prefer short- and medium-term government bonds over long bonds for income.
Credit spreads and liquidity Selectivity is crucial amid tight spreads and uneven fundamentals. Credit with clear cash flows, lender protections and recovery value; higher-rated high yield.
Inflation and scarcity Scarcity, secure supply and power demand carry inflation risks. Infrastructure, energy bottlenecks, EM local debt and real-asset-linked exposures.
Alpha opportunity Macro outcomes matter again in the new regime. Macro hedge funds, venture capital, market-neutral strategies, and selected private credit and non-U.S. alpha.

Note: Views are from a U.S. dollar perspective, September 2026. This material represents an assessment of the market environment at a specific time and is not intended to be a forecast of future events or a guarantee of future results. This information should not be relied upon by the reader as research or investment advice regarding any particular funds, strategy or security.

Asset class implications

Six- to 12-month tactical positioning, September 2026

This shows the implementation of our key investment views from the previous page through an asset class lens.

Legend Granular

Past performance is not a reliable indicator of current or future results. It is not possible to invest directly in an index. Note: Views are from a U.S. dollar perspective. This material represents an assessment of the market environment at a specific time and is not intended to be a forecast or guarantee of future results. This information should not be relied upon as investment advice regarding any particular fund, strategy or security.

Euro-denominated tactical granular views

Six to 12-month tactical views on selected assets vs. broad global asset classes by level of conviction, September 2026

Legend Granular

We have lengthened our tactical investment horizon back to six to 12 months. The table below reflects this and, importantly, leaves aside the opportunity for alpha, or the potential to generate above-benchmark returns – especially at a time of heightened volatility.

Past performance is not a reliable indicator of current or future results. It is not possible to invest directly in an index. Note: Views are from a euro perspective, September 2026. This material represents an assessment of the market environment at a specific time and is not intended to be a forecast or guarantee of future results. This information should not be relied upon as investment advice regarding any particular fund, strategy or security.

On the go?

Stay informed on our latest weekly Market take. Listen wherever you get your podcasts.
podcast banner
Meet the authors
Wei Li
Global Chief Investment Strategist – BlackRock Investment Institute
Beata Harasim
Senior Investment Strategist – BlackRock Investment Institute
Michel Dilmanian
Portfolio Strategist – BlackRock Investment Institute
Sam Vecht
Portfolio Manager, Global Emerging Market Equities – BlackRock