
U.S. dollar: surprisingly resilient
Market take
Weekly video_20261005
Michel Dilmanian
Portfolio Strategist
BlackRock Investment Institute
SCRIPT
Header:
CAPITAL AT RISK. MARKETING MATERIAL.
Opening frame: What’s driving markets? Market take
Camera frame
Title slide: U.S. dollar: surprisingly resilient
We think fundamental drivers, such as rate differentials, explain the dollar’s resilience this year, supporting our view that calls for its debasement are overdone. At the same time, we don’t think its strength means the beginning of a sustained upswing.
1: Big swings
The dollar has swung dramatically over the past 18 months. It dropped after the 'Liberation Day' tariffs, stabilized for a time, and then weakened again as investors questioned the Fed's credibility.
Now it's rebounding. The main reason? Markets have sharply repriced the path of Fed rates, pushing U.S. two-year yields higher relative to other developed market economies.
2: A more mundane picture
To be sure, we think market expectations for as many as four hikes over the next twelve months are overdone. If investors pare back expectations for further tightening, yield differentials could narrow and weigh on the dollar. That would reinforce our broader pro-risk stance and support our EM equity overweight.
3: More than one fundamental driver
But there’s more to the story. Strong U.S. growth, corporate earnings and AI investment have helped U.S. equities outperform for much of this year. Case in point: Foreign investors have poured nearly $1 trillion into U.S. assets in the 12 months through July, according to the Bureau of Economic Analysis. Our analysis also captures traditional drivers like risk sentiment and term premium.
On balance, we see little room for another sustained dollar rally. We expect the dollar to stay around current levels, if not somewhat weaker. That underscores skepticism of the debasement narrative around the dollar. If investors were losing confidence in the dollar’s long-term role, we would expect more weakness.
Outro: Here’s our Market take
The dollar’s resilience is largely explained by fundamental drivers, supporting our view that concerns about its long-term role are overdone. A stable or moderately weaker dollar would also reinforce our EM equity overweight.
Closing frame: Read details: blackrock.com/weekly-commentary
Dollar resilience
Fundamentals help explain the dollar’s resilience, supporting our view that it’s too soon to call for its demise. Yet we don’t think this portends a sustained rally.
Market backdrop
A soft U.S. jobs report helped cap gains in U.S. 10-year Treasury yields. Yet the structural forces driving long-term yields remain intact.
Week ahead
We look to September FOMC meeting minutes for details on the central bank’s discussion underscoring its first rate hike in three years.
The U.S. dollar has rallied over the past month, taking its gains this year to about 4% against developed-market currencies. Its resilience suggests it may be too soon to write off the dollar’s long-term role. Familiar drivers like rate differentials and risk sentiment help explain the rebound. Yet the greenback is stronger than the level suggested by our analysis. With markets pricing more Fed tightening than we think will materialize, there is limited scope for a sustained dollar bull run.
Paragraph-2,Image-1
Paragraph-3,Advance Static Table-1,Paragraph-4,Advance Static Table-2
Swing dollar
U.S. dollar index vs. trade-weighted two-year yield differential, 2022–2026
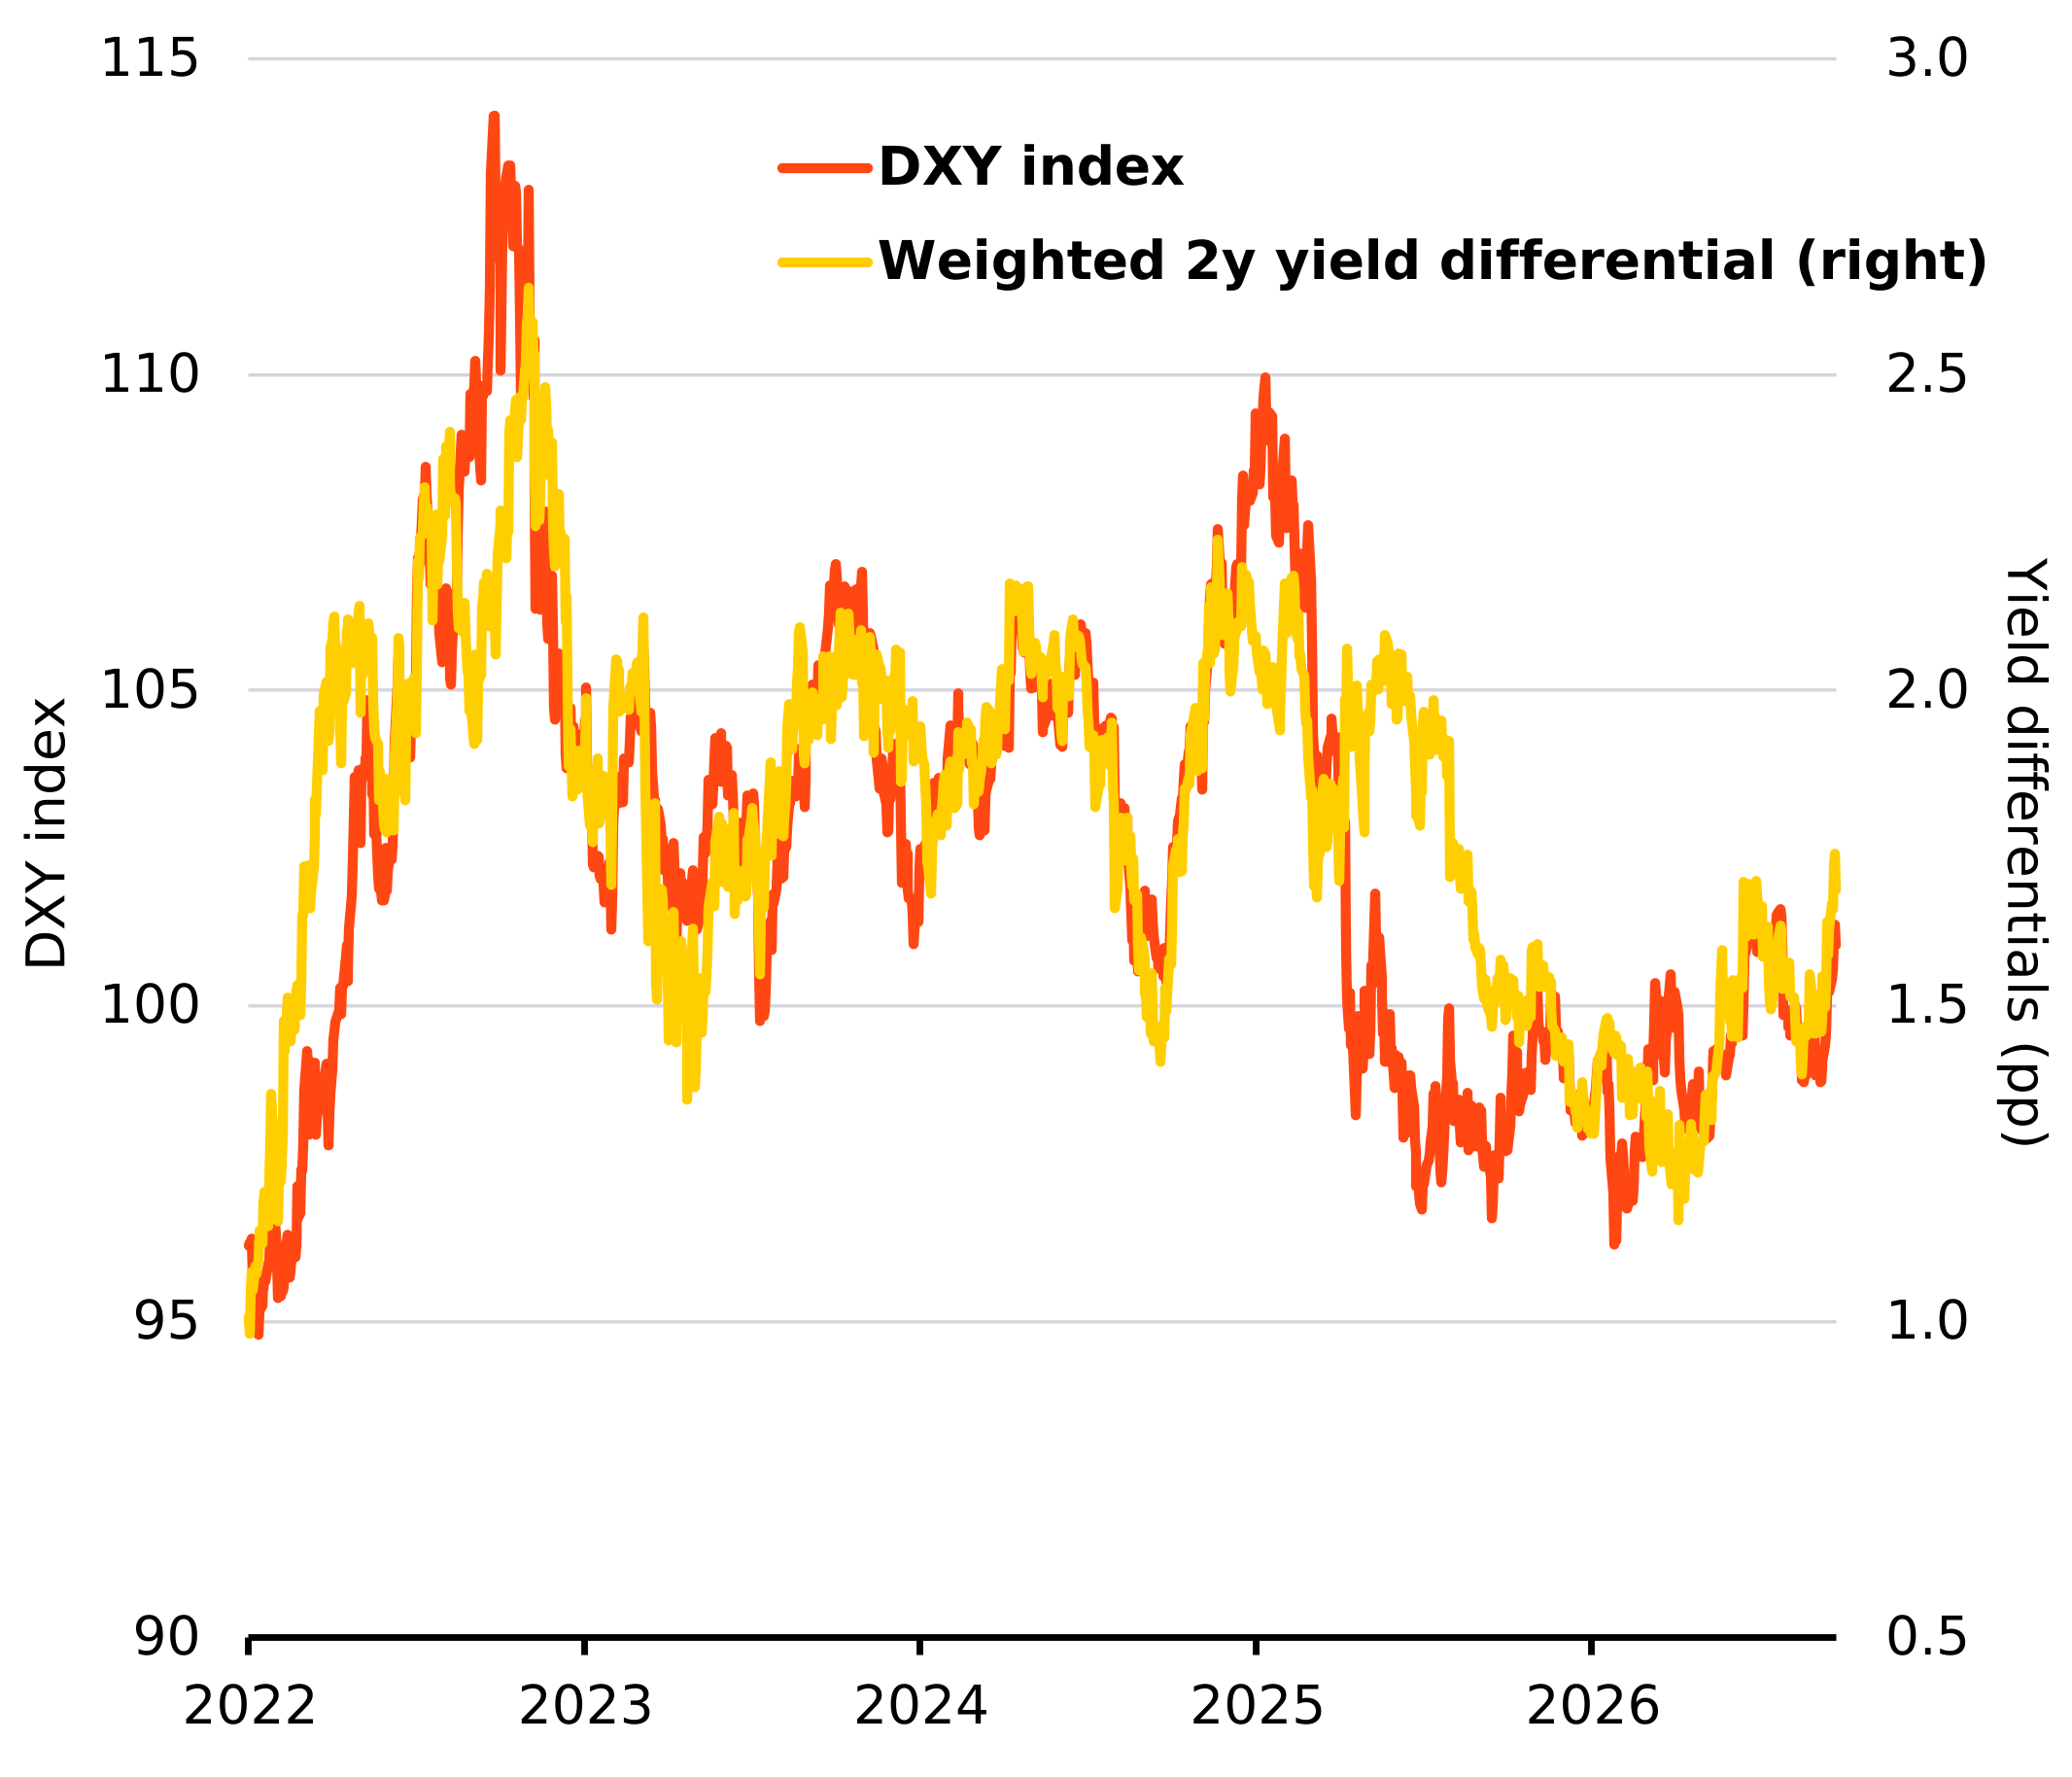
Source: BlackRock Investment Institute, with data from LSEG Datastream, October 2026. Notes: The orange line shows the U.S. Dollar Index (DXY). The yellow line shows the trade-weighted average U.S. two-year yield differential versus Germany, Japan, the UK, Canada, Sweden and Switzerland (right axis), using DXY currency weights. Yield differentials are shown in percentage points.
The dollar’s journey over the past 18 months has been telling. It fell sharply after President Donald Trump’s “Liberation Day” tariff announcements fueled warnings about dollar debasement, stabilized, then weakened again this summer amid Fed credibility concerns. It has since rebounded as Fed rate expectations swung dramatically – from as many as two cuts this year to one hike already delivered and more tightening priced. The dollar has closely tracked the resulting shift in two-year yield differentials. See the chart. The DXY has now retraced most of its post-April 2 tariff decline. That supports our pushback last year against the dollar debasement narrative. Yet we don’t expect a sustained appreciation cycle. Even with Fed repricing, strong U.S. growth and robust equity inflows, our analysis suggests the dollar is stronger than these and other fundamental drivers imply. The bar for further gains is high.
Start with the Fed rate path. The dramatic repricing has provided a powerful boost to the dollar and dollar assets this year. Markets have gone from pricing cuts at the start of the year to pricing roughly four more hikes over the next 12 months, on top of last month’s rate increase. We think that is too much. Last week’s weaker-than-expected jobs report highlights a macro backdrop that remains fluid. If expectations for further Fed tightening are pared back, the yield differentials that have helped drive the dollar’s rebound could narrow and weigh on the currency. A weaker dollar would reinforce our broader risk-on stance and create a more supportive backdrop for our EM equity overweight.
Other fundamental drivers
Next come capital flows. Strong U.S. growth, corporate earnings and AI investment have helped U.S. equities outperform since the start of the war in Iran, drawing global capital into dollar assets. Foreign investors poured nearly $1 trillion into U.S. equities and investment fund shares in the 12 months to July, including a record $426 billion in the second quarter alone, according to the Bureau of Economic Analysis. We expect that support to persist as earnings growth stays robust. U.S. equity outperformance should provide a partial offset if Fed repricing narrows yield differentials and weighs on the dollar.
Our analysis also captures traditional drivers, including risk sentiment and term premium. The latter has eased slightly after briefly rising this summer, as the Fed’s September hike helped restore central bank credibility. On balance, we see little room for another sustained dollar upswing. Instead, we see the currency staying around current levels, if not somewhat weaker. That is hard to square with the structural debasement narrative that started emerging last year: if investors were losing confidence in the dollar’s long-term role, we would expect a bigger deviation from the dollar’s fundamental drivers. That doesn’t mean the risks have disappeared. The fiscal backdrop remains challenging, with a $1.9 trillion deficit and public debt near 101% of GDP. While not a driver of the dollar today, these risks could return to the fore.
Our bottom line
The dollar’s resilience shows its moves are still largely explained by fundamental drivers rather than concerns about its long-term role. A stable or moderately weaker dollar would also reinforce our EM equity overweight.
Market backdrop
The global bond selloff deepened last week, with U.S. 10-year Treasury yields climbing to 5.34%, their highest level since 2002. A softer-than-expected jobs report added to the volatility as investor expectations for Fed tightening whipsawed. We see a consistent story: shifts in Fed expectations can influence rate moves in the near term, but they do not alter the structural forces driving long-term yields, including the intensifying competition for capital we have long described.
We look to September FOMC meeting minutes in a light macroeconomic data week. After the Fed raised interest rates for the first time in three years, we’re keen to see how hawkish the discussion surrounding the decision was among committee members. We also eye preliminary consumer sentiment data from the University of Michigan, after the index fell to its second-lowest reading ever at the end of September.
Week ahead
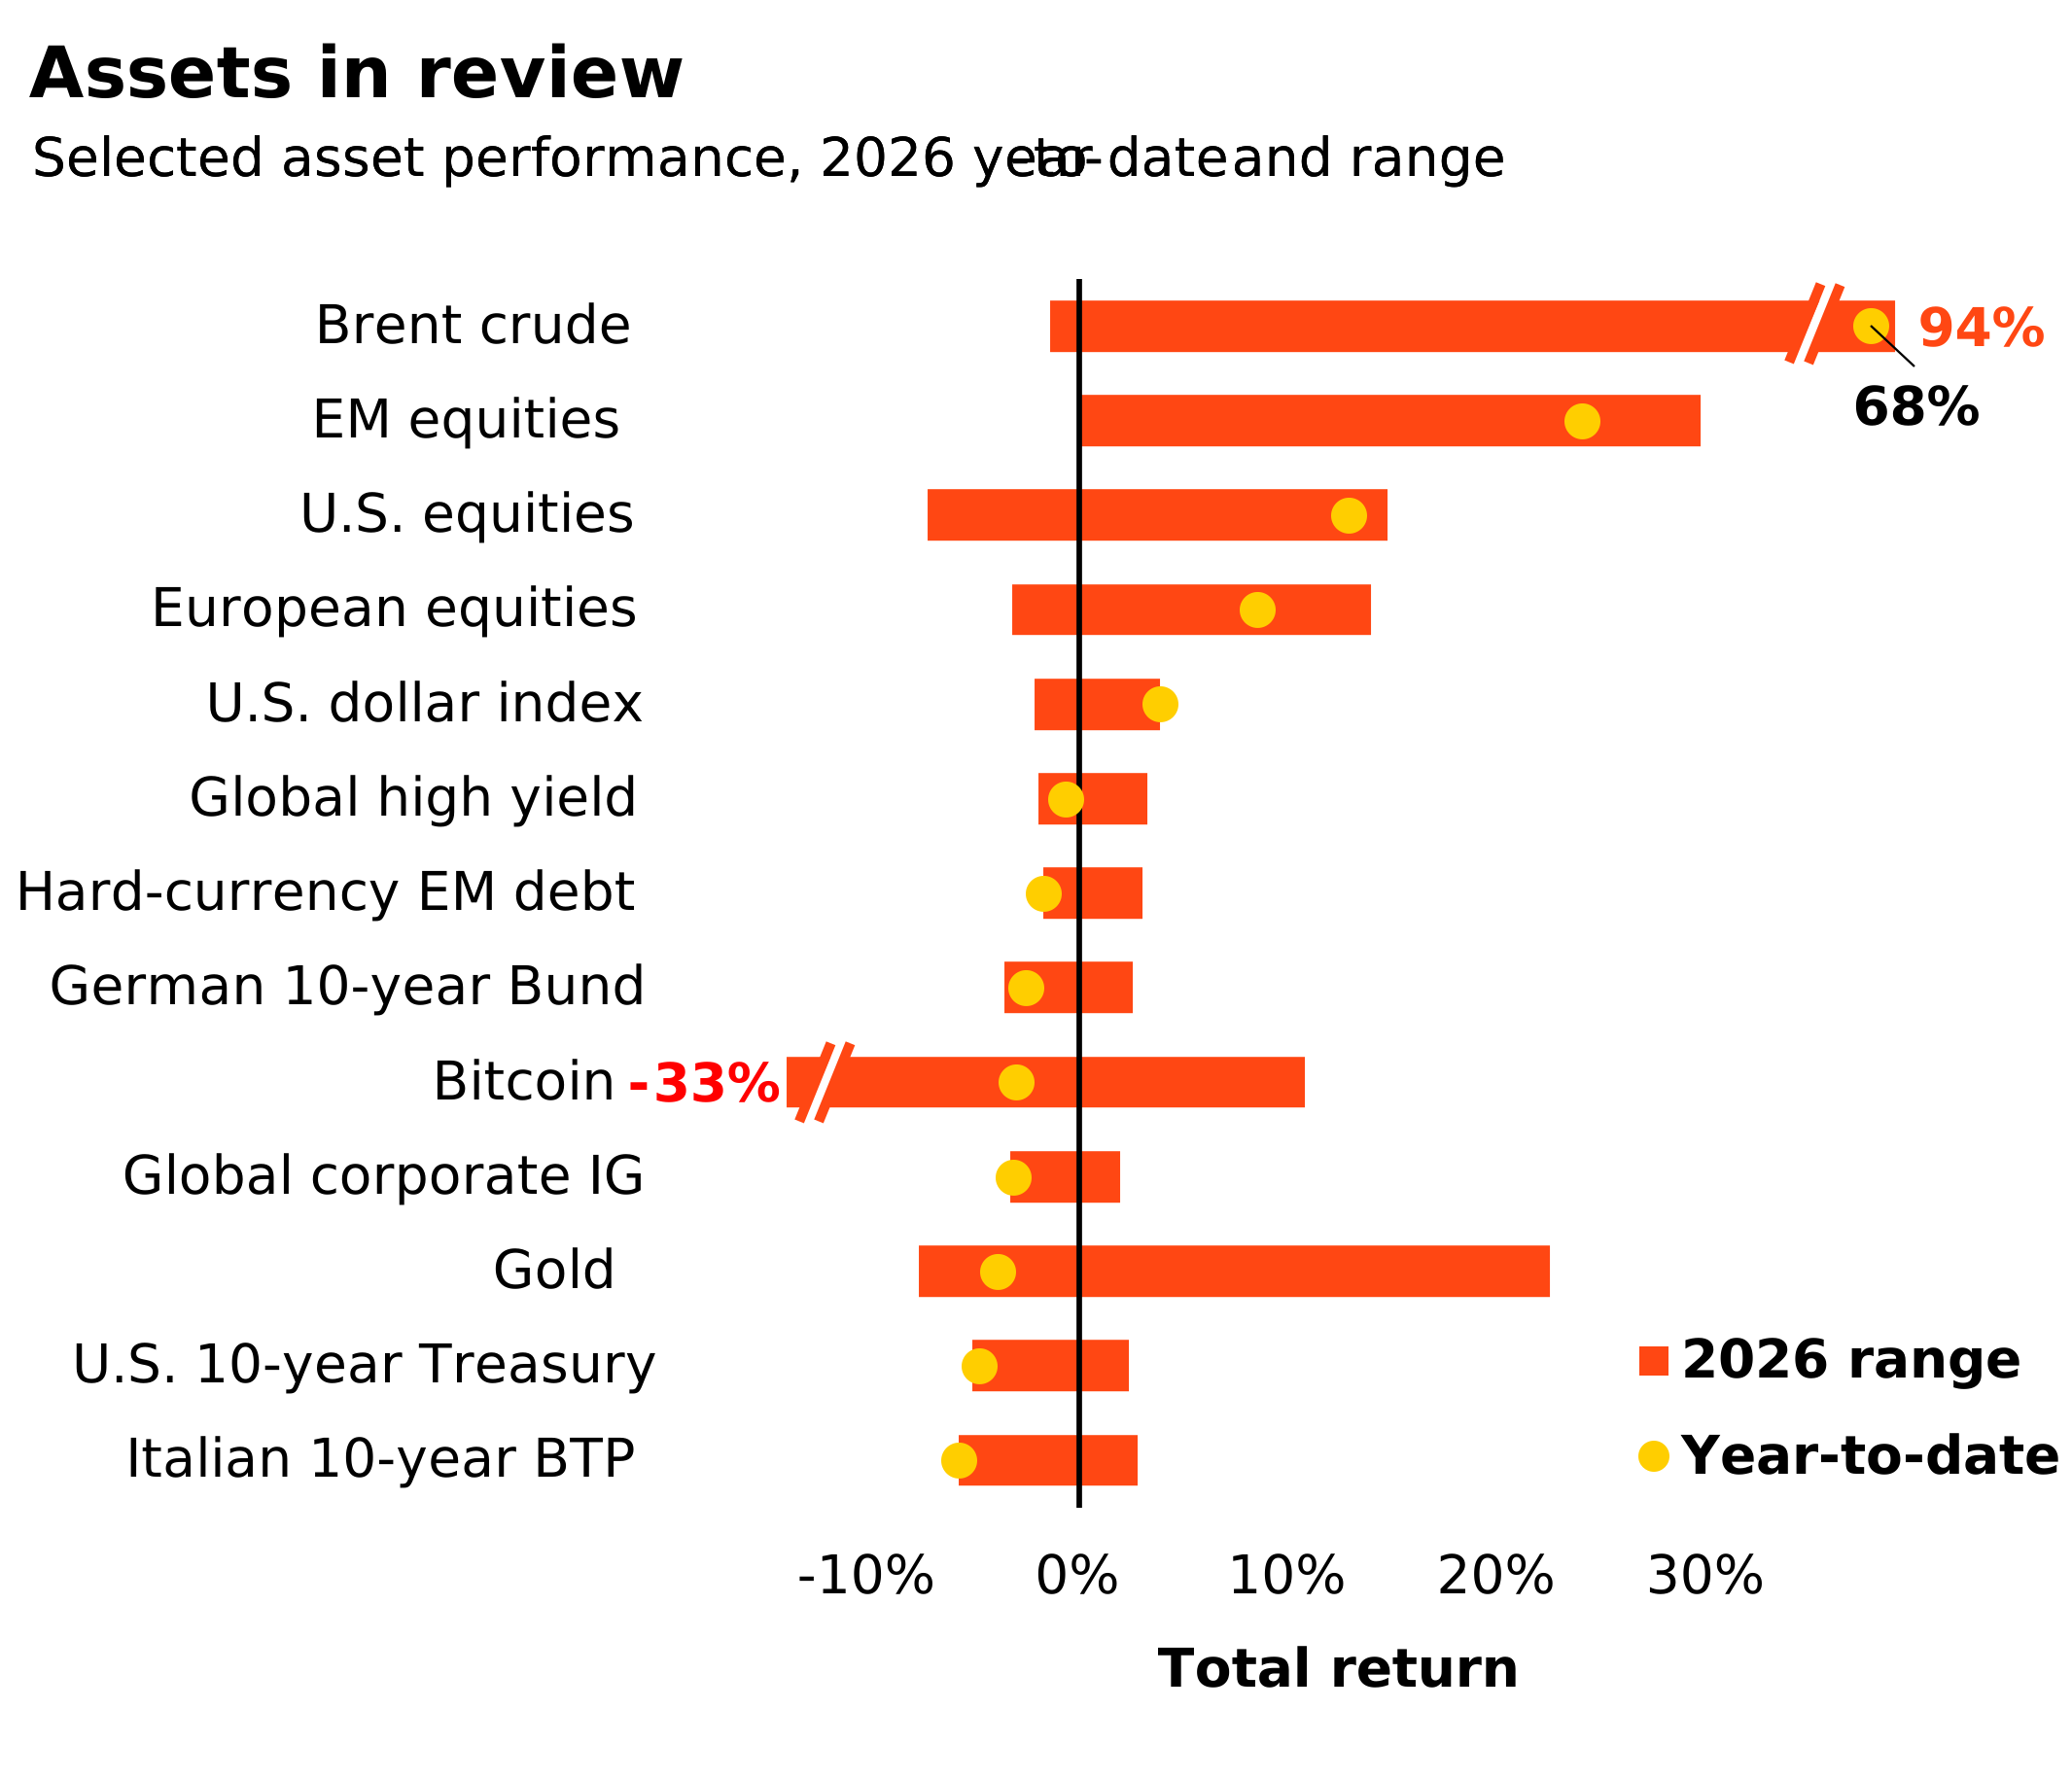
Past performance is not a reliable indicator of current or future results. Indexes are unmanaged and do not account for fees. It is not possible to invest directly in an index. Sources: BlackRock Investment Institute, with data from LSEG Datastream as of October 1, 2026. Notes: The two ends of the bars show the lowest and highest res at any point year to date, and the dots represent current year-to-date res. Emerging market (EM), high yield and global corporate investment grade (IG) res are denominated in U.S. dollars, and the rest in local currencies. Indexes or prices used are: spot Brent crude, ICE U.S. Dollar Index (DXY), spot gold, spot bitcoin, MSCI Emerging Markets Index, MSCI Europe Index, LSEG Datastream 10-year benchmark government bond index (U.S., Germany and Italy), Bloomberg Global High Yield Index, J.P. Morgan EMBI Index, Bloomberg Global Corporate Index and MSCI USA Index.
Oct. 5
Global composite/services PMI final
Oct. 6
U.S. international trade; EU & UK construction PMI
Oct. 7
FOMC minutes
Oct. 9
UMich preliminary consumer sentiment
Intersecting mega forces
Since we launched our mega forces framework it has become clearer how their intersection shapes almost all our investment views and opens up alpha opportunities. They cut across asset class labels, spurring a rethink of portfolio construction. Investors need to be deliberate about the economic or thematic exposures they own, the vehicles they use to implement them and their investment horizons.

From drivers to portfolio expressions
Our highest conviction views, October 2026
| Driver | What we think | Portfolio expression |
|---|---|---|
| Growth and AI scarcity | The AI buildout is speeding up, making bottlenecks binding. | Overweight U.S. and EM equities; focus on AI bottleneck opportunities: power, chips and data centers. |
| Duration and diversification | Long bonds carry high rate sensitivity and are less reliable diversifiers. | Prefer short- and medium-term government bonds over long bonds for income. |
| Credit spreads and liquidity | Selectivity is crucial amid tight spreads and uneven fundamentals. | Credit with clear cash flows, lender protections and recovery value; higher-rated high yield. |
| Inflation and scarcity | Scarcity, secure supply and power demand carry inflation risks. | Infrastructure, energy bottlenecks, EM local debt and real-asset-linked exposures. |
| Alpha opportunity | Macro outcomes matter again in the new regime. | Macro hedge funds, venture capital, market-neutral strategies, and selected private credit and non-U.S. alpha. |
Note: Views are from a U.S. dollar perspective, October 2026. This material represents an assessment of the market environment at a specific time and is not intended to be a forecast of future events or a guarantee of future results. This information should not be relied upon by the reader as research or investment advice regarding any particular funds, strategy or security.
Asset class implications
Six- to 12-month tactical positioning, October 2026
This shows the implementation of our key investment views from the previous page through an asset class lens.

| Asset | Tactical view | Commentary | ||||
|---|---|---|---|---|---|---|
| Equities | ||||||
| United States |  |
We are overweight. Strong corporate earnings, fueled by the AI buildout and a favorable macro backdrop, are outpacing higher interest rate expectations. | ||||
| Europe |  |
We are neutral. We would need to see more business-friendly policy and deeper capital markets for Europe to outperform. We favor financials, infrastructure, and industrials. | ||||
| UK | |
We are neutral. Valuations remain attractive relative to the U.S., but we see few near-term catalysts to trigger a shift. | ||||
| Japan | |
We are neutral. Strong corporate balance sheets and governance reforms remain supportive. We prefer targeted exposures to physical AI and the buildout’s bottlenecks. | ||||
| Emerging markets (EM) |  |
We are overweight. Strong earnings and cheaper valuations create opportunities. We particularly like different expressions of the AI scarcity theme across Asia and Latin America. | ||||
| China | |
We are neutral. We see opportunities in physical AI. Cheap, open-source AI could drive adoption, but that doesn’t necessarily translate into AI-provider profitability. | ||||
| Fixed income | ||||||
| Short U.S. Treasuries | |
We are neutral. We prefer short- and medium-term Treasuries, given the attractive risk-adjusted income on offer. | ||||
| Long U.S. Treasuries |  |
We are underweight. We see investors wanting more compensation for holding long-term bonds amid persistent inflation and high debt loads. Long-duration bonds also are a less reliable portfolio diversifier in the new regime. | ||||
| Global inflation-linked bonds | |
We are neutral. We see inflation settling above pre-pandemic levels, but markets may not price this in the near term as economic growth could slow. | ||||
| Euro area government bonds |  |
We are neutral short- and medium-term bonds. Current ECB rate pricing looks fairly valued given the balance of risks. Higher energy prices could push rates higher. We prefer to deploy risk elsewhere. | ||||
| UK gilts | |
We are neutral. We expect periods of elevated volatility given political uncertainty, longer-term bonds making up a larger market share, and buyers becoming more price-sensitive. | ||||
| Japanese government bonds |  |
We are underweight. Rate hikes, higher global term premium and heavy bond issuance will likely drive yields up further. | ||||
| China government bonds | |
We are neutral. China bonds offer stability and diversification but developed market yields are higher. A shift in investor sentiment toward equities limits upside. | ||||
| U.S. agency MBS | |
We are overweight. Agency MBS offer higher income than Treasuries with similar risk and may offer more diversification amid fiscal and inflationary pressures. | ||||
| Short-term IG credit | |
We are neutral. Spreads are tight due to corporate strength; they could widen if issuance increases or risk appetite shifts. | ||||
| Long-term IG credit | |
We are underweight. We prefer short-term bonds less exposed to interest rate risk over long-term bonds. | ||||
| Global high yield | |
We are neutral. High yield offers attractive income. We prefer higher-rated U.S. and European high yield over investment grade and see dispersion of returns increasing. | ||||
| Asia credit | |
We are neutral. Overall yields are attractive and fundamentals are solid, but spreads are tight. | ||||
| Emerging hard currency | |
We are neutral. Fundamentals have improved, but we see a more attractive risk-reward profile in EM local debt. | ||||
| Emerging local currency | |
We are overweight. We like the yield relative to its volatility and improving fundamentals. | ||||
Past performance is not a reliable indicator of current or future results. It is not possible to invest directly in an index. Note: Views are from a U.S. dollar perspective. This material represents an assessment of the market environment at a specific time and is not intended to be a forecast or guarantee of future results. This information should not be relied upon as investment advice regarding any particular fund, strategy or security.

Jean Boivin
Head – BlackRock Investment Institute

Wei Li
Global Chief Investment Strategist – BlackRock

Roelof Salomons
Chief Investment Strategist for the Netherlands and the Nordics – BlackRock Investment Institute

Michel Dilmanian
Portfolio Strategist – BlackRock Investment Institute
