China: up the value chain
Market take
Weekly video_20260928
Serena Jiang
Economist
BlackRock Investment Institute
SCRIPT
Camera frame
Title slide: China: up the value chain
China is increasingly competing on quality in advanced manufacturing – not just scale. In our latest China research, we argue cheaper Chinese technology can lower costs for users while pressuring competitors’ margins and market share.
1: Moving up the value chain
China’s move up the manufacturing value chain has global implications. Its long-held focus on cheap, labor-intensive exports has evolved. Today, China is gaining market share in cutting-edge industries like EVs, batteries, advanced machinery and AI.
And there’s a key nuance underscoring this shift. While what China sells has moved decidedly upmarket, it’s relying more on its own supply chains.
2: Intensifying competition
The result is greater competition for producers, even as low-cost Chinese technology benefits the end user. Outside of China, the important question is whether companies rely on Chinese technology, or compete against it. For example, cheaper Chinese robots can boost productivity, but they also put pressure on rivals.
And China is moving from customer to competitor. Just last year, Beijing overtook Germany as the world's largest machine-tool exporter.
We see a similar divide in AI, where cheaper Chinese models could accelerate adoption commoditizing the model markets.
3: Scale doesn’t equal returns
Whether growth can translate into profits and shareholder returns inside China is an open question. China's industrial policies have built globally competitive companies, but market share gains don't always lead to stronger earnings.
AI-related industries are benefiting, while intense competition is squeezing profits elsewhere. Industrial strength, in other words, doesn't guarantee investment returns.
Outro: Here’s our Market take
China's move up the industrial value chain is reshaping global competition. We’re neutral Chinese equities and stay focused on the areas where growth is translating into strong returns, including around physical AI.
Closing frame: Read details: blackrock.com/weekly-commentary
China is increasingly competing on quality – not just scale – in advanced manufacturing. We see uneven effects for companies and investors globally.
Global government bond yields soared to multi-decade highs last week. Market expectations for further Fed tightening may be overstated, in our view.
We look to September US payrolls and PCE for signs that slower labor supply is keeping wage pressures – and ultimately inflation – elevated.
AI was a key topic when President Donald Trump met Chinese President Xi Jinping last week, underscoring China’s move up the manufacturing value chain into advanced technologies. In our latest China research, we argue cheaper Chinese technology can lower costs for users while pressuring competitors' margins and market share. But trade and technology tensions can cloud profits and market access. We stay neutral Chinese equities but see opportunities in physical AI.
Leaning outward
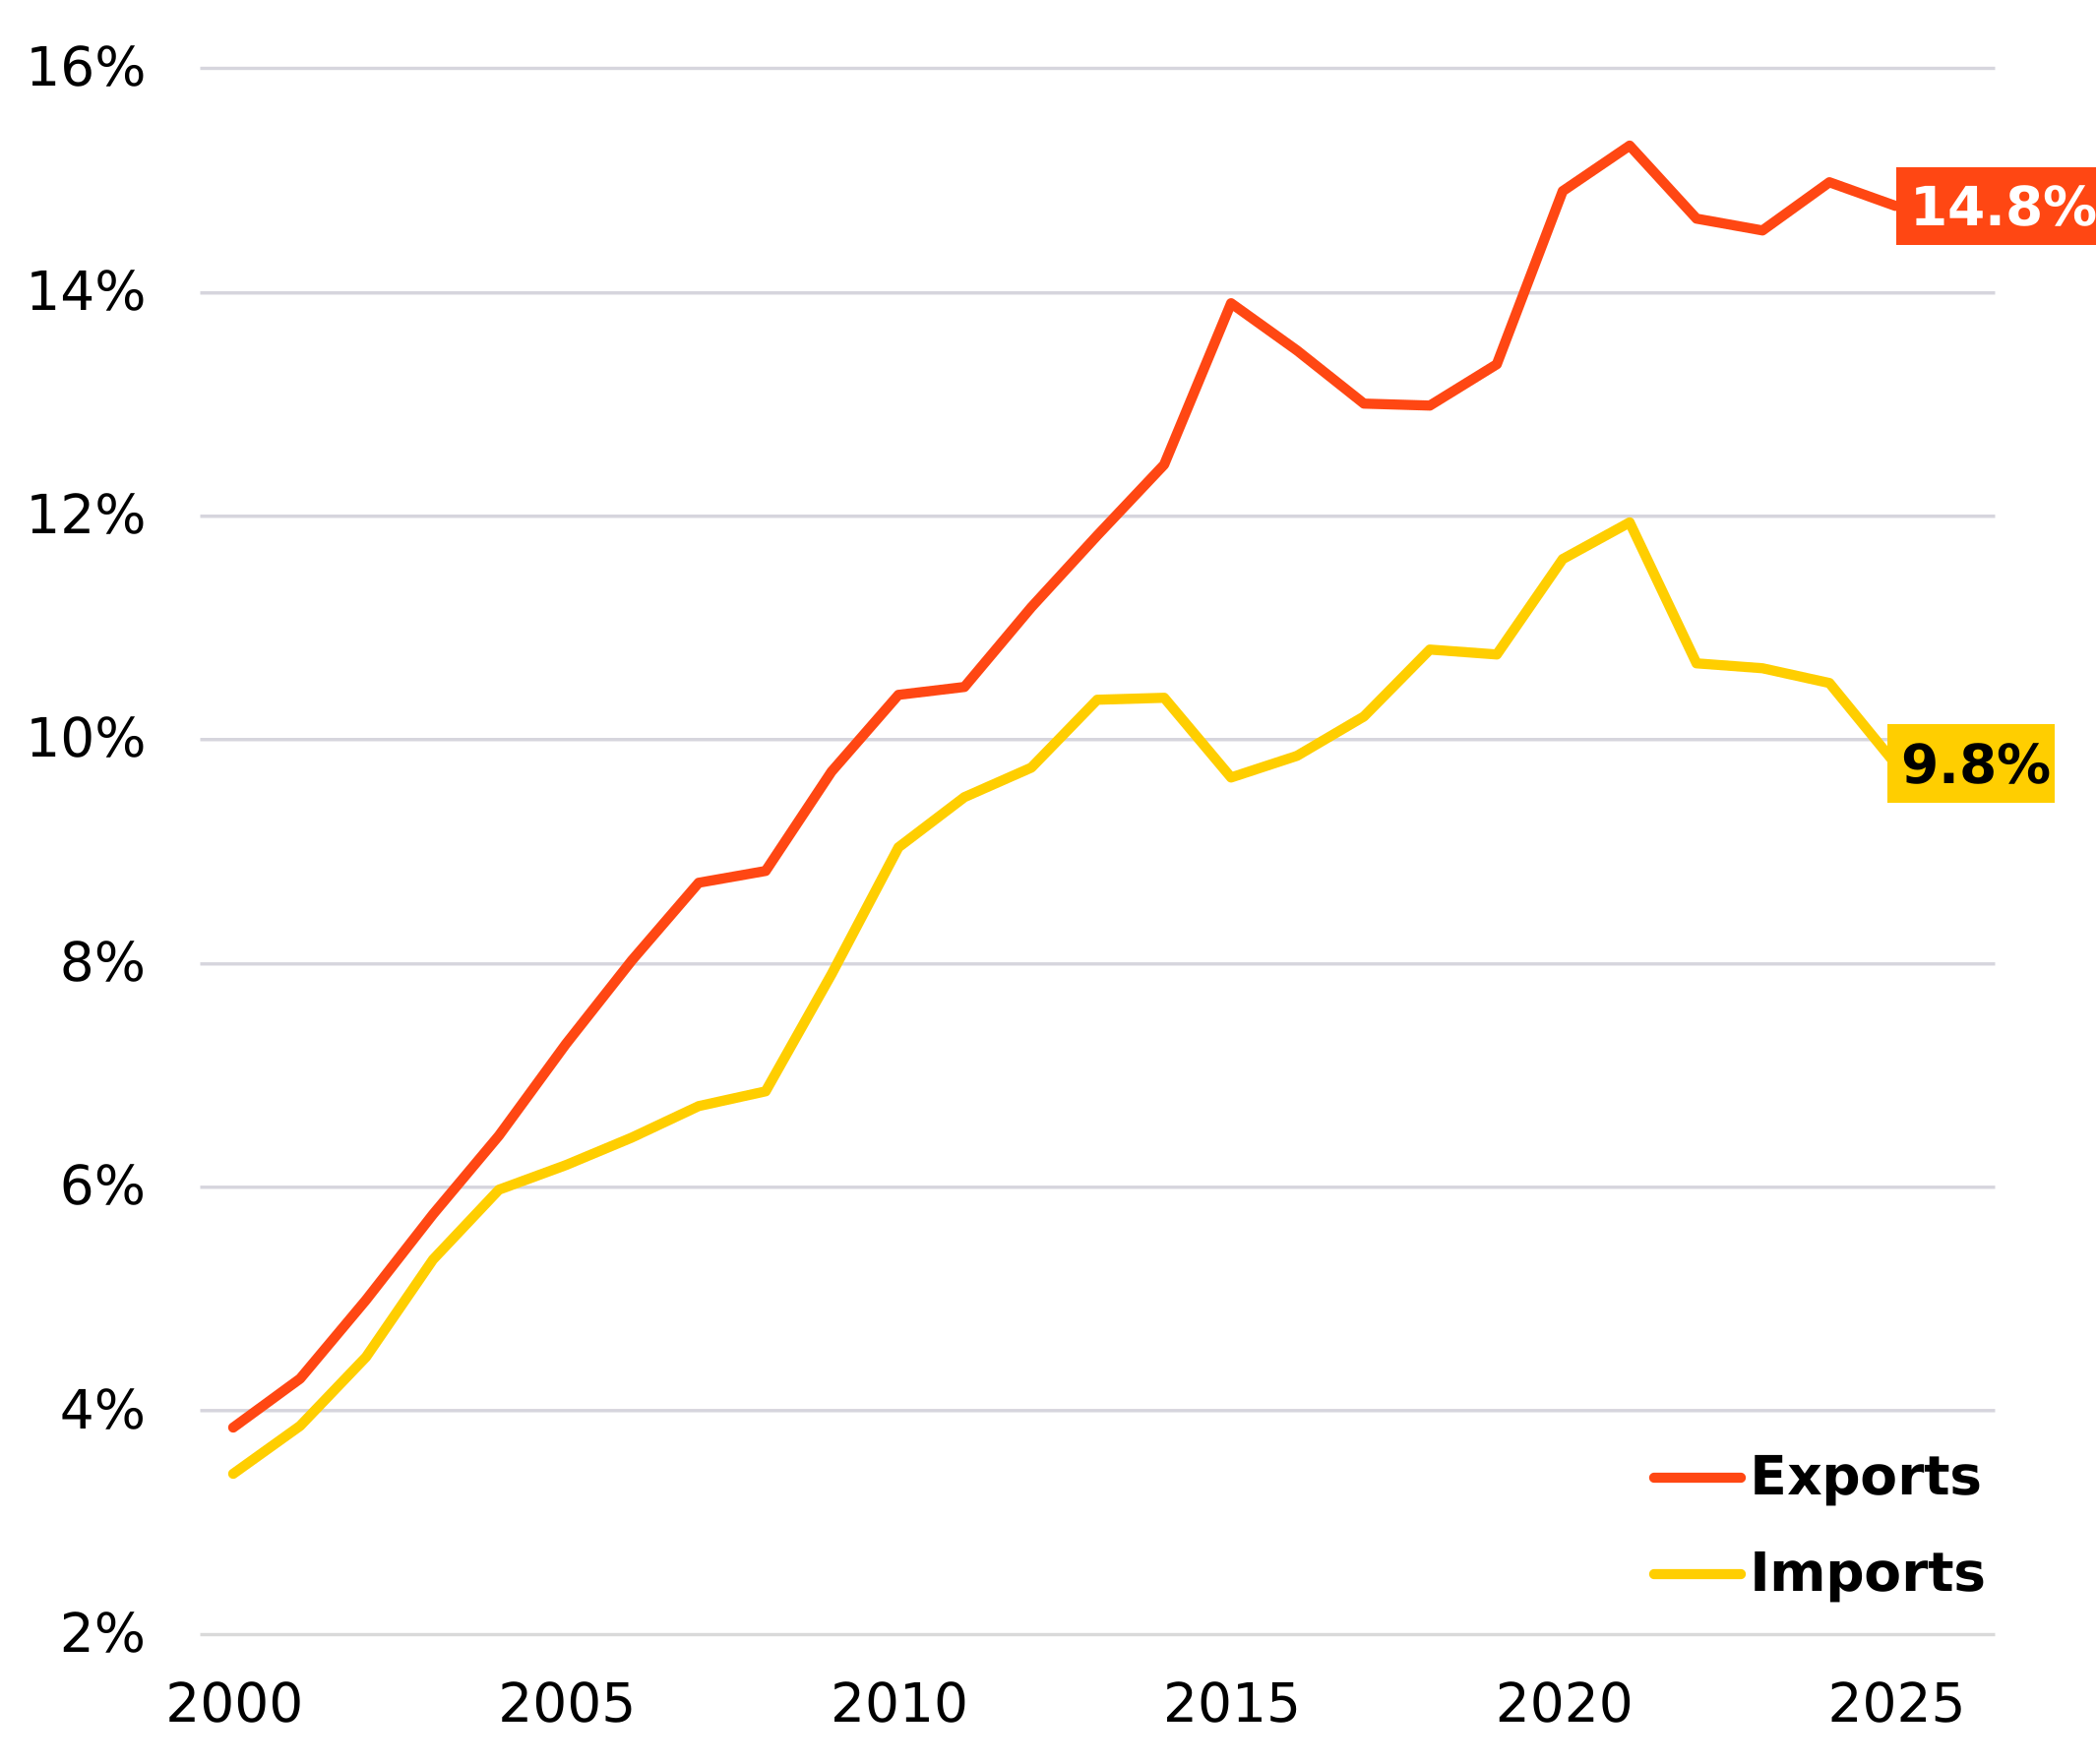
China’s share of global merchandise trade, 2000–25
Source: IMF Direction of Trade Statistics (DOTS) via LSEG Datastream, September 2026. Notes: Lines show China’s exports to and imports from the world as a share of total global exports and imports, respectively. Exports are measured free on board (FOB); imports are measured cost, insurance and freight (CIF).
China’s climb up the manufacturing value chain is reshaping industries and global profit pools. China’s 2001 entry into the World Trade Organization unleashed what some academics called the “China shock”: cheap, labor-intensive exports soared, but so did imports as China became embedded in global supply chains. Made in China 2.0 looks different. State support has helped China rapidly gain market share in cutting edge industries like EVs, advanced machinery and AI, backed increasingly by its own supply chains. This means while China’s share of global exports has stayed steady, what it sells has moved decidedly upmarket. At the same time, its import share has fallen from its 2021 peak as domestic demand trails production. See the chart. The result is greater competition for producers globally, even as lower-cost Chinese technology benefits end users.
Outside China, the key question is whether companies use Chinese technology or compete against it. Cheaper Chinese industrial robots and machinery can boost productivity and ease labor shortages for their customers. For rival producers, the economics are less appealing. European machinery makers illustrate the squeeze. China has moved from a major buyer of advanced machinery to a formidable competitor at home and abroad. In 2025, it overtook Germany as the world’s largest machine-tool exporter for the first time.
AI creates a similar divide
AI creates a similar divide. Cheaper Chinese models could accelerate AI adoption while commoditizing the model market. That could shift value toward the physical infrastructure needed to support greater AI use - computing power, data centers and electricity - reinforcing the scarcity investment theme from our Midyear Global Outlook. Physical AI could amplify demand for power electronics and batteries while broadening demand for components like motors and actuators – areas where China already has a manufacturing and supply-chain advantage. But technology sovereignty cuts both ways: export controls and efforts to reduce reliance on Chinese technology could limit market access. That makes geopolitics a key risk to where the opportunity ultimately lies.
Inside China, industrial policy has helped build scale and competitiveness, but growth alone does not guarantee shareholder returns. Long-standing challenges – including weak domestic consumption, a soft property market and an aging population – remain, while intense competition can squeeze margins even in industries where China has gained global market shares. The divergence is stark: profits at Chinese electronic-device makers rose 110% year over year in the first seven months of 2026, supported by global AI demand, while auto profits fell 20.4%, according to data from the National Bureau of Statistics of China. Likewise, AI hardware suppliers have expanded margins, while solar manufacturers have seen theirs collapse. Markets echo that divide: the MSCI China index has lost 11% in US dollar terms this year through Sept. 21, while the MSCI China Information Technology index has gained 7%.
Our bottom line
This divide reinforces our selective approach: we stay neutral Chinese equities while favoring areas where growth is translating into stronger margins and returns – particularly in AI hardware and select advanced manufacturing.
Market backdrop
The global bond selloff accelerated last week, pushing long-dated US Treasury yields to their highest levels in over 20 years. The 30-year yield reached 5.53%, a level last seen in 2004, while the 10-year rose to a 19-year high of 5.22% on expectations for further rate hikes. We think markets may be getting ahead of themselves. A hike that strengthens Fed credibility, against a backdrop of stronger growth, is in our view on net good news for risk assets.
US payrolls and inflation are in focus. Slower labor supply growth means softer job gains need not signal a weaker economy, in our view. We expect hiring around levels consistent with full employment – enough to keep wage pressures elevated and risk keeping inflation sticky. September PCE will show whether that pressure is feeding through, with core inflation still running above 3%.
Week ahead
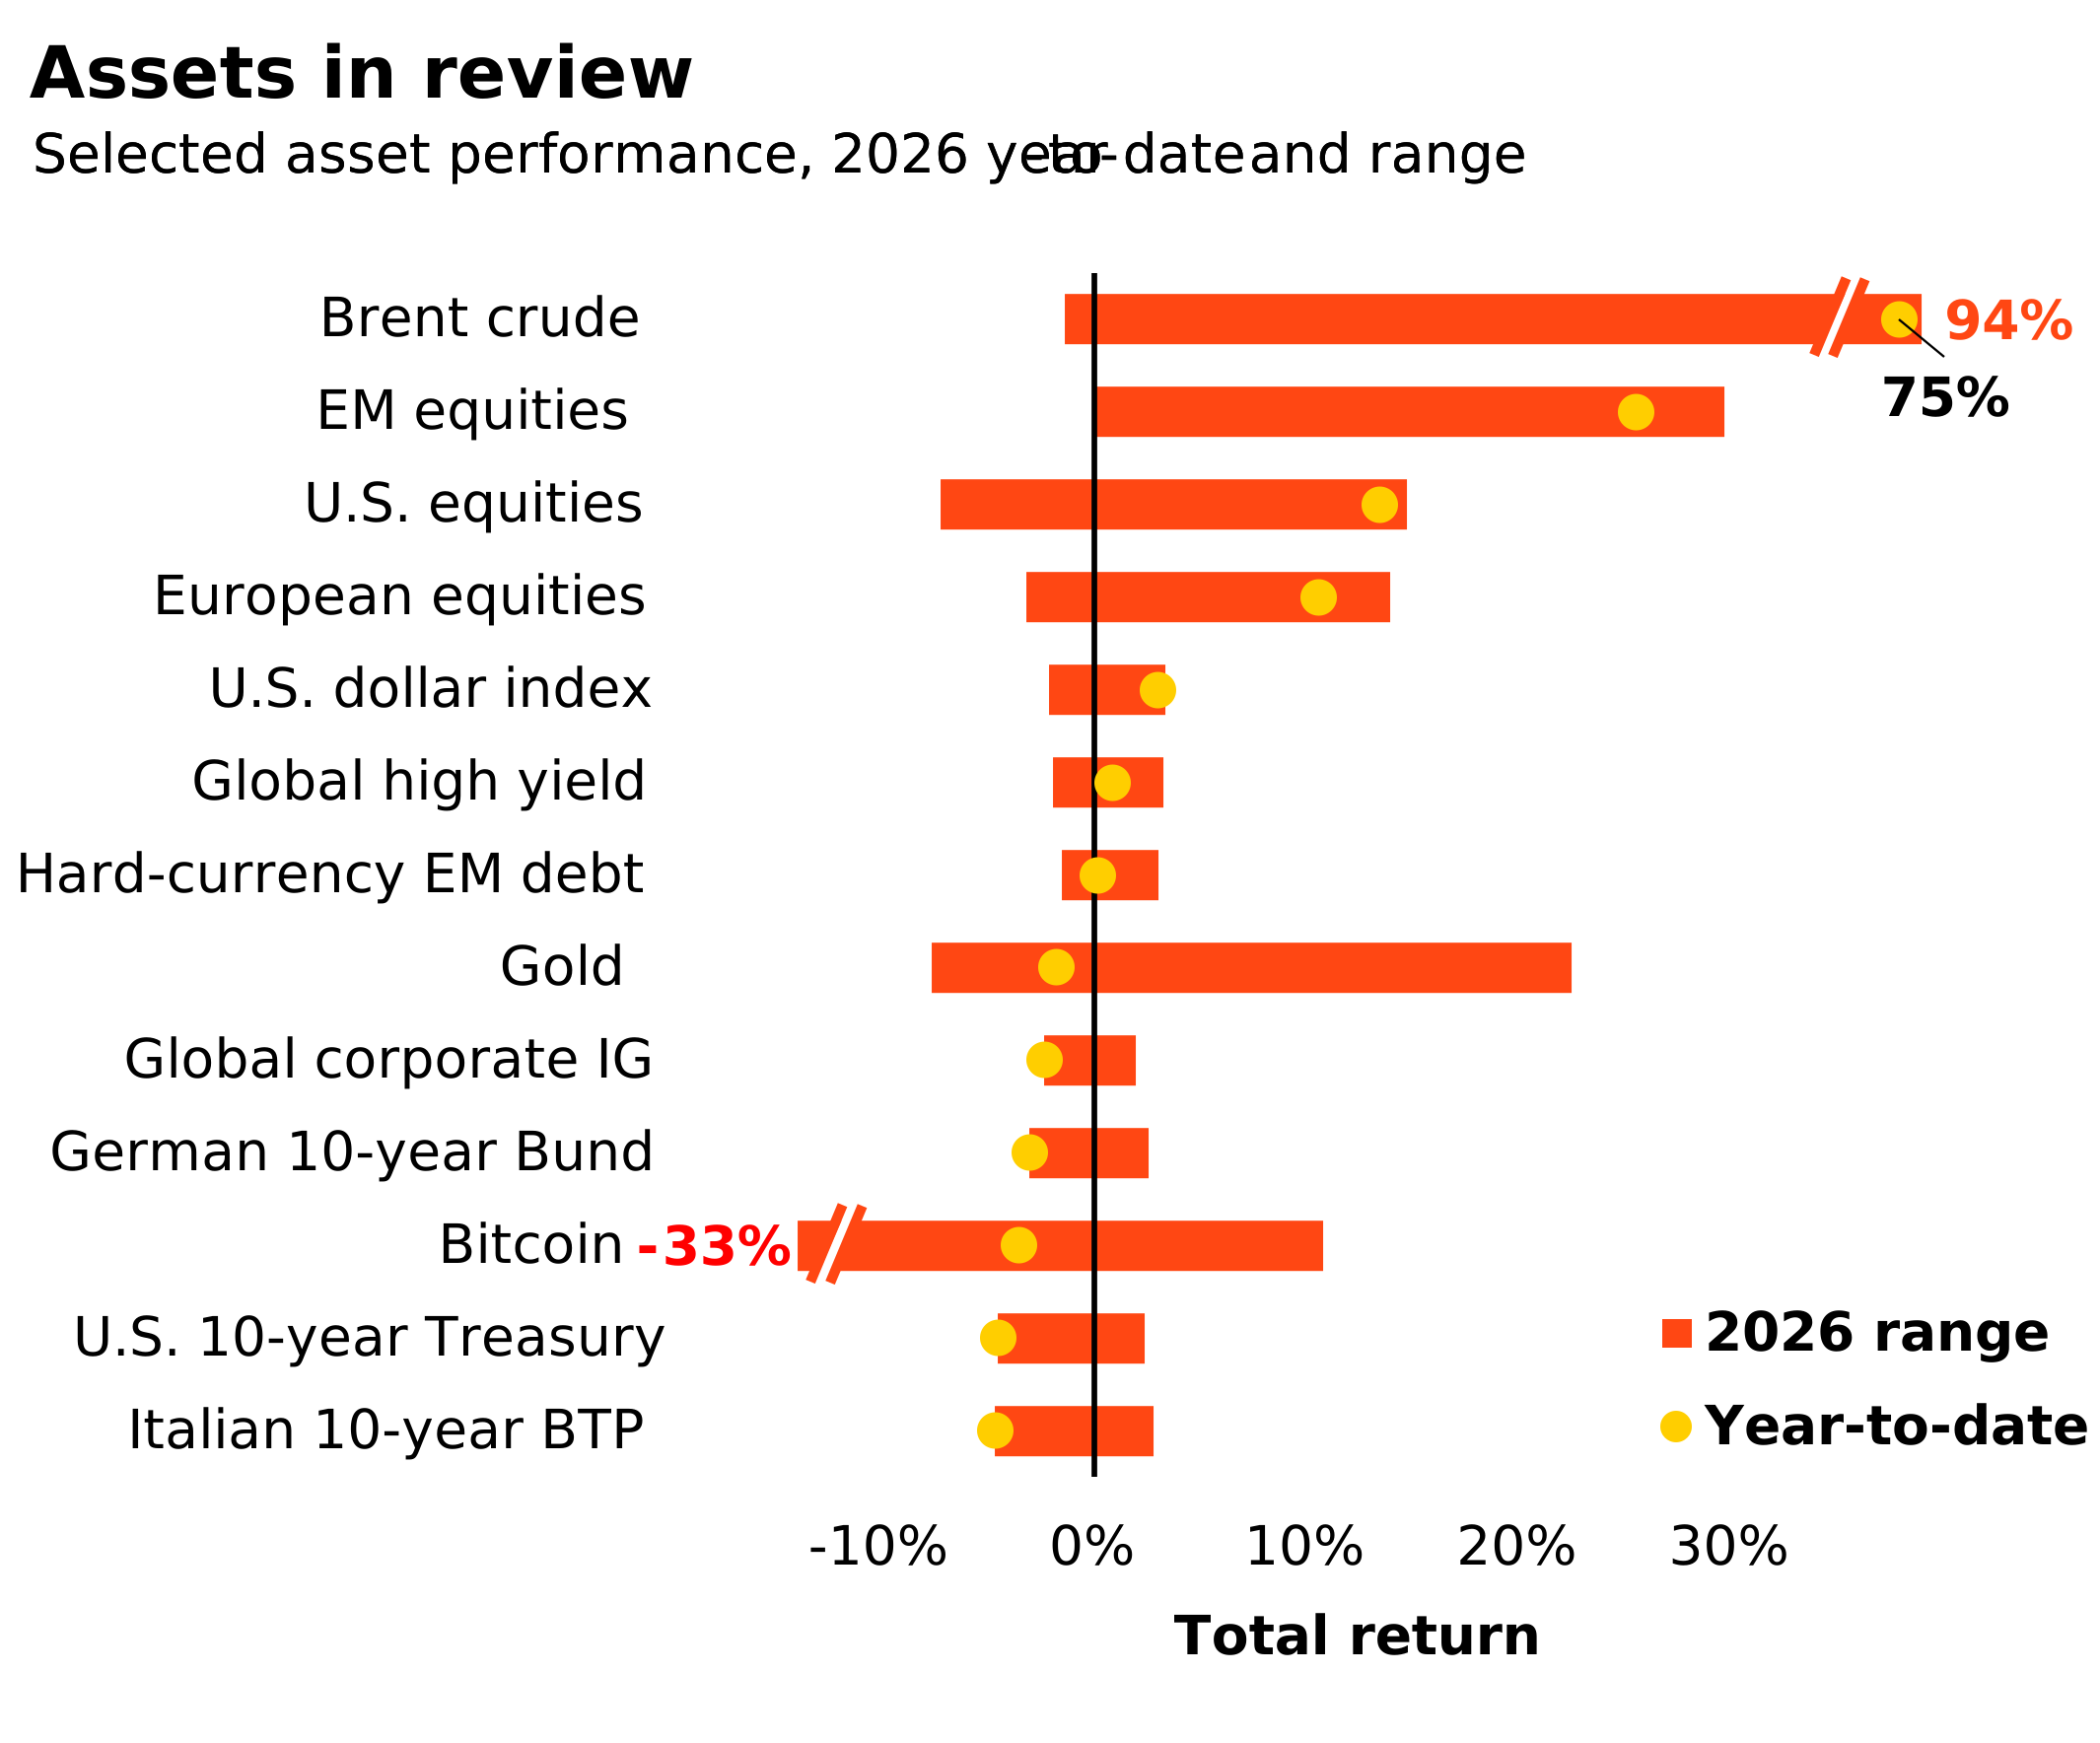
Past performance is not a reliable indicator of current or future results. Indexes are unmanaged and do not account for fees. It is not possible to invest directly in an index. Sources: BlackRock Investment Institute, with data from LSEG Datastream as of September 24, 2026. Notes: The two ends of the bars show the lowest and highest res at any point year to date, and the dots represent current year-to-date res. Emerging market (EM), high yield and global corporate investment grade (IG) res are denominated in US dollars, and the rest in local currencies. Indexes or prices used are: spot Brent crude, ICE US Dollar Index (DXY), spot gold, spot bitcoin, MSCI Emerging Markets Index, MSCI Europe Index, LSEG Datastream 10-year benchmark government bond index (US, Germany and Italy), Bloomberg Global High Yield Index, J.P. Morgan EMBI Index, Bloomberg Global Corporate Index and MSCI USA Index.
US job openings; US & EU consumer confidence final
US PCE; UK GDP; China manufacturing PMI
Global PMI final; EU unemployment
US nonfarm payrolls; Japan unemployment, EU flash HICP
Read our past weekly commentaries here.
Intersecting mega forces
Since we launched our mega forces framework it has become clearer how their intersection shapes almost all our investment views and opens up alpha opportunities. They cut across asset class labels, spurring a rethink of portfolio construction. Investors need to be deliberate about the economic or thematic exposures they own, the vehicles they use to implement them and their investment horizons.

From drivers to portfolio expressions
Our highest conviction views, September 2026
| Driver | What we think | Portfolio expression |
|---|---|---|
| Growth and AI scarcity | The AI buildout is speeding up, making bottlenecks binding. | Overweight US and EM equities; focus on AI bottleneck opportunities: power, chips and data centers. |
| Duration and diversification | Long bonds carry high rate sensitivity and are less reliable diversifiers. | Prefer short- and medium-term government bonds over long bonds for income. |
| Credit spreads and liquidity | Selectivity is crucial amid tight spreads and uneven fundamentals. | Credit with clear cash flows, lender protections and recovery value; higher-rated high yield. |
| Inflation and scarcity | Scarcity, secure supply and power demand carry inflation risks. | Infrastructure, energy bottlenecks, EM local debt and real-asset-linked exposures. |
| Alpha opportunity | Macro outcomes matter again in the new regime. | Macro hedge funds, venture capital, market-neutral strategies, and selected private credit and non-US alpha. |
Note: Views are from a US dollar perspective, September 2026. This material represents an assessment of the market environment at a specific time and is not intended to be a forecast of future events or a guarantee of future results. This information should not be relied upon by the reader as research or investment advice regarding any particular funds, strategy or security.
Asset class implications
Six- to 12-month tactical positioning, September 2026
This shows the implementation of our key investment views from the previous page through an asset class lens.

| Asset | Tactical view | Commentary | ||||
|---|---|---|---|---|---|---|
| Equities | ||||||
| United States | We are overweight. Strong corporate earnings, fueled by the AI buildout and a favorable macro backdrop, are outpacing higher interest rate expectations. | |||||
| Europe | We are neutral. We would need to see more business-friendly policy and deeper capital markets for Europe to outperform. We favor financials, infrastructure, and industrials. | |||||
| UK | We are neutral. Valuations remain attractive relative to the US, but we see few near-term catalysts to trigger a shift. | |||||
| Japan | We are neutral. Strong corporate balance sheets and governance reforms remain supportive. We prefer targeted exposures to physical AI and the buildout’s bottlenecks. | |||||
| Emerging markets (EM) | We are overweight. Strong earnings and cheaper valuations create opportunities. We particularly like different expressions of the AI scarcity theme across Asia and Latin America. | |||||
| China | We are neutral. We see opportunities in physical AI. Cheap, open-source AI could drive adoption, but that doesn’t necessarily translate into AI-provider profitability. | |||||
| Fixed income | ||||||
| Short US Treasuries | We are neutral. We prefer short- and medium-term Treasuries, given the attractive risk-adjusted income on offer. | |||||
| Long US Treasuries | We are underweight. We see investors wanting more compensation for holding long-term bonds amid persistent inflation and high debt loads. Long-duration bonds also are a less reliable portfolio diversifier in the new regime. | |||||
| Global inflation-linked bonds | We are neutral. We see inflation settling above pre-pandemic levels, but markets may not price this in the near term as economic growth could slow. | |||||
| Euro area government bonds | We are neutral short- and medium-term bonds. Current ECB rate pricing looks fairly valued given the balance of risks. Higher energy prices could push rates higher. We prefer to deploy risk elsewhere. | |||||
| UK Gilts | We are neutral. We expect periods of elevated volatility given political uncertainty, longer-term bonds making up a larger market share, and buyers becoming more price-sensitive. | |||||
| Japanese government bonds | We are underweight. Rate hikes, higher global term premium and heavy bond issuance will likely drive yields up further. | |||||
| China government bonds | We are neutral. China bonds offer stability and diversification but developed market yields are higher. A shift in investor sentiment toward equities limits upside. | |||||
| US agency MBS | We are overweight. Agency MBS offer higher income than Treasuries with similar risk and may offer more diversification amid fiscal and inflationary pressures. | |||||
| Short-term IG credit | We are neutral. Spreads are tight due to corporate strength; they could widen if issuance increases or risk appetite shifts. | |||||
| Long-term IG credit | We are underweight. We prefer short-term bonds less exposed to interest rate risk over long-term bonds. | |||||
| Global high yield | We are neutral. High yield offers attractive income. We prefer higher-rated US and European high yield over investment grade and see dispersion of returns increasing. | |||||
| Asia credit | We are neutral. Overall yields are attractive and fundamentals are solid, but spreads are tight. | |||||
| Emerging hard currency | We are neutral. Fundamentals have improved, but we see a more attractive risk-reward profile in EM local debt. | |||||
| Emerging local currency | We are overweight. We like the yield relative to its volatility and improving fundamentals. | |||||
Past performance is not a reliable indicator of current or future results. It is not possible to invest directly in an index. Note: Views are from a US dollar perspective. This material represents an assessment of the market environment at a specific time and is not intended to be a forecast or guarantee of future results. This information should not be relied upon as investment advice regarding any particular fund, strategy or security.
Euro-denominated tactical granular views
Six to 12-month tactical views on selected assets vs. broad global asset classes by level of conviction, September 2026

We have lengthened our tactical investment horizon back to six to 12 months. The table below reflects this and, importantly, leaves aside the opportunity for alpha, or the potential to generate above-benchmark returns – especially at a time of heightened volatility.
| Asset | Tactical view | Commentary | ||
|---|---|---|---|---|
| Equities | ||||
| Europe ex UK | We are neutral. We would need to see more business-friendly policy and deeper capital markets for Europe to outperform and to justify a broad overweight. We stay selective, favoring financials, infrastructure, industrials, materials and healthcare. | |||
| Germany | We are neutral. Higher spending on defense and infrastructure support the corporate sector. Valuations are not stretched but neither compelling and expected earnings growth lags other countries. Light positioning means potential easing in geopolitical tensions and AI lifting industrials-driven earnings could create opportunities. | |||
| France | We are neutral. Strong expected earnings growth and global revenue exposure support French corporates. Valuations are less compelling, albeit not stretched versus euro area peers. Persistent political uncertainty leaves the overall risk reward balanced. | |||
| Italy | We are neutral. Earnings growth and momentum are strong, boosted by the significant exposure to financials, utilities and energy. Valuations are still at discount vs. peers, but not as much as in previous years. Political risk is currently low but likely to pick up ahead of 2027 elections. | |||
| Spain | We are overweight. Valuations remain attractive vs. peers even if relative earnings momentum has slowed. Strong domestic demand growth and exposure to fast-growing areas like Latin America support Spanish stocks. Financials, utilities and infrastructure-linked stocks would benefit from Europe’s push towards autonomy. | |||
| Netherlands | We are neutral. Earnings revisions in the IT sector, a large sector in the Dutch stock market is offset by other sectors seeing less favorable valuations and a weaker earnings outlook than European peers. | |||
| Switzerland | We are neutral. Valuations have improved, from stretched levels, but the earnings outlook is weaker than other European markets. If global risk appetite stays strong, the index’s tilt to stable, less volatile sectors may weigh on performance. | |||
| UK | We are neutral. Valuations remain attractive relative to the US, but we see few near-term catalysts to trigger a shift. | |||
| Fixed income | ||||
| Euro area government bonds | We are neutral short- and medium-term bonds. Current ECB rate pricing looks fairly valued given the balance of risks. Higher energy prices could push rates higher. We prefer to deploy risk elsewhere. | |||
| German bunds | We are neutral Bunds. Current ECB rate pricing looks more fairly valued given the balance of risks. Fiscal stimulus and increased bond issuance exert upward pressure on yields, alongside inflation risks amid lingering geopolitical tensions. | |||
| French OATs | We are neutral. Elevated political uncertainty, high budget deficits and slow structural reforms could stoke volatility, but these risks already seem priced into OATs and we don’t expect a material worsening from here. | |||
| Italian BTPs | We are neutral. The spread over German bunds looks tight given Italy’s large budget deficits and growing public debt. Domestic factors remain supportive, with growth holding up relative to the rest of the euro area and local demand for BTPs solid at current yield levels. Domestic disapproval would likely prevent defense spending from reaching fiscally unstable levels. Political uncertainty is likely to increase ahead of next year’s elections. | |||
| UK gilts | We are neutral. We expect periods of elevated volatility given political uncertainty, longer-term bonds making up a larger market share, and buyers becoming more price-sensitive. | |||
| Swiss government bonds | We are neutral. The SNB seems comfortable with its medium-term inflation outlook and its current policy stance. Market pricing is broadly in line with SNB messaging. | |||
| European inflation-protected securities | We are neutral. We see higher medium-term inflation, but inflation expectations are firmly anchored. Cooling inflation and uncertain growth may matter more near term. | |||
| European investment grade | European investment grade is supported by healthy corporate sector balance sheets, contained default rates and the persistently strong demand for durable income from European households. We prefer European investment grade over the US. | |||
| European high yield | We are overweight. While spreads are low, the income potential remains attractive. Defaults are contained and high yield is of higher quality and less sensitive to interest rate swings compared with the US. | |||
Past performance is not a reliable indicator of current or future results. It is not possible to invest directly in an index. Note: Views are from a euro perspective, September 2026. This material represents an assessment of the market environment at a specific time and is not intended to be a forecast or guarantee of future results. This information should not be relied upon as investment advice regarding any particular fund, strategy or security.
Meet the authors
This material is for distribution to Professional Clients (as defined by the Financial Conduct Authority or MiFID Rules) and Qualified Investors only and should not be relied upon by any other persons.
Issued by BlackRock Investment Management (UK) Limited, authorised and regulated by the Financial Conduct Authority. Registered office: 12 Throgmorton Avenue, London, EC2N 2DL. Tel: 020 7743 3000. Registered in England No. 2020394. For your protection telephone calls are usually recorded. BlackRock is a trading name of BlackRock Investment Management (UK) Limited.
Past performance is not a reliable indicator of current or future results and should not be the sole factor of consideration when selecting a product or strategy.
Capital at risk. The value of investments and the income from them can fall as well as rise and is not guaranteed. You may not get back the amount originally invested. Changes in the rates of exchange between currencies may cause the value of investments to diminish or increase. Fluctuation may be particularly marked in the case of a higher volatility fund and the value of an investment may fall suddenly and substantially. Levels and basis of taxation may change from time to time.
Any research in this document has been procured and may have been acted on by BlackRock for its own purpose. The results of such research are being made available only incidentally. The views expressed do not constitute investment or any other advice and are subject to change. They do not necessarily reflect the views of any company in the BlackRock Group or any part thereof and no assurances are made as to their accuracy.
This document is for information purposes only and does not constitute an offer or invitation to anyone to invest in any BlackRock funds and has not been prepared in connection with any such offer.
© 2026 BlackRock, Inc. All Rights reserved. BLACKROCK, BLACKROCK SOLUTIONS, iSHARES, BUILD ON BLACKROCK and SO WHAT DO I DO WITH MY MONEY logo are registered and unregistered trademarks of BlackRock, Inc. or its subsidiaries in the United States and elsewhere. All other trademarks are those of their respective owners.