Skip to content

Welcome to the BlackRock site for Qualified Clients and Sophisticated Investors.
Before you proceed, please take a moment to review and accept the following Terms and Conditions.
The information and material on this website, including any offering document, is intended to be used for information purposes only. None of the information constitutes an offer to the public of securities or fund units under any applicable legislation (including but not limited to the Israeli Securities Law, 1968 and the Israeli Joint Investment Trust Law, 1994), or an offer to sell, or a solicitation or an offer to purchase, any financial instruments, including but not limited to the investment products.
The Qualified Client/Sophisticated Investor section of this website and its content is restricted to “Qualified Clients”/Sophisticated Investors” (as defined below) only and is not intended for retail or private investors who are not “Qualified Clients” or “Sophisticated Investors”.
For the purposes of these terms, references to a "Qualified Client" mean a qualified client pursuant to the First Schedule to the Israeli Regulation of Investment Advice, Investment Marketing and Investment Portfolio Management Law, 1995 (“the Investment Advice Law”), while reference to “Sophisticated Investors” mean a qualified investor pursuant to the Israeli Securities Law, 1968 (the "Securities Law”).
By clicking below, you confirm and consent to meet the definition of Qualified Client/Sophisticated Investor, to have the relevant knowledge and experience to receive the detailed information and documents about BlackRock and iShares products and to fall within one of the following categories:
Qualified Client:
- a joint investment trust fund or a Fund Manager
- a management company or a provident fund as defined in the Control of Provident Funds Law
- a licensed insurance company
- an underwriter qualified in accordance with Section 56 (c) of the Securities Law investing for its own account
- a licensed banking corporation and auxiliary body corporate, as defined by Israeli Banking (Licensing) Law 1981, other than a joint service company
- a licensee under the Investment Advice Law
- a member of the Tel Aviv Stock Exchange
- an entity which is wholly owned by an entity which falls within this list;
- an unlicensed corporation (other than an entity that incorporated in order to obtain services) whose equity capital exceeds NIS 50 million
- A corporation incorporated abroad, with characteristics of activity similar to those of a corporation named in this list
Sophisticated Investor:
- A mutual fund or a company that manages a fund
- a licensed provident fund
- a venture capital fund1
- a licensed management company that manages a provident fund
- a licensed insurance company
- A corporation with 50 million ILS equity
- an underwriter qualified in accordance with Section 56 (c) of the Securities Law investing for its own account
- a licensed banking corporation or auxiliary corporation as defined by Israeli Banking (Licensing) Law 1981 which intends to invest for its own account or for entities which fall within this list
- a licensed portfolio management company investing for its own account or for entities which fall within this list
- a licensed investment advising company or investment marketing company as defined in the Investment Advice Law investing for its own account
- a member of the Tel Aviv Stock Exchange investing for its own account or for entities which fall within this list
- an entity which is wholly owned by an entity which falls within this list;
In accessing the website as a Qualified Client or Sophisticated Investor you will be undertaking, warranting and representing to the BlackRock Group that you are a Qualified Client or Sophisticated Investor, as applicable. Please note that BlackRock will be acting in reliance upon your undertaking, warranty and representation.
As a matter of general policy, BlackRock will not conduct regulated investment activities with any person as a result of their receiving information from the website, unless agreed otherwise with a Qualified Client or Sophisticated Investor. Anyone who is not a Qualified Client or a Sophisticated Investor should not access the Website.
You understand and consent that due to your classification as a Sophisticated Investor, the protections granted to investors under the Securities Law will not be available for you. For example, you may be offered and sold investments that are not regulated or supervised by the ISA, that are not subject to any disclosure obligations (accordingly, there might be no available information with respect to thereto), and that are not permitted to be publicly offered in Israel) and consent thereto. Furthermore, you understand and consent that even if any information provided by BlackRock was considered "Investment Marketing" (without derogating from the fact that it should not be treated as such), BlackRock would not be required to comply with the following requirements of the Investment Advice Law, due to your classification as a Qualified Clients: (1) ensuring the compatibility of service to the needs of client; (2) engaging in a written agreement with the client, the content of which is as described in section 13 of the Investment Advice Law; (3) providing the client with appropriate disclosure regarding all matters that are material to a proposed transaction or to the advice given; (4) a prohibition on preferring certain Securities or other Financial Assets; (5) providing disclosure about "extraordinary risks" entailed in a transaction (and obtaining the client's approval of such transactions, if applicable); (6) a prohibition on making Portfolio Management fees conditional upon profits or number of transactions; (7) maintaining records of advisory/discretionary actions. Based on all of the above, you confirm that you are aware of the consequences of being classified as a Qualified Client and a Sophisticated Investor, including the consequences listed above, request and consent to be classified as a Qualified Client and a Sophisticated Investor.
By accessing this website, you consent to receive information on this website in English, unless you inform us otherwise.
Please note that the Privacy Policy includes important information on the use of cookies on our website, to which you agree by clicking above.
Legal Information
None of the material within this website is intended to be relied upon as a forecast, research or investment advice, and is not a recommendation, offer or solicitation to buy or sell any securities or financial product or to adopt any investment strategy. Any opinions expressed may change as subsequent conditions vary. The information and opinions contained in this material are derived from proprietary and non-proprietary sources deemed by BlackRock to be reliable, are not necessarily all-inclusive and are not guaranteed as to accuracy. Any investments named within this material may not necessarily be held in any accounts managed by BlackRock. Reliance upon information in this material is at the sole discretion of the reader. Past performance is no guarantee of future.
BlackRock Investment Management (UK) Limited is not licensed as, a portfolio manager, investment adviser or investment manager under the Investment Marketing and Investment Portfolio Management Law- 1995 (the "Advice Law") or any other applicable law, nor does it carry insurance as required thereunder. BlackRock Investment Management (UK) Limited is not, and will not be providing any investment advice, investment marketing or portfolio management services to the Investor. BlackRock and the Funds managed by BlackRock are not subject to the laws and supervision that apply to mutual funds in Israel.
BlackRock benefits from investments made by investors in Israel in the products mentioned in this website, as well as in other products managed by third parties with whom BlackRock is involved in a business contract. In particular, BlackRock manages the foreign funds mentioned in this website, and therefore benefits from investments of Israeli investors in them (inter alia, by charging a "management fee" as specified in the prospectus and in the Annex to the prospectuses of such funds). Therefore, BlackRock has a "Connection" to such products, a personal interest in their sale, and might prefer such products over other products. Accordingly, any advice BlackRock provides, is considered, for the purpose of the Investment Advice Law, as Investment Marketing (and not Investment Advising). The complete and updated information regarding the names of such asset managers to the products of which BlackRock has a "connection" (and the types of products issued by each one) is available upon request.
Accessibility statement
BlackRock is committed to making its websites accessible following the current Web Content Accessibility Guidelines (WCAG).. These improvements are part of our broader effort to meet legal and regulatory requirements and to ensure an inclusive digital experience for all users.
By accepting these terms and conditions, you consent to communicate with us in English unless you inform us otherwise.
1“Venture Capital Fund” means a corporation primarily engaged in investments in other corporations which are engaged, at the time of the investment, in research and development or in the production of innovative or high technology products or processes, and where the risk of such investment is typically higher than the risk involved in other investments.
BlackRock Investment Management (UK) Limited is not licensed as, a portfolio manager, investment adviser or investment manager under the Investment Marketing and Investment Portfolio Management Law- 1995 (the "Advice Law") or any other applicable law, nor does it carry insurance as required thereunder. BlackRock Investment Management (UK) Limited is not, and will not be providing any investment advice, investment marketing or portfolio management services to the Investor.
I/We confirm that each time I/We log onto to this website, that I/We are Qualified Investors as such term is defined under the Securities Law of 1968 and Qualified Clients under the Advice Law and understand that this website is designated solely for Qualified Investors that are also Qualified Clients, and will not be permitted to view or access the content thereof until I confirm my status as such. I am aware and consent to the implications of being designated as a Qualified Investor and a Qualified Client, including not being entitled to certain protection available under law. Should this status as a Qualified Investor and Qualified Client change, I/We will inform BlackRock Investment Management (UK) Limited which may have the impact of limiting or withdrawing access to the website.


The Mideast energy shock’s next phase
Market take
Weekly video_20261026
Ehsan Khoman
Economist
BlackRock Investment Institute
SCRIPT
Header:
CAPITAL AT RISK. MARKETING MATERIAL.
Opening frame: What’s driving markets? Market take
Camera frame
Title slide: The Middle East energy shock’s next phase
The global economy proved resilient to the Middle East energy shock. Now, buffers that helped soften the initial hit to economic growth like strategic reserves and rerouted oil shipments are weakening, and supply constraints are moving downstream.
1: A more nuanced story
Brent crude oil jumped to a five-month high last week. But oil prices are only part of the evolving Middle East conflict story. Early on, the focus was on crude supply. Now, the pressure has moved downstream to refining and shipping bottlenecks. That’s pushed up the delivered cost of fuel and helped refinery and tanker stocks far outpace major oil and gas producers. After those sharp gains, what matters now is which bottlenecks persist, even if the conflict ends.
2: Uneven effects
The global economy has weathered the energy shock better than expected, thanks to AI investment and government spending, but not everyone is feeling it equally. Europe is more vulnerable, particularly with gas reserves at historically low levels heading into winter. Meanwhile, the US has so far had a much bigger cushion as a net energy exporter.
That’s accelerating the push for more resilient energy systems. Importers are diversifying their energy supplies, while exporters are investing in new routes around vulnerable chokepoints. We think that shift could outlast the conflict, creating investment opportunities but also requiring huge amounts of capital and putting upward pressure on government bond yields.
3: Selectivity is key
So, where does that leave us as investors? The focus is on refining and energy infrastructure, or where bottlenecks could persist. We’re also selective across regions, with Europe more exposed to higher energy costs and the US less exposed to the worst outcomes.
In bonds, higher yields have made US Treasuries more attractive. We prefer shorter-term bonds for their income, as the investment needed to strengthen energy security could put upward pressure on longer-term yields.
Outro: Here’s our Market take
We think some of today’s energy constraints could outlast the Middle East conflict. That keeps us selective, favoring opportunities where energy constraints and margins look durable.
Closing frame: Read details: blackrock.com/weekly-commentary
An evolving conflict
The Middle East conflict is exposing longer-term energy constraints as buffers that absorbed the initial shock weaken. Selectivity is key in this environment.
Market backdrop
The Nasdaq fell nearly 1% last week and US Treasuries rallied as investors sought safety from the tech stock selloff. Brent crude oil hit a six-month high.
Week ahead
We eye the Fed’s second-to-last policy meeting of 2026. We expect another hike by year-end but see market pricing for further tightening as overly hawkish.
The global economy and markets have proved resilient to the Middle East energy shock. Strong AI investment and fiscal spending have cushioned the hit to growth, while supply buffers helped absorb much of the initial shock. Now, renewed attacks targeting energy sites and shipping in the Gulf are testing these buffers just as they’re thinning, while supply constraints are moving downstream. Selectivity is key as new vulnerabilities emerge across regions, sectors and asset classes.
Paragraph-2,Image-1,Paragraph-3
Paragraph-4,Advance Static Table-1,Paragraph-5,Advance Static Table-2,Paragraph-6,Advance Static Table-3
Scarcity pays downstream
Selected oil industry sub-sector equity performance, 2026

Past performance is not a reliable indicator of current or future results. Source: BlackRock Investment Institute with data from Bloomberg, October 2026. The chart shows the equal-weighted average equity returns of selected companies across four oil industry sub-sectors, rebased to 100 on Jan. 2, 2026. Returns are based on weekly observations and exclude dividends.
Brent crude oil surged back to around $117 a barrel last week, its highest since April. But oil prices tell only part of the story of how the energy shock has evolved. The initial disruption centered on crude supply, but rerouted shipments, inventories and strategic reserves helped absorb much of the shock. Now scarcity has shifted downstream. Even as crude supplies recover, refining and shipping bottlenecks have pushed the delivered cost of fuel from the Middle East to Asia to more than twice prewar levels. This helps explain why shares of refiners have jumped some 160% this year, while shares of tanker operators have climbed 120%. See the chart. Both have far outpaced the 40% gain in major oil and gas producers, even as energy has become the top-performing sector globally. But after such sharp gains, how much further these stocks can run depends on which bottlenecks persist, even if the conflict ends.
Global growth has held up thanks to strong AI investment and government spending. Much of the initial inflation shock is already reflected in headline inflation, but higher fuel costs are starting to feed into some core inflation categories. As we’ve previously noted, the energy shock has uneven effects: we estimate it’s reduced GDP by about 0.5% in Europe, compared with just 0.1% in the US Those differences could become even more pronounced. Europe looks particularly vulnerable, with natural gas storage at around 75% – its lowest seasonal level since recordkeeping began in 2011 – while disrupted supplies of liquefied natural gas complicate efforts to rebuild reserves. A colder winter could push European energy prices, already up 170% this year, higher. The US is better insulated as a net energy exporter, while strong tech exports have cushioned Asia from higher import costs. The shock’s uneven impacts are accelerating efforts to bolster energy resilience and security.
Selectivity is key
That is creating new investment opportunities – but at a cost. The geopolitical fragmentation mega force we’ve long described reinforces this shift, raising the value of infrastructure that protects against future shocks. Energy importers are diversifying both traditional fuel supplies and electrification, underscoring the energy transition and resilience mega force. Exporters, including those in the Middle East, are investing in alternative routes to bypass vulnerable chokepoints. We see this as a structural shift that could outlast the conflict. Yet building these contingencies requires substantial investment, which could intensify competition for capital and put further upward pressure on sovereign bond yields.
We favor opportunities where energy constraints and profit margins look durable and valuations remain attractive. For now, existing energy equity exposures could deliver strong earnings as oil prices and refining margins stay elevated. But after this year’s oil rally, we also see opportunities in select US and European utilities hit by rising bond yields. In bonds, higher yields support our recent upgrade to US Treasuries. We prefer short-term bonds for income, as growing energy security investment could increase competition for capital and push longer-term yields higher.
Our bottom line
The Mideast energy shock is exposing longer-term constraints that could outlast the conflict. We favor selective exposure to energy infrastructure and short-term income over broad market bets.
Market backdrop
Tech stocks swung sharply last week as investors stepped up scrutiny of the AI trade, pushing the Nasdaq down roughly 1% despite strong earnings from some of the sector’s biggest names. The S&P 500 fell 0.4%, with a rotation into defensive sectors helping limit losses. US 10-year Treasury yields slipped below 5% as investors sought refuge from the tech selloff. Brent crude oil touched a six-month high of $117 a barrel on concerns about further disruption to Middle East energy flows.
The Federal Reserve’s interest rate decision takes center stage this week after a hotter-than-expected September CPI report showed price pressures broadening. Even as we expect another hike by year-end, we don’t view recent tightening as the start of a sustained hiking cycle. Markets have partially scaled back expectations for further hikes since the September meeting, moving closer to our view.
Week ahead

Past performance is not a reliable indicator of current or future results. Indexes are unmanaged and do not account for fees. It is not possible to invest directly in an index. Sources: BlackRock Investment Institute, with data from LSEG Datastream as of October 22, 2026. Notes: The two ends of the bars show the lowest and highest returns at any point year to date, and the dots represent current year-to-date returns. Emerging market (EM), high yield and global corporate investment grade (IG) returns are denominated in US dollars, and the rest in local currencies. Indexes or prices used are: spot Brent crude, ICE US Dollar Index (DXY), spot gold, spot bitcoin, MSCI Emerging Markets Index, MSCI Europe Index, LSEG Datastream 10-year benchmark government bond index (US, Germany and Italy), Bloomberg Global High Yield Index, J.P. Morgan EMBI Index, Bloomberg Global Corporate Index and MSCI USA Index.
Oct. 27
US consumer confidence; Japan services PPI
Oct. 28
US Fed rate decision
Oct. 29
US GDP & PCE
Oct. 30
EU flash GDP & unemployment; BoJ rate decision; Japan CPI
Read our past weekly commentaries here.
Intersecting mega forces
Since we launched our mega forces framework it has become clearer how their intersection shapes almost all our investment views and opens up alpha opportunities. They cut across asset class labels, spurring a rethink of portfolio construction. Investors need to be deliberate about the economic or thematic exposures they own, the vehicles they use to implement them and their investment horizons.

From drivers to portfolio expressions
Our highest conviction views, October 2026
| Driver | What we think | Portfolio expression |
|---|---|---|
| Growth and AI scarcity | AI fundamentals are strong, but we eye near-term volatility. | Neutral US equities and overweight EM equities; favor AI- and tech-related opportunities. |
| Duration and diversification | Higher starting yields improve prospective returns and income. | Overweight short-term US Treasuries for solid income and a cushion against higher rates; neutral long-term Treasuries |
| Credit spreads and liquidity | Selectivity is crucial amid tight spreads and uneven fundamentals. | Credit with clear cash flows, lender protections and recovery value; higher-rated high yield. |
| Inflation and scarcity | Scarcity, secure supply and power demand carry inflation risks. | Infrastructure, energy bottlenecks, EM local debt and real-asset-linked exposures. |
| Alpha opportunity | Macro outcomes matter again in the new regime. | Macro hedge funds, venture capital, market-neutral strategies, and selected private credit and non-US alpha. |
Note: Views are from a US dollar perspective, October 2026. This material represents an assessment of the market environment at a specific time and is not intended to be a forecast of future events or a guarantee of future results. This information should not be relied upon by the reader as research or investment advice regarding any particular funds, strategy or security.
Asset class implications
Six- to 12-month tactical positioning, October 2026
This shows the implementation of our key investment views from the previous page through an asset class lens.

| Asset | Tactical view | Commentary | ||||
|---|---|---|---|---|---|---|
| Equities | ||||||
| United States | 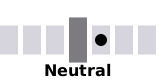 |
We are neutral. Strong AI fundamentals remain supportive, but policy uncertainty could fuel near-term volatility. We continue to favor AI and tech. | ||||
| Europe | 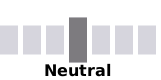 |
We are neutral. We would need to see more business-friendly policy and deeper capital markets for Europe to outperform. We favor financials, infrastructure, and industrials. | ||||
| UK | |
We are neutral. Valuations remain attractive relative to the US, but we see few near-term catalysts to trigger a shift. | ||||
| Japan | |
We are neutral. Strong corporate balance sheets and governance reforms remain supportive. We prefer targeted exposures to physical AI and the buildout’s bottlenecks. | ||||
| Emerging markets (EM) |  |
We are overweight. Strong earnings and cheaper valuations create opportunities. We particularly like different expressions of the AI scarcity theme across Asia and Latin America. | ||||
| China | |
We are neutral. We see opportunities in physical AI. Cheap, open-source AI could drive adoption, but that doesn’t necessarily translate into AI-provider profitability. | ||||
| Fixed income | ||||||
| Short US Treasuries | |
We are overweight. Much of the repricing we anticipated has occurred, and expectations for further Fed hikes look excessive. We favor the front end for attractive income and a greater breakeven buffer. | ||||
| Long US Treasuries | 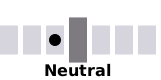 |
We are neutral. Higher yields offer attractive income and a bigger cushion against further rate increases. We still see room for yields to rise as competition for capital intensifies. | ||||
| Global inflation-linked bonds | |
We are neutral. We see inflation settling above pre-pandemic levels, but markets may not price this in the near term as economic growth could slow. | ||||
| Euro area government bonds | |
We are neutral short- and medium-term bonds. Current ECB rate pricing looks fairly valued given the balance of risks. Higher energy prices could push rates higher. We prefer to deploy risk elsewhere. | ||||
| UK Gilts | |
We are neutral. We expect periods of elevated volatility given political uncertainty, longer-term bonds making up a larger market share, and buyers becoming more price-sensitive. | ||||
| Japanese government bonds |  |
We are underweight. The substantial repricing in yields has improved the risk-reward, but further rate hikes and heavy issuance could push yields higher. | ||||
| China government bonds | |
We are neutral. China bonds offer stability and diversification but developed market yields are higher. A shift in investor sentiment toward equities limits upside. | ||||
| US agency MBS | |
We are neutral and lean into the stable income MBS provide despite tight spreads. | ||||
| Short-term IG credit | |
We are neutral. Spreads are tight due to corporate strength; they could widen if issuance increases or risk appetite shifts. | ||||
| Long-term IG credit | 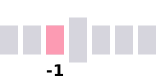 |
We are underweight. We prefer short-term bonds less exposed to interest rate risk over long-term bonds. But attractive overall yields help offset the risk of increased issuance. | ||||
| Global high yield | |
We are neutral. High yield offers attractive income. We prefer higher-rated US and European high yield over investment grade and see dispersion of returns increasing. | ||||
| Asia credit | |
We are neutral. Overall yields are attractive and fundamentals are solid, but spreads are tight. | ||||
| Emerging hard currency | |
We are neutral. Fundamentals have improved, but we see a more attractive risk-reward profile in EM local debt. | ||||
| Emerging local currency | |
We are overweight. We like the yield relative to its volatility and improving fundamentals. | ||||
Past performance is not a reliable indicator of current or future results. It is not possible to invest directly in an index. Note: Views are from a US dollar perspective. This material represents an assessment of the market environment at a specific time and is not intended to be a forecast or guarantee of future results. This information should not be relied upon as investment advice regarding any particular fund, strategy or security.
Euro-denominated tactical granular views
Six to 12-month tactical views on selected assets vs. broad global asset classes by level of conviction, October 2026
We have lengthened our tactical investment horizon back to six to 12 months. The table below reflects this and, importantly, leaves aside the opportunity for alpha, or the potential to generate above-benchmark returns – especially at a time of heightened volatility.
| Asset | Tactical view | Commentary | ||
|---|---|---|---|---|
| Equities | ||||
| Europe ex UK | |
We are neutral. We would need to see more business-friendly policy and deeper capital markets for Europe to outperform and to justify a broad overweight. We stay selective, favoring financials, infrastructure, industrials, materials and healthcare. | ||
| Germany | |
We are neutral. Higher spending on defense and infrastructure support the corporate sector. Valuations are not stretched but neither compelling and expected earnings growth lags other countries. Light positioning means potential easing in geopolitical tensions and AI lifting industrials-driven earnings could create opportunities. | ||
| France | |
We are neutral. Strong expected earnings growth and global revenue exposure support French corporates. Valuations are less compelling, albeit not stretched versus euro area peers. Persistent political uncertainty leaves the overall risk reward balanced. | ||
| Italy | |
We are neutral. Earnings growth and momentum are strong, boosted by the significant exposure to financials, utilities and energy. Valuations are still at discount vs. peers, but not as much as in previous years. Political risk is currently low but likely to pick up ahead of 2027 elections. | ||
| Spain |  |
We are overweight. Valuations remain attractive vs. peers even if relative earnings momentum has slowed. Strong domestic demand growth and exposure to fast-growing areas like Latin America support Spanish stocks. Financials, utilities and infrastructure-linked stocks would benefit from Europe’s push towards autonomy. | ||
| Netherlands | |
We are neutral. Earnings revisions in the IT sector, a large sector in the Dutch stock market is offset by other sectors seeing less favorable valuations and a weaker earnings outlook than European peers. | ||
| Switzerland |  |
We are neutral. Valuations have improved, from stretched levels, but the earnings outlook is weaker than other European markets. If global risk appetite stays strong, the index’s tilt to stable, less volatile sectors may weigh on performance. | ||
| UK | |
We are neutral. Valuations remain attractive relative to the US, but we see few near-term catalysts to trigger a shift. | ||
| Fixed income | ||||
| Euro area government bonds | |
We are neutral short- and medium-term bonds. Current ECB rate pricing looks fairly valued given the balance of risks. Higher energy prices could push rates higher. We prefer to deploy risk elsewhere. | ||
| German bunds | |
We are neutral Bunds. Current ECB rate pricing looks more fairly valued given the balance of risks. Fiscal stimulus and increased bond issuance exert upward pressure on yields, alongside inflation risks amid lingering geopolitical tensions. | ||
| French OATs | |
We are neutral. Elevated political uncertainty, high budget deficits and slow structural reforms could stoke volatility, but these risks already seem priced into OATs and we don’t expect a material worsening from here. | ||
| Italian BTPs | |
We are neutral. The spread over German bunds looks tight given Italy’s large budget deficits and growing public debt. Domestic factors remain supportive, with growth holding up relative to the rest of the euro area and local demand for BTPs solid at current yield levels. Domestic disapproval would likely prevent defense spending from reaching fiscally unstable levels. Political uncertainty is likely to increase ahead of next year’s elections. | ||
| UK gilts | |
We are neutral. We expect periods of elevated volatility given political uncertainty, longer-term bonds making up a larger market share, and buyers becoming more price-sensitive. | ||
| Swiss government bonds | |
We are neutral. The SNB seems comfortable with its medium-term inflation outlook and its current policy stance. Market pricing is broadly in line with SNB messaging. | ||
| European inflation-protected securities | |
We are neutral. We see higher medium-term inflation, but inflation expectations are firmly anchored. Cooling inflation and uncertain growth may matter more near term. | ||
| European investment grade | |
European investment grade is supported by healthy corporate sector balance sheets, contained default rates and the persistently strong demand for durable income from European households. We prefer European investment grade over the US. | ||
| European high yield | |
We are overweight. While spreads are low, the income potential remains attractive. Defaults are contained and high yield is of higher quality and less sensitive to interest rate swings compared with the US. | ||
Past performance is not a reliable indicator of current or future results. It is not possible to invest directly in an index. Note: Views are from a euro perspective, October 2026. This material represents an assessment of the market environment at a specific time and is not intended to be a forecast or guarantee of future results. This information should not be relied upon as investment advice regarding any particular fund, strategy or security.
Meet the authors

Wei Li
Global Chief Investment Strategist – BlackRock

Chris Weber
Sustainable Investment and Research Analytics – BlackRock Investment Institute

Mark Hume
Portfolio Manager, Thematics and Sectors Team - BlackRock Fundamental Equities

Ehsan Khoman
Economist — BlackRock Investment Institute
This material is for distribution to Professional Clients (as defined by the Financial Conduct Authority or MiFID Rules) and Qualified Investors only and should not be relied upon by any other persons.
Issued by BlackRock Investment Management (UK) Limited, authorised and regulated by the Financial Conduct Authority. Registered office: 12 Throgmorton Avenue, London, EC2N 2DL. Tel: 020 7743 3000. Registered in England No. 2020394. For your protection telephone calls are usually recorded. BlackRock is a trading name of BlackRock Investment Management (UK) Limited.
Past performance is not a reliable indicator of current or future results and should not be the sole factor of consideration when selecting a product or strategy.
Capital at risk. The value of investments and the income from them can fall as well as rise and is not guaranteed. You may not get back the amount originally invested. Changes in the rates of exchange between currencies may cause the value of investments to diminish or increase. Fluctuation may be particularly marked in the case of a higher volatility fund and the value of an investment may fall suddenly and substantially. Levels and basis of taxation may change from time to time.
Any research in this document has been procured and may have been acted on by BlackRock for its own purpose. The results of such research are being made available only incidentally. The views expressed do not constitute investment or any other advice and are subject to change. They do not necessarily reflect the views of any company in the BlackRock Group or any part thereof and no assurances are made as to their accuracy.
This document is for information purposes only and does not constitute an offer or invitation to anyone to invest in any BlackRock funds and has not been prepared in connection with any such offer.
© 2026 BlackRock, Inc. All Rights reserved. BLACKROCK, BLACKROCK SOLUTIONS, iSHARES, BUILD ON BLACKROCK and SO WHAT DO I DO WITH MY MONEY logo are registered and unregistered trademarks of BlackRock, Inc. or its subsidiaries in the United States and elsewhere. All other trademarks are those of their respective owners.
Explore more
Products
-
-
BY ASSET CLASS
-
LITERATURE

© 2026 BlackRock, Inc. All rights reserved.
BII1026-M-6053839-EXP1028