October 27, 2026 | BlackRock
Different by Design: Rethinking the Insurance Model
BlackRock’s 15th Global Insurance Report examines how insurers are combining internal capabilities and external partnerships across investments, liabilities, capital, technology and distribution—contributing to a more connected industry, but not a uniform one.
463
Insurance professionals
31
Markets represented
$24T
Insurance AUM represented
15
Years of survey data
Survey overview
BlackRock’s Global Insurance Report has tracked the evolution of insurer priorities for 15 years. This year’s survey broadens the lens beyond asset allocation to examine the increasing interdependence of decisions across assets, liabilities, capital, technology and distribution.
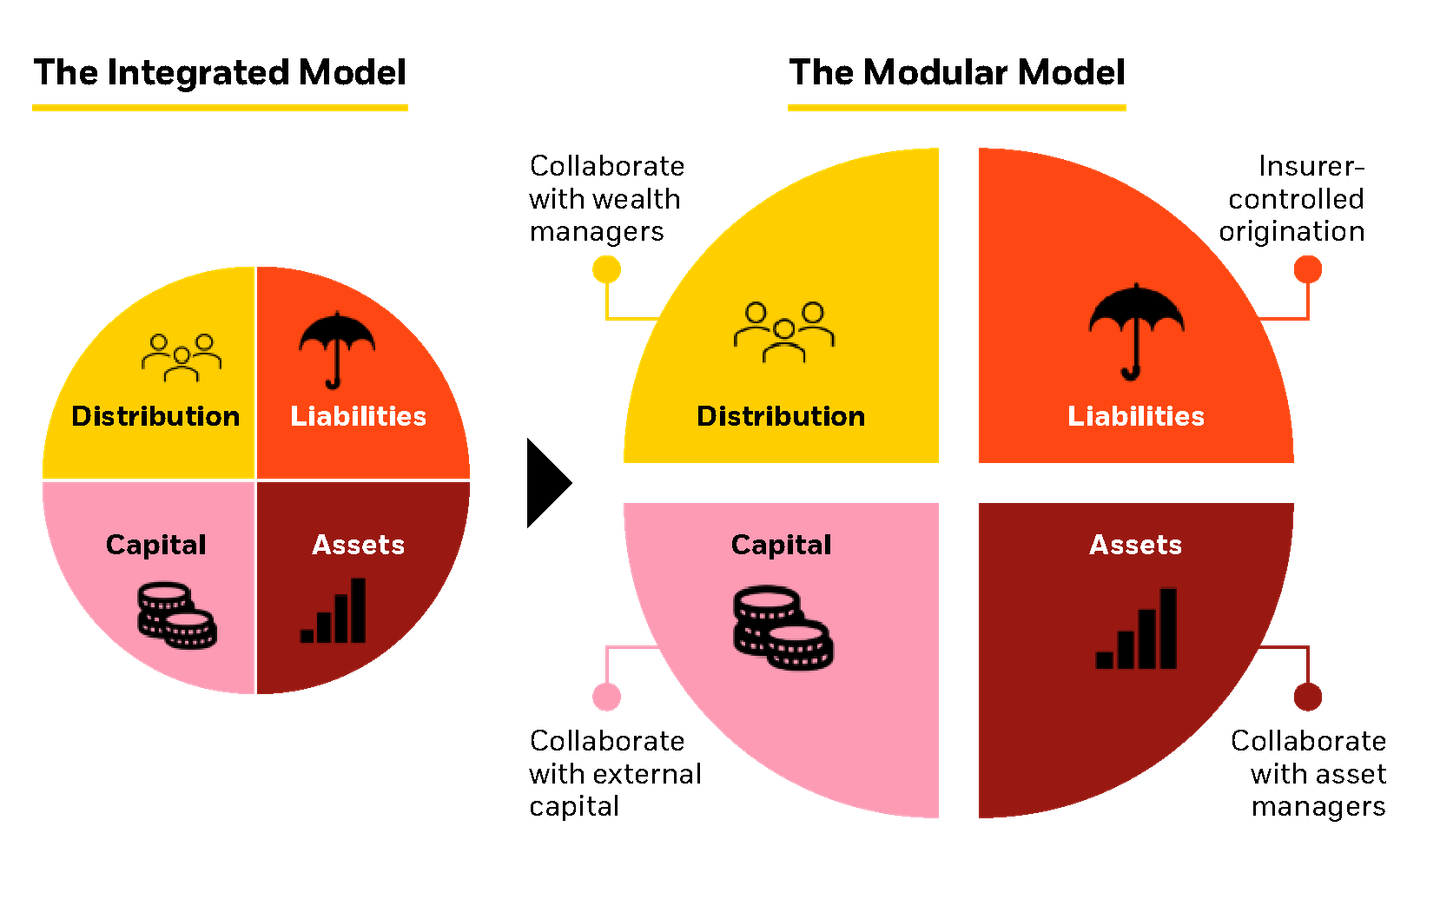
The findings point to a wider range of operating models built around different combinations of internal capabilities and external partners.
The insurance industry has become more modular, but not more uniform.
Source:
BlackRock, as of August 2026..
Five key themes shaping portfolio strategies and operating models
1. Insurers have been transitioning from vertically integrated operating models toward more modular architectures
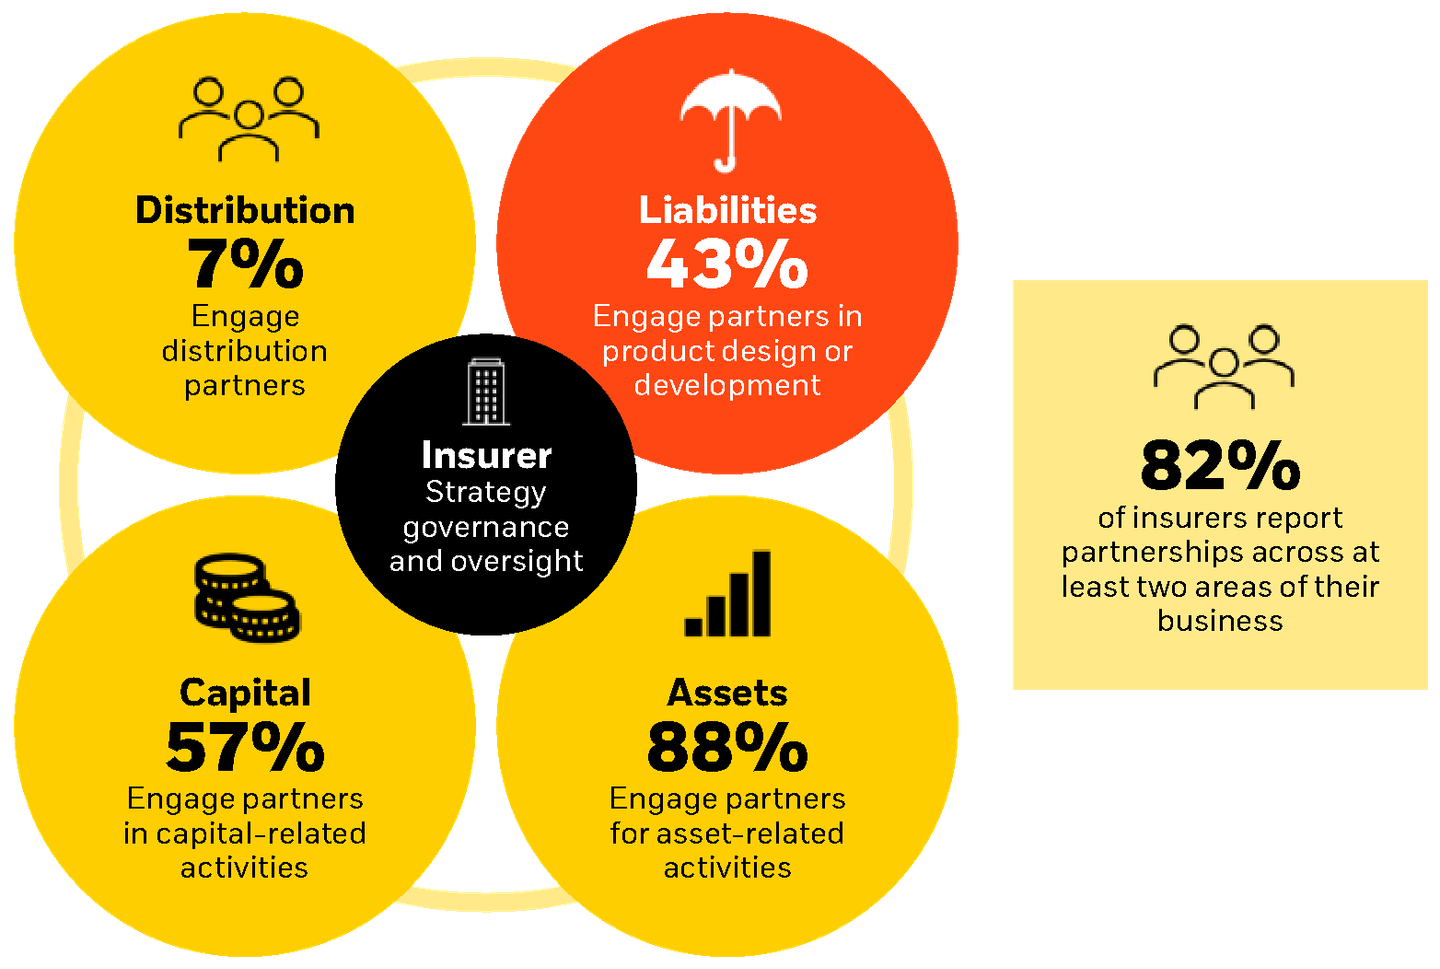
Insurers have increasingly adopted modular operating models, combining internal capabilities with external partners across investments, capital and other core functions, according to our report. Partnerships extend beyond assets to include capital, liabilities and distribution. Insurers have not converged around a single operating model; instead, they are using a wider range of options to align internal and external capabilities with their strategic priorities.
Use of external partners across insurer capabilities
Source:
BlackRock, as of August 2026. For illustrative purposes only.
2. Stable global averages conceal increasingly different strategies
Stable industry averages increasingly mask divergent views and portfolio strategies across regions and insurer segments. 82% of respondents expect to maintain investment risk in 2026, reflecting an industry that has largely adjusted to higher interest rates. Beneath that headline stability, portfolio strategies diverged by firm size, region and economic outlook, shaping portfolio decisions.
Investment risk appetite
Source:
BlackRock, as of August 2026.
Respondents expecting a soft landing
Source:
BlackRock, as of August 2026.
3. Liabilities drive strategy
Liability-specific challenges have been driving different investment priorities, capital needs and operating decisions across business lines. Life and annuity respondents focused on extending liability duration, while property and casualty respondents cite claims severity and inflation. Multiline respondents pointed to increasing complexity; health respondents, to utilization and medical costs; and reinsurers, to tail-event risks.
Top liability profile changes by LOB
Source:
BlackRock. Data as of August 2026.
4. Private markets mature
Over the past decade, private markets have evolved from a source of potential yield into a strategic component of insurers’ investment portfolios. While demand has moderated from a high of 94% in 2025, the reported 76% in 2026 remains one of the highest readings in our survey’s history. In our view, this reflects a shift from broad-based allocation growth toward more selective deployment.
Expected changes to private markets allocations
Source:
BlackRock. Data as of August 2026.
5. AI goes live
Artificial intelligence is moving beyond experimentation toward broader implementation across underwriting, claims, investment and operational workflows. Significant barriers remain, while executives and other respondents view the pace of adoption differently. In our view, closing that gap will require insurers to embed AI more consistently across workflows, decisions and operating models.
AI adoption across insurance workflows
Source:
BlackRock. Data as of August 2026.