Allie Plotsky, Director, Sales Engineering, Aladdin Wealth Tech
The ideal portfolio is often easy to imagine. The challenge is getting there.
For many investors, the portfolio they own today is not the portfolio they ultimately would want to hold. The gap between the two is often shaped by embedded gains, which can reflect successful investment outcomes but can also result in potential tax liabilities and other real-world frictions that make portfolio changes costly to implement. Investors and advisors must constantly weigh the benefits of portfolio improvements against the cost of making them.
Much of the conversation around tax-aware portfolio management centers on navigating those trade-offs. The transition often becomes the focal point.
But a portfolio is never done. By the time one transition is complete, the next reason to change it is already underway.
Markets move. Gains accumulate. Models evolve. Objectives change. Withdrawals occur. Losses surface. The same framework advisors use to navigate a major portfolio transition can be applied continuously, to every decision, for every client, and at scale.
That shift, from a one-time exercise to an ongoing capability, is where firms can create lasting value for taxable investors.
Here's why.
Tax considerations are part of ongoing portfolio management
Much of the same decision-making that takes place during a portfolio transition continues throughout the life of a portfolio. Rebalancing, model updates, new cash contributions, withdrawals, concentration management, and loss harvesting can all involve balancing portfolio objectives with tax liabilities.
Each of these actions can improve a portfolio, but achieving those improvements can come at a cost and may trigger a tax liability that offsets some or all of the benefit.
The most effective portfolio decision is not always the one that produces the highest pre-tax return. It is the one that balances investment outcomes against the tax cost of getting there.
Models define the destination. Personalization shapes the journey.
Risk-factor-based optimization focuses on how efficiently a portfolio can achieve its intended outcome. It is not centered on matching a model security by security.
Let's consider a client holding a large, appreciated technology stock at a significantly higher weight than the target model calls for.
A model-based approach may view that position as a deviation from the target and focus on bringing it back in line with the model. A risk-factor-based approach asks a different question: “How does that over-allocation affect the portfolio's overall exposures, and how does that compare to the intended outcome?”
If the position represents a meaningful overweight to a sector or risk factor, the objective is not necessarily to sell it down immediately. Instead, the challenge is determining how to bring the portfolio closer to its intended outcome without incurring an outsized tax liability. That may involve trimming the position, building the rest of the portfolio around it, or some combination of both.
Viewed through this lens, the question shifts from "How do we reduce this position?" to "What is the most tax-efficient way to achieve the intended outcome and investment objective?"
Personalization does not require abandoning the model
A common misconception about model portfolios is that they cannot accommodate the tax sensitivity, restrictions, and personalization that many high-net-worth and ultra-high-net-worth clients require. Yet a well-constructed optimization engine can account for those considerations without abandoning the model.
Risk-factor-based optimization allows firms to focus on the intended outcome rather than requiring every client portfolio to hold the same securities. Different holdings, embedded gains, tax profiles, constraints, and client-specific restrictions may lead to different implementation decisions, even when clients are pursuing the same investment objective.
As a result, two clients may hold very different portfolios while targeting similar underlying exposures and intended outcomes. A model defines where a portfolio is headed. It should not dictate the specific securities every client must hold to get there.
Deploy the capital gains budget where it creates the most value
Most advisors are already managing capital gains budgets. The challenge is determining how to deploy that budget effectively and create the greatest value for clients.
Not every trade that generates a tax liability delivers the same value. Some may meaningfully reduce tracking error, improve alignment with an intended outcome, or address a concentration risk. Others may generate a similar tax cost while delivering only a modest portfolio benefit.
The difference is not always obvious. Two trades may appear similar on the surface yet create very different outcomes for the client.
The opportunity is to evaluate every trade against that standard: not simply whether it triggers a tax liability, but whether the value it delivers is worth that cost.
Making tax-aware decisions repeatable at scale
A skilled advisor can often do this well for an individual client, weighing risk factors and tax consequences through judgment and experience across transitions, rebalances, and model updates.
Across an enterprise, the challenge is different.
Firms need to evaluate tens of thousands of portfolios, each with their own tax profile, constraints, starting point, and intended outcome. They must determine which trades are worth making, which decisions can be deferred, and where a capital gains budget can be deployed most effectively. Meeting that demand requires a scalable and repeatable process for evaluating portfolio and tax trade-offs consistently and on an ongoing basis, one that can help free up advisors to focus on higher-value activities, such as strategic client conversations and portfolio decisions.
In other words, personalization does not mean managing every portfolio by hand, and scale does not mean building every portfolio the same way. Each portfolio can be managed according to its own facts and circumstances while remaining aligned to a defined objective and a decision-making framework that works across the client base.
A portfolio is never done, whether for one client or 10,000
The broader opportunity extends beyond decision-making for one account at a time. It is making that same level of decision-making available across the client base through a centrally managed, systematic process—and technology is what makes that possible.
It makes that same level of analysis available more consistently across the client base, rather than reserving it for only the most complex client situations.
The payoff is a durable advantage: the ability to extend personalized portfolio management across the client base, rather than limiting it to a select few.
The firms best positioned to lead in this space will be those that can deliver that level of personalization consistently across thousands of portfolios, without sacrificing discipline, oversight, or scale.
A portfolio is never done, and the view should not stop at the account level. The same discipline that guides decisions within a portfolio can extend across the household, where third-party separately managed accounts (SMAs) and other outside holdings become part of a more complete, tax-aware view of the client's portfolio.
Learn how Aladdin Wealth helps firms bring tax-aware, personalized portfolio management to scale.
FOR INSTITUTIONAL, WHOLESALE, QUALIFIED AND PROFESSIONAL INVESTOR/CLIENT USE ONLY.
BlackRock does not provide tax advice. This material is for informational purposes only does not constitute any specific legal, tax or accounting advice. We urge you to consult with a qualified professional for such advice.
Get started with Aladdin Wealth™
Aladdin Wealth™ by BlackRock is an investment management technology platform for wealth management firms, including registered investment advisors (RIAs), broker-dealers, private banks, and other financial institutions. The platform brings together portfolio management, risk and oversight, business insights, and advisor workflows to help firms support growth and efficiency, personalize client portfolios at scale, and take a unified approach to portfolio management.
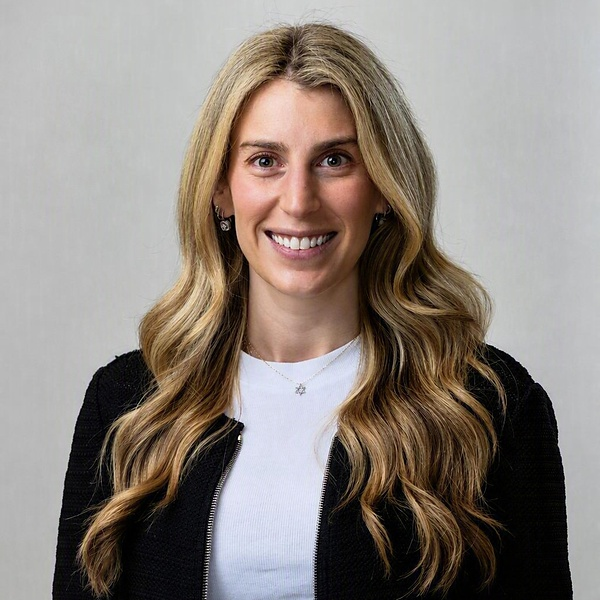
Allie Plotsky
Director, Sales Engineering, Aladdin Wealth Tech
Allie Plotsky partners closely with wealth management firms to help them accelerate growth, drive efficiency, and scale personalized portfolio management. She serves as a strategic technology advisor, helping clients evaluate their technology landscape and identify solutions that support their investment, advisory, and operating model objectives. Allie brings deep technical product knowledge and expertise across portfolio personalization, tax-aware investing, household-level optimization, discretionary portfolio management, and scalable portfolio rebalancing.
Get in touch to learn more about Aladdin®
About us
This material is provided for informational purposes only and is not intended to be relied upon as a forecast, research or investment advice, and is not a recommendation, offer or solicitation to buy or sell any securities or to adopt any investment strategy. The opinions expressed are subject to change at any time without notice. The information and opinions contained in this material are derived from proprietary and nonproprietary sources deemed by BlackRock to be reliable, are not necessarily all-inclusive and are not guaranteed as to accuracy. Performance and risk calculations, including those incorporated into Aladdin technology, are based on assumptions, historical correlations, and other factors (such as inputs provided by the Aladdin users) and are not assured to predict future results. All graphs and screenshots are for illustrative purposes only. BlackRock’s Aladdin platform is a financial technology platform designed for institutional, wholesale, qualified, and professional investor/client use only and is not intended for end investor use. Aladdin users undertake sole responsibility and liability for investment or other decisions related to the technology’s calculations and for compliance with applicable laws and regulations. The technology should not be viewed or construed by any Aladdin users, or their customers or clients, as providing investment advice or investment recommendations to any parties. For additional information on any of the descriptions contained herein, please contact your Aladdin Relationship Management representative. BlackRock may modify or discontinue any functionality or service component described herein at any time without prior advance notice to you.
Certain Aladdin technology products and services may not be offered by BlackRock in your local jurisdiction.
In the U.S. and Canada, this material is intended for institutional investors. In EMEA, this material is for distribution to Professional, Qualified Clients and Investors only. This information is marketing material. For qualified investors in Switzerland: This material shall be exclusively made available to, and directed at, qualified investors as defined in Article 10 (3) of the CISA of 23 June 2006, as amended, at the exclusion of qualified investors with an opting-out pursuant to Art. 5 (1) of the Swiss Federal Act on Financial Services ("FinSA"). For information on art. 8 / 9 Financial Services Act (FinSA) and on your client segmentation under art. 4 FinSA, please see the following website: www.blackrock.com/finsa. In South Africa, a provider who provides products or services to a client other than financial products or financial services, must disclose to the client the fact that the additional products or services are not regulated under the Act and therefore the client is not afforded the same protections in respect of those additional products or services that may apply in respect of the provision of financial products or services in terms of the Act. Please be advised that BlackRock Investment Management (UK) Limited is an authorised Financial Services provider with the South African Financial Services Conduct Authority, FSP No. 43288. In Singapore, this is for use only with institutional investors as defined in Section 4A of the Securities and Futures Act, Chapter 289 of Singapore. In the provision of any of the services described herein, neither BlackRock (nor any of its affiliates) will be acting in a capacity as investment adviser or broker-dealer nor will it be performing the functions of an organized market or exchange (and has not been recognized as doing so by the Monetary Authority of Singapore). In Hong Kong, the technology and the material is for distribution to "Professional Investors" (as defined in the Securities and Futures Ordinance (Cap.571 of the laws of Hong Kong) and any rules made under that ordinance.) and should not be relied upon by any other persons or redistributed to retail clients in Hong Kong. In Japan, this is for Professional Investors only (Professional Investor is defined in Financial Instruments and Exchange Act). In Australia, issued by BlackRock Investment Management (Australia) Limited ABN 13 006 165 975 AFSL 230 523 (BIMAL) for the exclusive use of the recipient who warrants by receipt of this material that they are a wholesale client and not a retail client as those terms are defined under the Australian Corporations Act 2001 (Cth). In Brunei, Indonesia, and Malaysia, this material is issued for institutional investors only. In Latin America, for institutional investors and financial intermediaries only (not for public distribution). No securities regulator within Latin America has confirmed the accuracy of any information contained herein. Please note that IN MEXICO, the provision of investment management and investment advisory services (“Investment Services”) is a regulated activity, subject to strict rules, and performed under the supervision of the Mexican National Banking and Securities Commission (Comisión Nacional Bancaria y de Valores, the “CNBV”). BlackRock does not provide, and it shall not be deemed that it provides through Aladdin technology, any personalized investment advice to the recipient of this document, by reason of its use or otherwise. These materials are shared for information purposes only, do not constitute investment advice, and are being shared in the understanding that the addressee is an Institutional or Qualified investor as defined under Mexican Securities (Ley del Mercado de Valores). Each potential investor shall make its own investment decision based on their own analysis of the available information. Please note that by receiving these materials, it shall be construed as a representation by the receiver that it is an Institutional or Qualified investor as defined under Mexican law. BlackRock México Operadora, S.A. de C.V., Sociedad Operadora de Fondos de Inversión (“BlackRock México Operadora”) is a Mexican subsidiary of BlackRock, Inc., authorized by the CNBV as a Mutual Fund Manager (Operadora de Fondos), and as such, authorized to manage Mexican mutual funds, ETFs and provide Investment Services. For more information on the Investment Services offered by BlackRock Mexico, please review our Investment Services Guide available in www.blackrock.com/mx.
©2026 BlackRock, Inc. or its affiliates. All rights reserved. BLACKROCK and ALADDIN are trademarks of BlackRock, Inc. or its affiliates. All other marks are the property of their respective owners.